Best Home Insurance in Utah for 2026 (Just $77/mo!)
The best home insurance in Utah is with Amica, Chubb, and Liberty Mutual. Travelers offers the lowest rate, starting at $77 per month with a $5K deductible. Utah homeowners insurance companies offer affordable rates, reliable property coverage, policy discounts, and protection against severe winter weather.
Read more
Table of Contents
Table of Contents
Published Insurance Expert
Melanie Musson, a published insurance expert, is the fourth generation in her family to work in the insurance industry. Over the past two decades, she has gained in-depth knowledge of state-specific insurance laws and how insurance fits into every person’s life, from budgets to coverage levels. She specializes in autonomous technology, real estate, home security, consumer analyses, investing, di...
Melanie Musson
Managing Editor
Aleksandra J. Churlinov holds a Bachelor of Arts in English Language and Literature and a Master of Science in Marketing Management. Over the past six years, Aleks has focused on the insurance sector, working on a range of content, including business, auto, and life insurance. In April 2025, she stepped into the role of Managing Editor, where she now leads a team of talented insurance writers. ...
Aleksandra J. Churlinov
Principal Broker
William Lemmon has been a licensed insurance agent for over 12 years. He is the principal broker and owner of Broadway Insurance Services in Los Angeles, CA. He works one-on-one with clients to create personalized plans that minimize risk and maximize savings. Being one of the foremost authorities on Airbnb and home-sharing property insurance, Lemmon offers his clients first-hand guidance on how t...
William Lemmon
Updated September 2026
Amica, Chubb, and Liberty Mutual offer the best home insurance in Utah. Amica offers competitive rates for extended wind and hail protection.
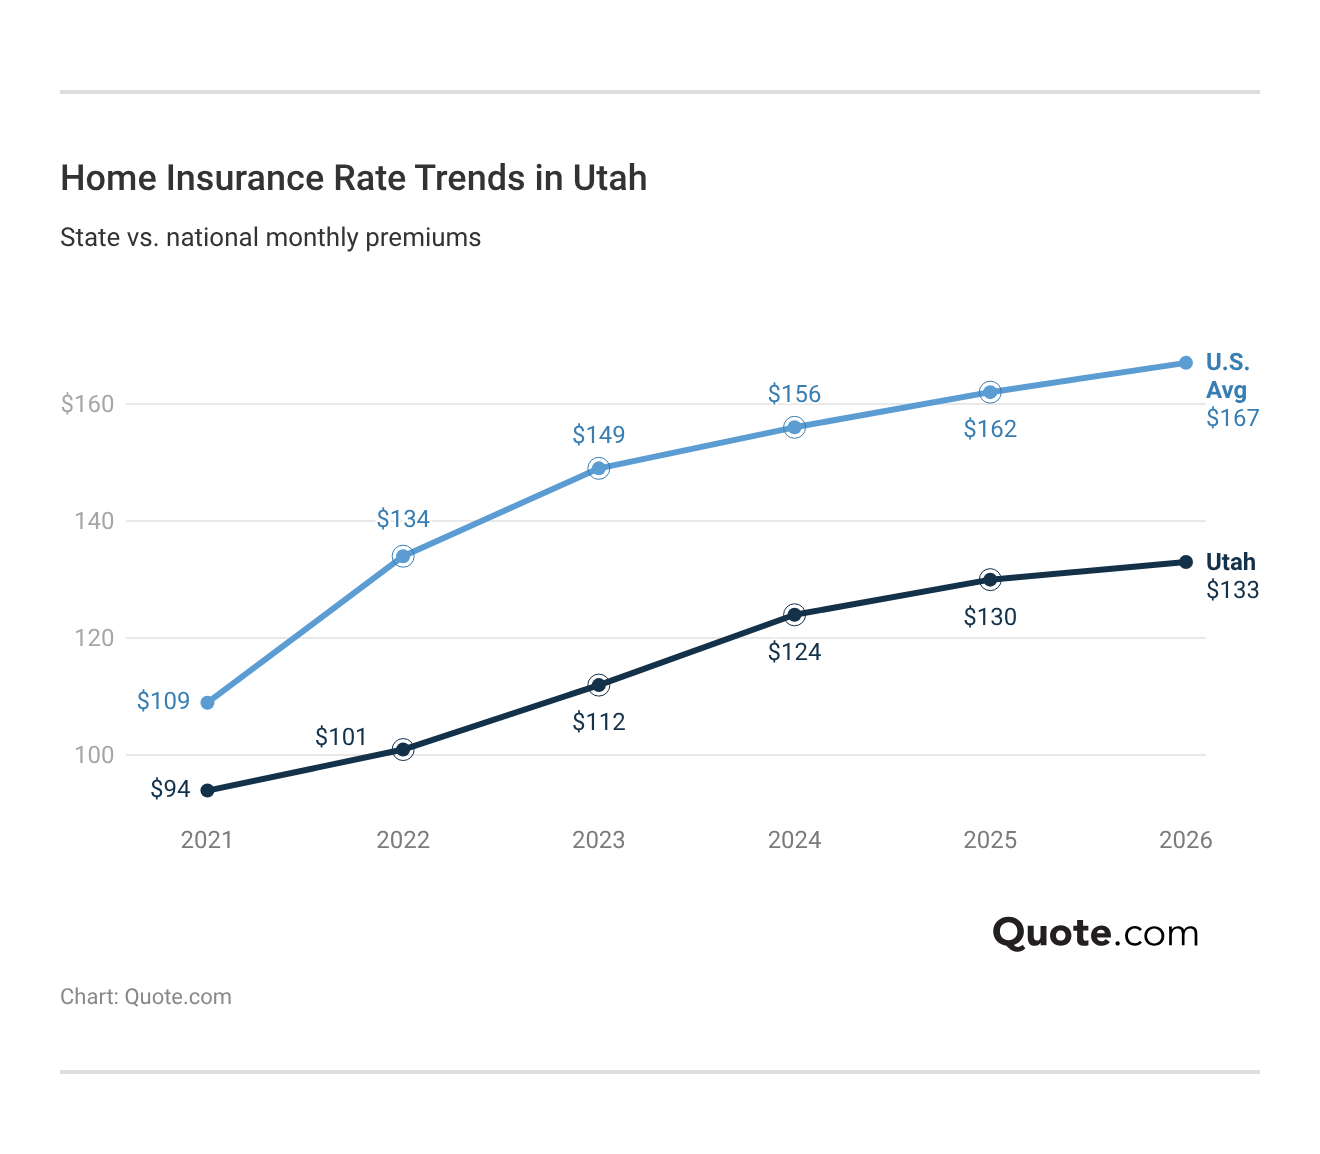
- Utah home insurance averages $130, below the $167 U.S. average
- Amica is the top pick, with affordable premiums and 30% bundle savings
- Higher coverage levels protect Utah homes from winter weather damage
Costs vary based on homeowners insurance coverage, deductible, credit, location, and property risks, which can affect premiums.
Amica and Travelers keep rates affordable across all policy levels, and Chubb offers competitive rates for high-value homes.
Top 10 Companies: Best Home Insurance in Utah| Company | Rank | Claims Satisfaction | Complaints | Best for |
|---|---|---|---|---|
 | #1 | 773 / 1,000 | Low | Policy Value |
 | #2 | 744 / 1,000 | Low | Luxury Homes |
 | #3 | 722 / 1,000 | Mid | Policy Discounts |
 | #4 | 720 / 1,000 | High | Roof Coverage |
 | #5 | 700 / 1,000 | Low | Green Homes |
 | #6 | 700 / 1,000 | Mid | Bundle Savings |
 | #7 | 691 / 1,000 | Mid | Custom Policies |
 | #8 | 690 / 1,000 | Mid | Local Agents |
 | #9 | 681 / 1,000 | Low | Sewer Coverage |
 | #10 | 672 / 1,000 | Low | Digital Tools |
Liberty Mutual costs more, but Utah homeowners can lower costs with useful discounts, policy bundles, and a higher deductible.
Review coverage, discounts, and policy limits to find the right protection for your home. Use our home insurance comparison tool to check reputable insurers, coverage options, and prices.
Compare Utah Home Insurance Costs
Home insurance costs usually rise with higher limits because dwelling coverage for homeowners determines how much insurers may pay to repair or rebuild a home.
Amica is one of the most affordable home insurers in Utah, with rates of $101 per month for $200K in dwelling coverage and $174 per month for $500K, plus replacement cost and extra rebuild options.
Utah Home Insurance Monthly Rates by Dwelling Coverage| Company | $200K | $300K | $400K | $500K |
|---|---|---|---|---|
| $104 | $128 | $153 | $179 |
| $105 | $129 | $152 | $176 |
| $101 | $126 | $149 | $174 |
| $223 | $297 | $387 | $466 |
| $157 | $198 | $237 | $276 |
| $102 | $141 | $183 | $226 |
| $194 | $244 | $291 | $338 |
| $137 | $170 | $199 | $228 |
| $108 | $136 | $162 | $188 |
| $96 | $121 | $149 | $178 |
Chubb costs $157 to $276 per month, partly due to broader coverage and higher limits designed for high-value homes.
Liberty Mutual costs $194 to $338 per month. Use our home insurance quote tool to review pricing from lower-cost providers.
Higher dwelling coverage usually means higher premiums. Ask for a rebuild estimate and choose a limit based on the cost to rebuild your home to avoid paying too much or having too little coverage.
Brad Larson Licensed Insurance Agent
Make sure your policy has enough coverage for severe weather risks, including wind and freezing water damage.
High-risk or high-value properties may need additional hazard insurance for risks not covered by a standard policy. Check your limits and exclusions to make sure your home has enough protection.
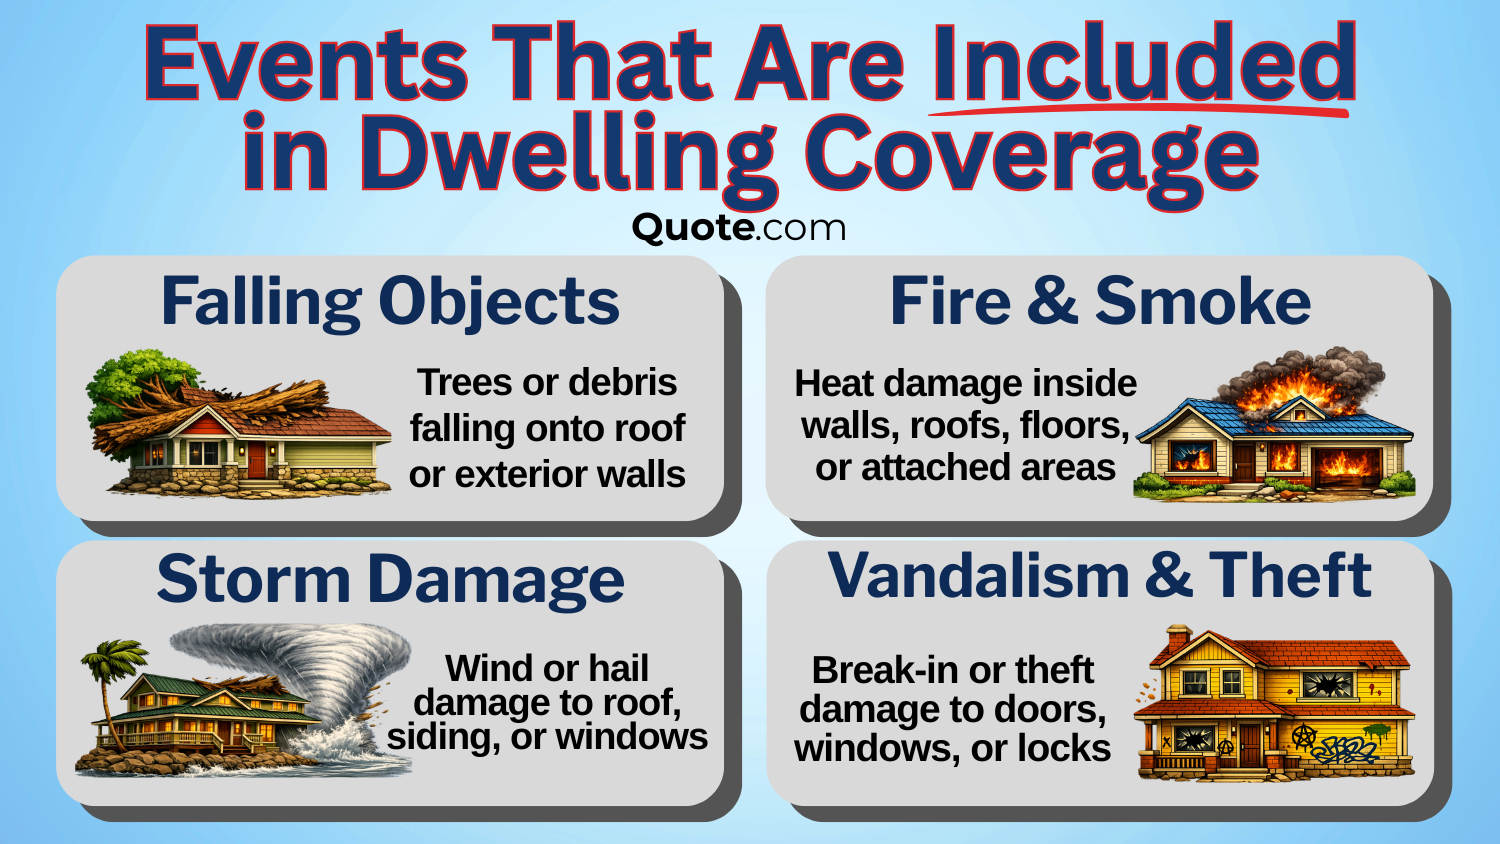
Comparing the average home insurance rates by dwelling coverage amount can help Utah homeowners choose a limit that covers the full cost of a rebuild.
Estimated dwelling coverage, which helps pay to rebuild the home after a covered loss, is about 21% to 22% above home value.
Estimated Coverage, Costs, & Risk Levels in Utah| Home Value | Coverage | Monthly Rate | Rebuild Costs | Risk Level |
|---|---|---|---|---|
| $200K | $242K | $133 | Low | Standard |
| $225K | $272K | $142 | Low | Standard |
| $250K | $304K | $151 | Moderate | Standard |
| $275K | $333K | $160 | Moderate | Elevated |
| $300K | $365K | $169 | Moderate | Elevated |
| $350K | $425K | $188 | High | Elevated |
| $400K | $485K | $206 | High | Substantial |
| $450K | $545K | $225 | High | Substantial |
| $500K | $610K | $243 | Extreme | Substantial |
| $600K | $728K | $281 | Extreme | Substantial |
As home values rise, homeowners may need more coverage to protect their property’s full value. Utah coverage estimates range from $242K for a $200K home to $728K for a $600K home.
Review your policy as your home value changes to make sure your coverage still fits your property and budget. See which policies fit your needs and budget by comparing personalized quotes.
Utah Home Insurance Premiums vs. U.S. Average
The average homeowners insurance cost in Utah is about $130 per month, below the U.S. average of $167 per month.
Utah home insurance premiums continue to rise after costly claims or as insurers face higher repair and rebuild expenses.
Homes in areas prone to major property damage may also cost more to insure. If your property faces wind or winter storm damage, you may see even higher premiums based on local risk.
Wildfire risk can also affect homeowners in exposed parts of Utah because a single fire can cause severe damage. Learn More: How to File a Wildfire Home Insurance Claim
How Deductibles Affect Utah Home Insurance Costs
Premiums tend to drop as homeowners insurance deductibles in Utah rise because homeowners pay more toward a claim.
A $500 deductible has the highest monthly premium at $144, but it offers the largest claim payout and may work well for homeowners who file claims more often.
Home Insurance Deductibles in Utah: Premium Impact| Category | $500 | $1K | $2K | $5K |
|---|---|---|---|---|
| Best Use | File Often | Less Often | Low Cost | Rare Claims |
| Claim Payout | Largest | High | Moderate | Smallest |
| Claim Rate | Highest | Moderate | Low | Lowest |
| Monthly Rate | $144 | $133 | $120 | $106 |
| Rate Stability | Lowest | Moderate | High | Highest |
Raising the deductible to $1K lowers the premium to $133 per month, while a $2K deductible brings it down to $120 and offers a middle ground between monthly premiums and out-of-pocket expenses.
A $5K deductible offers the lowest premium at $106 per month, but higher insurance deductibles mean homeowners pay more toward a covered loss before insurance pays the rest.
Amica has some of the lowest premiums among the top three companies, from $110 per month with a $500 deductible to $81 with a $5K deductible.
Amica’s premium drops by $29 per month when the deductible rises from $500 to $5K, which can help homeowners save on monthly insurance costs.
Utah Home Insurance Monthly Rates by Deductible| Company | $500 | $1K | $2K | $5K |
|---|---|---|---|---|
| $113 | $104 | $94 | $83 |
| $116 | $105 | $95 | $84 |
| $110 | $101 | $92 | $81 |
| $241 | $223 | $202 | $178 |
| $169 | $157 | $143 | $126 |
| $112 | $102 | $93 | $82 |
| $211 | $194 | $176 | $155 |
| $149 | $137 | $124 | $110 |
| $118 | $108 | $98 | $87 |
| $104 | $96 | $87 | $77 |
Chubb costs $126 to $169 per month, with higher premiums for broader high-value home coverage, compared to Travelers, which offers the lowest premiums, from $104 per month with a $500 deductible to $77 with a $5K deductible.
If your premium feels high, shop affordable insurance rates from top companies and review your options.
Why Utah Home Insurance Rates Vary by Location
Utah home insurance premiums range from $112 to $280 per month statewide, with a $196 midpoint.
Amica falls below that benchmark in the article’s property-risk data, while Chubb reaches about $195 and Liberty Mutual exceeds $200.
Location can affect home insurance rates. Utah homes with greater wildfire risk, severe weather, or limited contractor access may have higher premiums.
Your ZIP code can affect your home insurance premium. Get local quotes from top home insurance companies to compare prices in your area.
How Property Risks Influence Utah Home Insurance Rates
Risk may vary depending on where in Utah an insured property is located. Water damage accounts for 32% of claims. Wind and hail account for another 21%.
Homes along the Wasatch Front may face higher premiums due to exposure to storms that can damage roofs and home exteriors.
5 Most Common Home Insurance Risks in Utah| Risk | Claims | Payout | Cost | Area |
|---|---|---|---|---|
| #1 Water Damage | 32% | $12K | Moderate | Northern |
| #2 Wind & Hail | 21% | $14K | Moderate | Wasatch Front |
| #3 Wildfire | 11% | $32K | High | Foothills |
| #4 Theft | 8% | $3K | Low | Urban Areas |
| #5 Flooding | 7% | $8K | Low | River Valleys |
Wildfires are less common but have the highest average payout at $32K due to the risk of severe property damage.
Theft generally leads to modest-to-medium losses, whilst properties in and near river valleys face a much higher flood risk and may need separate flood insurance.
Costly property risks can raise premiums, but updated plumbing and protective features may help reduce them.
Dani Best Licensed Insurance Agent
Amica has the lowest premiums, from $112 to $130 per month, along with reliable claims support and customer service.
Chubb offers the best insurance for high-risk homes, from $169 to $195 a month. Liberty Mutual costs more, with premiums from $211 to $257, but its discounts can help lower costs.
Utah Home Insurance Monthly Rates by Risk Factor| Company | Water Damage | Wildfire | Wind & Hail | Winter Storm |
|---|---|---|---|---|
| $116 | $134 | $118 | $113 |
| $118 | $139 | $121 | $116 |
| $113 | $130 | $115 | $112 |
| $247 | $282 | $250 | $242 |
| $173 | $195 | $176 | $169 |
| $115 | $137 | $118 | $113 |
| $214 | $257 | $222 | $211 |
| $151 | $181 | $156 | $149 |
| $119 | $143 | $123 | $118 |
| $108 | $126 | $109 | $104 |
Chubb and Liberty Mutual can still be good choices if you want broader protection and added policy options, even at a higher price.
Standard policies don’t always cover the risks listed in the table. Utah homeowners with high-risk properties who need optional add-ons to customize protection benefit most from higher-priced providers like Liberty Mutual.
Paying a little more for strong claims service and natural-disaster coverage options in Utah may be worthwhile for high-risk homeowners who need extra protection after serious property damage.
Compare home insurance prices from several providers to see if your premium is competitive.
How Credit Affects Home Insurance Premiums in Utah
Credit can affect your home insurance premium in Utah. Some insurers use credit-based insurance scores to estimate how likely a homeowner is to file a claim.
A stronger credit profile can help homeowners qualify for lower premiums with some insurers. Travelers offers the cheapest home insurance in Utah at $96 to $205 per month, followed by Amica at $101 to $215 per month, based on credit.
Utah Home Insurance Monthly Rates by Credit Score| Company | Excellent (800+) | Good (670-799) | Fair (580-669) | Poor (<580) |
|---|---|---|---|---|
| $104 | $125 | $168 | $229 |
| $105 | $127 | $174 | $241 |
| $101 | $119 | $159 | $215 |
| $223 | $257 | $338 | $456 |
| $157 | $181 | $234 | $309 |
| $102 | $124 | $169 | $235 |
| $194 | $233 | $315 | $438 |
| $137 | $162 | $216 | $294 |
| $108 | $126 | $165 | $221 |
| $96 | $113 | $151 | $205 |
Chubb ranges from $157 to $309 per month, partly due to higher coverage limits in Utah and broader protection for high-value homes.
Liberty Mutual has the highest premiums among the top three, from $194 to $438 per month, as credit, property value, coverage, and other risk factors can affect its prices.
Use our quote comparison tool to see what Utah home insurance coverage may cost in your area.
Free Home Insurance Comparison
Compare Quotes From Top Companies and Save
Types of Homeowners Insurance Policies in Utah
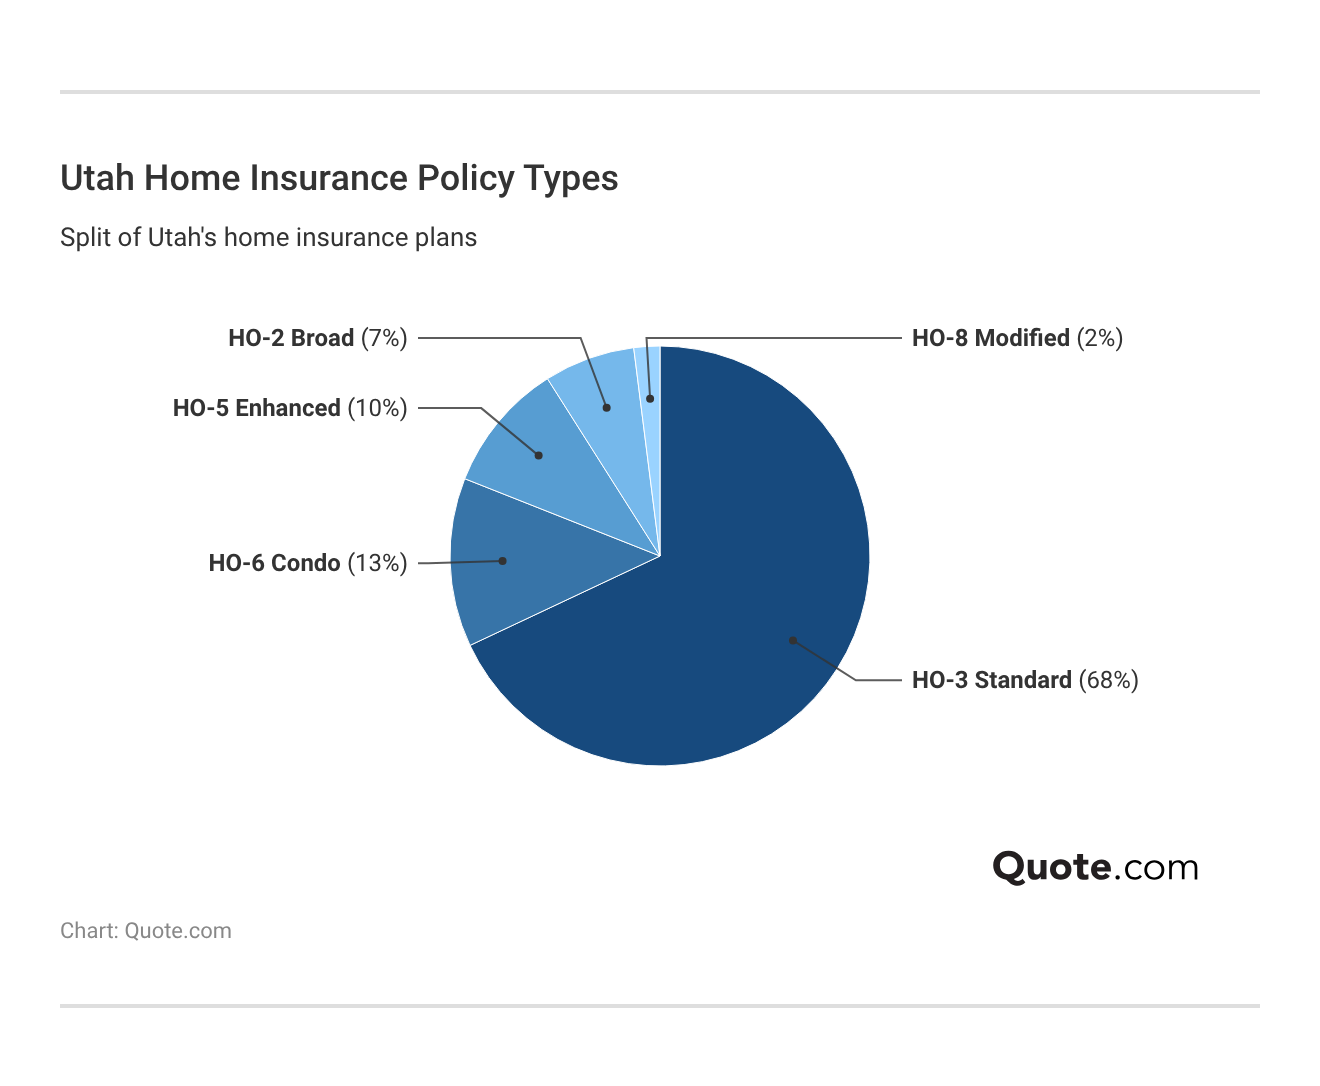
HO-3 Standard policies account for 68% of Utah plans, making them one of the most common types of home insurance for broad property and liability protection.
Other policy types are less common because they fit more specific homes or coverage needs.
- HO-2 Broad: Covers the home and personal property against specific risks listed in the policy.
- HO-3 Standard: Covers the home, personal property, liability, and extra living costs after a covered loss.
- HO-5 Enhanced: Offers broader home and personal property coverage with fewer restrictions than an HO-3 policy.
- HO-6 Condo: Covers personal property, liability, interior improvements, and condo parts not covered by the association.
- HO-8 Modified: Generally designed for older homes where standard replacement cost coverage may not be practical.
Some apply to condos or older homes, while other Utah homeowners insurance options provide different levels of protection based on a homeowner’s coverage needs.
Even broad home insurance policies have limits and exclusions. Risks such as floods and earthquakes may require separate coverage or an add-on.
These gaps make it important to review which property risks insurers cover before you choose a policy.
The best home insurance companies in Utah offer several ways to protect against property risks, though earthquake and flood coverage may require separate protection.
Home Insurance Coverage Options in Utah| Company | Earthquake | Flood | Wildfire | Wind & Hail |
|---|---|---|---|---|
| ➕Add-On | ✅Both | ⚠️Limited | ➕Add-On |
| ➕Add-On | ✅Both | ✅ | ✅ |
| ➕Add-On | ⚠️NFIP | ✅ | ✅ |
| ⚠️Limited | ✅Both | ✅ | ➕Add-On |
| ➕Add-On | ⚠️Private | ✅ | ✅ |
| ➕Add-On | ⚠️NFIP | ✅ | ✅ |
| ⚠️Limited | ⚠️NFIP | ⚠️Limited | ✅ |
| ➕Add-On | ⚠️Private | ✅ | ✅ |
| ➕Add-On | ⚠️NFIP | ✅ | ✅ |
| ⚠️Limited | ⚠️Private | ✅ | ✅ |
American Family, Amica, and Chubb offer broad coverage options that address common Utah home insurance problems and property risks.
Coverage matters, but claims support is also important when homeowners need to repair damage or adjust a policy after a loss.
Liberty Mutual may have more policy restrictions, but its strong customer satisfaction can help homeowners who need support with claims or policy changes.
Clear claim steps can also help homeowners know what to expect after property damage and avoid delays during the claims process.
Understanding Coverage Restrictions on Utah Homeowners Insurance
Utah home insurance limits will also differ by the age of your home, state of the roof, value of property, and exposure to winter damage. Read More: How Roof Inspections Affect Home Insurance
Amica and Chubb have 25-year roof limits, which may offer more flexibility for homeowners with older roofs than insurers with 15- or 20-year limits.
Utah Home Insurance Restrictions by Company| Company | Inspection? | Roof Limit | Sewer | Winter Freeze |
|---|---|---|---|---|
| ⚠️by Age | 20 Yrs | ⚠️ by Condition | ⚠️Capped |
| ⚠️by Review | 20 Yrs | ➕Add-On | ✅ |
| ⚠️by Review | 25 Yrs | ✅ | ⚠️by Review |
| ⚠️Exterior | 20 Yrs | ✅ | ⚠️by Condition |
| ⚠️by Value | 25 Yrs | ✅ | ⚠️Limited |
| ⚠️by Age | 15 Yrs | ✅ | ⚠️by Condition |
| ⚠️by Age | 15 Yrs | ⚠️ by Condition | ⚠️Capped |
| ⚠️by Review | 20 Yrs | ✅ | ⚠️by Review |
| ⚠️by Age | 20 Yrs | ⚠️ by Condition | ⚠️Capped |
| ⚠️by Review | 20 Yrs | ⚠️ by Condition | ⚠️by Review |
Liberty Mutual has stricter coverage rules, which may limit options for Utah homeowners with older properties or greater winter weather risks.
Compare coverage options from top home insurance companies in Utah to find a policy that fits your home and coverage needs.
How to Save on Home Insurance in Utah
Even though Utah home insurance costs less than the national average, homeowners can still save.
Simple changes to your policy, home, or payment method can help lower your premium. Start with these five ways to cut costs without reducing important coverage.
- Compare Insurers Regularly: Home insurance prices vary by company and coverage, so compare home insurance rates and ratings in Utah to find better value.
- Improve the Roof: Replacing an older roof or using impact-resistant roofing materials may help reduce costs with some insurers.
- Pay Premium in Full: Some insurers offer savings when homeowners pay the annual premium at once instead of monthly.
- Raise Deductible: Home insurance premiums by deductible in Utah may decrease with a higher deductible, but homeowners will pay more out of pocket after a claim.
- Use Automatic Payments: Insurers may offer a small discount for automatic electronic payments.
Utah homeowners can find some of the best home insurance discounts through policy bundles, claim-free rewards, newer-home savings, and security system credits.
These savings can reduce premiums without requiring homeowners to lower their coverage limits or increase their deductible.

American Family offers the highest bundling discount at 40%, followed by Amica at 30% and State Farm at 26%.
Allstate, American Family, Amica, and Travelers offer the highest no-claims discount at 12%, while Allstate, Chubb, and Travelers offer up to 9% for newer homes.
Top Home Insurance Discounts in Utah| Company | Bundling | New Home | No Claims | Security |
|---|---|---|---|---|
| 20% | 9% | 12% | 5% |
| 40% | 8% | 12% | 6% |
| 30% | 8% | 12% | 5% |
| 14% | 8% | 10% | 4% |
| 10% | 9% | 11% | 6% |
| 20% | 7% | 10% | 5% |
| 12% | 6% | 9% | 4% |
| 15% | 8% | 11% | 6% |
| 26% | 7% | 10% | 5% |
| 16% | 9% | 12% | 6% |
American Family, Chubb, Nationwide, and Travelers provide the highest security discount at 6%.
See which discounts and premiums are available to you when you compare home insurance quotes from top companies.
How Home and Auto Bundles Help Lower Insurance Costs in UT
The best auto and home insurance bundles reward customers who insure both their home and car with the same company.
To qualify, both policies usually need to be active with the insurer and meet its bundle requirements.
10 Best Home & Auto Insurance Bundle Discounts in Utah| Company | Rank | Discount | Savings | Bundle Rules |
|---|---|---|---|---|
| #1 | 40% | $1,020 | Auto Customers |
| #2 | 26% | $780 | Current Policy |
 | #3 | 25% | $725 | Bundle Quote |
| #4 | 20% | $590 | Qualifying Policy |
| #5 | 20% | $575 | Online Bundle |
| #6 | 16% | $480 | Qualifying Home |
| #7 | 15% | $450 | Prior Policy |
| #8 | 14% | $430 | Local Agent |
 | #9 | 13% | $410 | Members Only |
| #10 | 12% | $390 | Shared Address |
Compared with many competitors, the 12% bundle discount at Liberty Mutual is on the small side, so customers save an estimated $390.
However, it offers flexible policy options, optional add-ons, and home insurance discounts in Utah that can help homeowners adjust coverage to fit their needs.
American Family offers the largest bundle discount at 40%, with estimated savings of $1,020, plus other policy savings for Utah homeowners.
State Farm combines a 26% bundle discount and $780 in estimated savings with access to local agents for policy and claims support. Start comparing insurance quotes to see prices based on your needs.
Top Home Insurance Providers in Utah
State Farm is Utah’s largest home insurer, with a broad agent network and strong local support. Homeowners can get in-person help with coverage, policy questions, and claims.
Amica, Chubb, and American Family rank higher on our list because they stand out in specific areas. Compare Now: American Family vs. Travelers Insurance Review
10 Largest Home Insurance Companies in Utah| Company | Market Share | Policy Count | Premiums Written | Financial Rating |
|---|---|---|---|---|
| 15.4% | 107K | $193.6M | A+ |
| 11.2% | 77K | $139.9M | A |
| 9.7% | 67K | $121.7M | A+ |
| 8.3% | 57K | $103.4M | A |
| 7.7% | 53K | $96.6M | A |
 | 7.1% | 49K | $88.9M | A++ |
 | 6.6% | 46K | $83.1M | A- |
| 5.9% | 41K | $74.4M | A+ |
| 5.0% | 34K | $62.4M | A++ |
| 2.9% | 20K | $36.8M | A+ |
Our top picks for homeowners insurance in Utah include Amica for strong overall policy value, Chubb for added protection for high-value homes, and American Family for some of the largest discounts.
When choosing a Utah home insurance company, consider coverage, premiums, discounts, claims service, and financial strength.
#1 – Amica: Top Pick Overall
Pros
- Competitive Rates: Utah premiums start at $81 per month for a $5K deductible with maximum coverage. Explore rates in our guide: Amica Insurance Review
- Low-Cost High-Risk Policies: The cost for water, wind, hail, fire, and other property risks in a Utah policy is estimated between $112 and $130 per month.
- Big Bundle Discount: Among the homeowners insurance discounts in Utah, Amica offers up to 30% off when you bundle your home and auto policies.
Cons
- Discount Requirements: Utah homeowners must meet Amica’s eligibility rules to qualify for its available policy discounts
- Older Roof Review: Amica may review Utah homes with older roofs before it approves coverage.
#2 – Chubb: Best for Luxury Homes
Pros
- Luxury Home Coverage: Chubb offers the best home insurance for high-value properties, with expanded protection and higher limits.
- Rebuild Coverage Extensions: Extended replacement cost can pay above the policy limit when a covered loss costs more to repair or rebuild.
- Flexible Settlements: After a covered total loss, eligible policyholders may choose a cash settlement instead of rebuilding the home.
Cons
- Freeze Coverage Limits: Chubb’s winter freeze protection is limited, so homeowners should review policy terms before they buy coverage.
- Earthquake Add-On: Earthquake damage usually requires separate coverage, which can increase the cost of a Utah policy.
#3 – Liberty Mutual: Best for Policy Discounts
Pros
- Policy Discounts: Utah homeowners can save in several ways, including multi-policy, preferred payment, new roof, and new or renovated home discounts.
- Flexible Winter Coverage: Liberty Mutual offers optional coverage you can tailor to your property and coverage needs, including freeze, wind, and hail protection.
- Digital Policy Tools: Homeowners can manage policies and payments either online or through Liberty Mutual’s mobile tools. Discover More: Liberty Mutual Insurance Review
Cons
- Expensive for High-Risk Properties: Wildfire exposure raises Liberty Mutual’s Utah premium to $257 per month, versus $211 for winter storm risk.
- Discount Eligibility: Some discounts aren’t available in all parts of Utah, and others depend on how you buy your policy and the coverage you add.
#4 – Nationwide: Best for Roof Protection
Pros
- Roof Protection: Homeowners can add roof replacement coverage at an affordable rate for extra protection after a covered loss.
- Bundle Savings: Utah customers can save up to 20% when they bundle Nationwide home and auto insurance.
- Coverage Options: Our detailed review of Nationwide says homeowners can choose optional protection for valuable belongings, water backup, and other property needs.
Cons
- Higher Premiums: Nationwide isn’t the most expensive home insurance company in Utah, but it charges higher rates than other companies based on credit and deductible.
- Property Reviews Required: Homes in Utah have specific property risks, so Nationwide will review them before approving coverage.
#5 – Travelers: Best for Green Homes
Pros
- Green Home Savings: Utah homeowners with a LEED-certified home may qualify for up to a 5% Travelers green home discount. What to Know: Travelers Review
- Cheapest Premiums: Travelers offers some of the best home insurance rates in Utah, starting at $77 per month with a $5K deductible.
- Access to Local Agents: Travelers has independent agents throughout Utah who can help homeowners review coverage needs and policy options.
Cons
- Costs Rise for Older Homes: Older Utah homes may face higher premiums due to repair and replacement costs.
- Eligibility Varies: Discounts may be limited by state and each homeowner’s eligibility, so not all advertised discounts are available to Utah homeowners.
#6 – American Family: Best for Bundle Savings
Pros
- Biggest Bundle Discount: Utah homeowners can save up to 40% with a home and auto bundle, the highest bundle discount in your data.
- Claim-Free Savings: Utah homeowners with no claims can qualify for a 12% discount, a benefit highlighted in our American Family insurance review.
- Discounts for Security Systems: Qualifying Utah homeowners can receive a 6% security discount.
Cons
- Wildfire Costs: Utah homeowners with wildfire exposure may pay about $139 per month, higher than other insurers listed.
- Older Roofs Not Eligible: American Family has a 20-year roof limit in your Utah data, which may affect eligibility for homes with older roofs.
#7 – Farmers: Best for Custom Policies
Pros
- Custom Policy Add-Ons: Farmers offers options such as Emergency Mortgage Assistance, Declining Deductibles, and Claim Forgiveness for tailored coverage.
- Affordable Wildfire Coverage: Farmers includes wildfire coverage in Utah costing $137 per month.
- Competitive Hail Protection: Wind and hail coverage is available, with a Utah premium of $118 per month. More Details Here: Farmers Insurance Review
Cons
- Smaller New-Home Deal: Farmers offers a 7% new-home discount in Utah, below the 9% available from some competitors.
- Rate Increase Based on Credit Score: Utah premiums can reach $235 per month for poor credit, compared with $102 for excellent credit.
#8 – State Farm: Best for Local Agents
Pros
- Local Agent Access: Utah homeowners can work with State Farm agents for quotes, policy questions, and coverage help.
- Strong Financials: As per our State Farm insurance review, the company has an A+ financial rating, which supports its ability to meet policy obligations.
- Utah Market Leader: State Farm holds 15.4% of Utah’s home insurance market, giving it broad experience with local homeowners and property claims.
Cons
- Restrictions on High-Risk Coverage: Sewer backup requires an add-on, while frozen-pipe claims may be denied if the home is not properly heated.
- Below-Average Claims Satisfaction: State Farm scored 690 in J.D. Power’s 2026 U.S. Property Claims Satisfaction Study, below the 702 study average.
#9 – Auto-Owners: Best for Sewer Coverage
Pros
- Sewer Coverage: Utah policies include sewer coverage, which can add protection against costly water-related losses.
- Inland Flood Coverage: Auto-Owners offers an inland flood endorsement that adds protection for eligible low-risk homes. Find Out More: Auto-Owners Insurance Review
- Higher Policy Limits: Auto-Owners can cover homes with larger dwelling limits, with premiums from $223 per month for $200K to $466 for $500K in coverage.
Cons
- Smaller Bundle Discount: Its 14% bundle discount trails several Utah competitors, including American Family at 40% and State Farm at 26%.
- Higher Wildfire Costs: Utah homeowners with wildfire exposure may pay about $282 per month, the highest Auto-Owners premium among the listed risk factors.
#10 – Allstate: Best for Digital Tools
Pros
- Digital Access: Allstate gives Utah homeowners online and mobile tools to manage policies, make payments, access documents, and file or track claims.
- No-Claims Savings: Utah homeowners may qualify for a 12% no-claims discount, one of the highest discounts in the data provided.
- New Home Savings: According to our Allstate insurance review, Utah homeowners can get up to a 9% new-home discount, which can help lower premiums for newer properties.
Cons
- Policy Limitations: Allstate offers winter storm protection only as an add-on, and it caps policy payouts for winter freeze damage.
- Lower Claims Satisfaction Score: Allstate has the lowest claims satisfaction score among the 10 insurers included in our Utah home insurance ranking.
Free Home Insurance Comparison
Compare Quotes From Top Companies and Save
Choose the Best Home Insurance in Utah
The best home insurance in Utah should match your home value, property risks, and budget.
Compare the same dwelling coverage limits and deductibles across insurers so you can judge premiums fairly.
Check endorsements, discounts, roof limits, and policy exclusions from the best home insurance companies before you choose a plan.
Low premiums may not always mean better value. Check claims service and policy terms. For example, choose an insurer with reliable claims support.
Jeff Root Licensed Insurance Agent
Review replacement cost terms to see how much your policy may pay if you need to rebuild after a covered loss.
Also check whether coverage limits keep pace with local labor and material costs, which can affect how much protection you need. A lower premium may save money, but make sure the policy still protects your home.
Amica provides affordable premiums and broad coverage, but some policy features and winter freeze protection may require review.
Chubb may charge more than Amica, but its higher thresholds and extra protection make it an excellent choice for high-value homes.
Liberty Mutual’s policy has a higher premium and lower roof limits, but its discounts and optional add-ons can help you tailor the best coverage.
Enter your ZIP code to see lower-cost home insurance premiums available in your neighborhood.
Frequently Asked Questions
How much does homeowners insurance cost in Utah?
The average cost of homeowners insurance in Utah is about $130 per month, compared to the national average of $167 per month. Actual premiums depend on your state, dwelling coverage, deductible, and credit and property risk.
Is homeowners insurance required in Utah?
Utah law does not require homeowners insurance, but most mortgage lenders will require it. Coverage such as personal liability insurance can also help protect homeowners from costly claims and property-related risks, even without a mortgage.
What factors affect homeowners insurance costs in Utah?
Utah home insurance prices by coverage levels may vary based on coverage limits, deductibles, location, and credit. Homes with greater wildfire or extreme weather risk may also face higher premiums. Compare home insurance quotes in Utah from multiple companies to see what impacts rates in your area.
How can homeowners save money on home insurance in Utah?
You can save by comparing home insurance quotes, choosing a higher deductible, and using discounts. Bundling policies with the best home and auto insurance companies in Utah, maintaining a newer roof, and paying premiums in full may also lower costs.
How can homeowners compare insurance in Utah?
Use the best insurance comparison sites to compare Utah home insurance rates, coverage, deductibles, discounts, and policy restrictions, including protection for wildfires, wind, hail, and winter storms.
Does home insurance cover fire damage in Utah?
Yes, fire is a covered peril in Utah for additional damage to the structure of the home and personal property caused by a covered fire.
Does homeowners insurance cover flooding in Utah?
Homeowners in Utah typically need flood coverage from the NFIP or a private insurer, since standard homeowners insurance does not cover flooding. Check homeowners insurance premiums to see your options.
Is earthquake insurance available to homeowners in Utah?
Yes, Utah homeowners can get cheap earthquake insurance, usually as an add-on or separate policy, since standard home insurance doesn’t cover earthquake damage.
What coverage do I need if wildfire risk is high?
If wildfire risk is high, choose home insurance that covers wildfire damage and has enough dwelling coverage to rebuild your home. Also check coverage for personal property and extra living expenses if you need to leave your home after a covered loss.
Learn More: Does home insurance cover wildfires?
Is it hard to get homeowners insurance in Utah?
Homeowners insurance is generally easy to get in Utah, but some homes may face more restrictions because of an older roof, property condition, or higher wildfire risk. Homeowners who cannot find suitable coverage can compare the best homeowners insurance companies in Utah or work with an independent insurance agent.
Does State Farm offer homeowners insurance in Utah?
What should you do if you’re denied home insurance coverage in Utah?
Related Articles
-
Jun 2026

Cheap Earthquake Insurance in 2026 (Find the Best Rates)
-
May 2026
Home Insurance Premiums: How They Work & Cost Factors (2026)
-
Jun 2026
10 Cheapest Home Insurance Companies in 2026
-
Jul 2026
Public Adjuster: Role, Benefits, & Claim Support (2026)
-
Aug 2026
Best Home Insurance in Alabama for 2026
-
Oct 2025
Best Home Insurance for High-Value Properties in 2026
Get a FREE Quote in Minutes
Insurance rates change constantly — we help you stay ahead by making it easy to compare top options and save.