Best Home Insurance in Connecticut for 2026
The best home insurance in Connecticut comes from Amica, The Hartford, and Chubb. CT home insurance rates start at $88 per month, and you can find lower rates here. The top Connecticut home insurance companies offer excellent customer service, valuable coverage, and customizable policies for common local risks.
Read more
Table of Contents
Table of Contents
Insurance Copywriter
Malory Will has an M.A. in English from Arizona State University. She has over four years of experience in writing for the insurance industry. With a background in health, auto, life, and homeowners insurance, Malory is passionate about making complex insurance topics clear and approachable. Her goal is to help readers make informed decisions with confidence.
Malory Will
Managing Editor
Daniel S. Young began his professional career as chief editor of The Chanticleer, a Jacksonville State University newspaper. He also contributed to The Anniston Star, a local newspaper in Alabama. Daniel holds a BA in Communication and is pursuing an MA in Journalism & Media Studies at the University of Alabama. With a strong desire to help others protect their investments, Daniel has writt...
Daniel S. Young
Licensed Insurance Agent
Heidi works with top-rated life insurance carriers to bring her clients the highest quality protection at the most competitive prices. She founded NoPhysicalTermLife.com, specializing in life insurance that doesn’t require a medical exam. Heidi is a regular contributor to several insurance websites, including FinanceBuzz.com, Insurist.com, and Forbes. As a parent herself, she understands the...
Heidi Mertlich
Updated September 2026
Amica, The Hartford, and Chubb have the best home insurance in Connecticut. Amica home insurance rates start at $116 per month.
- Connecticut home insurance rates are similar to the national average
- Coastal Connecticut home premiums start at $137 per month
- Homeowners in Connecticut should consider buying flood insurance
Connecticut homeowners have plenty of insurance companies to choose from, but you should consider coverage options, discounts, customer service, and financial strength before you buy.
Also consider how well an insurer addresses risks common in Connecticut, including coastal storms, severe winter weather, and flooding. Amica and The Hartford are the best homeowners insurance companies with the highest claim satisfaction ratings in the state.
Top 10 Companies: Best Home Insurance in Connecticut| Company | Rank | Claims Satisfaction | Complaints | Best for |
|---|---|---|---|---|
 | #1 | 773 / 1,000 | Low | Customer Service |
 | #2 | 756 / 1,000 | Low | Claims Service |
 | #3 | 744 / 1,000 | Low | Luxury Homes |
 | #4 | 722 / 1,000 | Mid | Flexible Options |
 | #5 | 720 / 1,000 | Low | Policy Add-Ons |
 | #6 | 704 / 1,000 | Mid | Digital Tools |
 | #7 | 700 / 1,000 | Low | Historic Homes |
 | #8 | 691 / 1,000 | Mid | Policy Perks |
 | #9 | 690 / 1,000 | Mid | Policy Bundling |
 | #10 | 672 / 1,000 | Mid | Discounts |
Keep reading to learn which companies offer the best Connecticut home insurance for your needs. Finding the right provider takes a little research, but the savings are definitely worth it.
When you’re ready to compare personalized quotes, enter your ZIP code into our free tool today.
Comparing Connecticut Home Insurance Rates
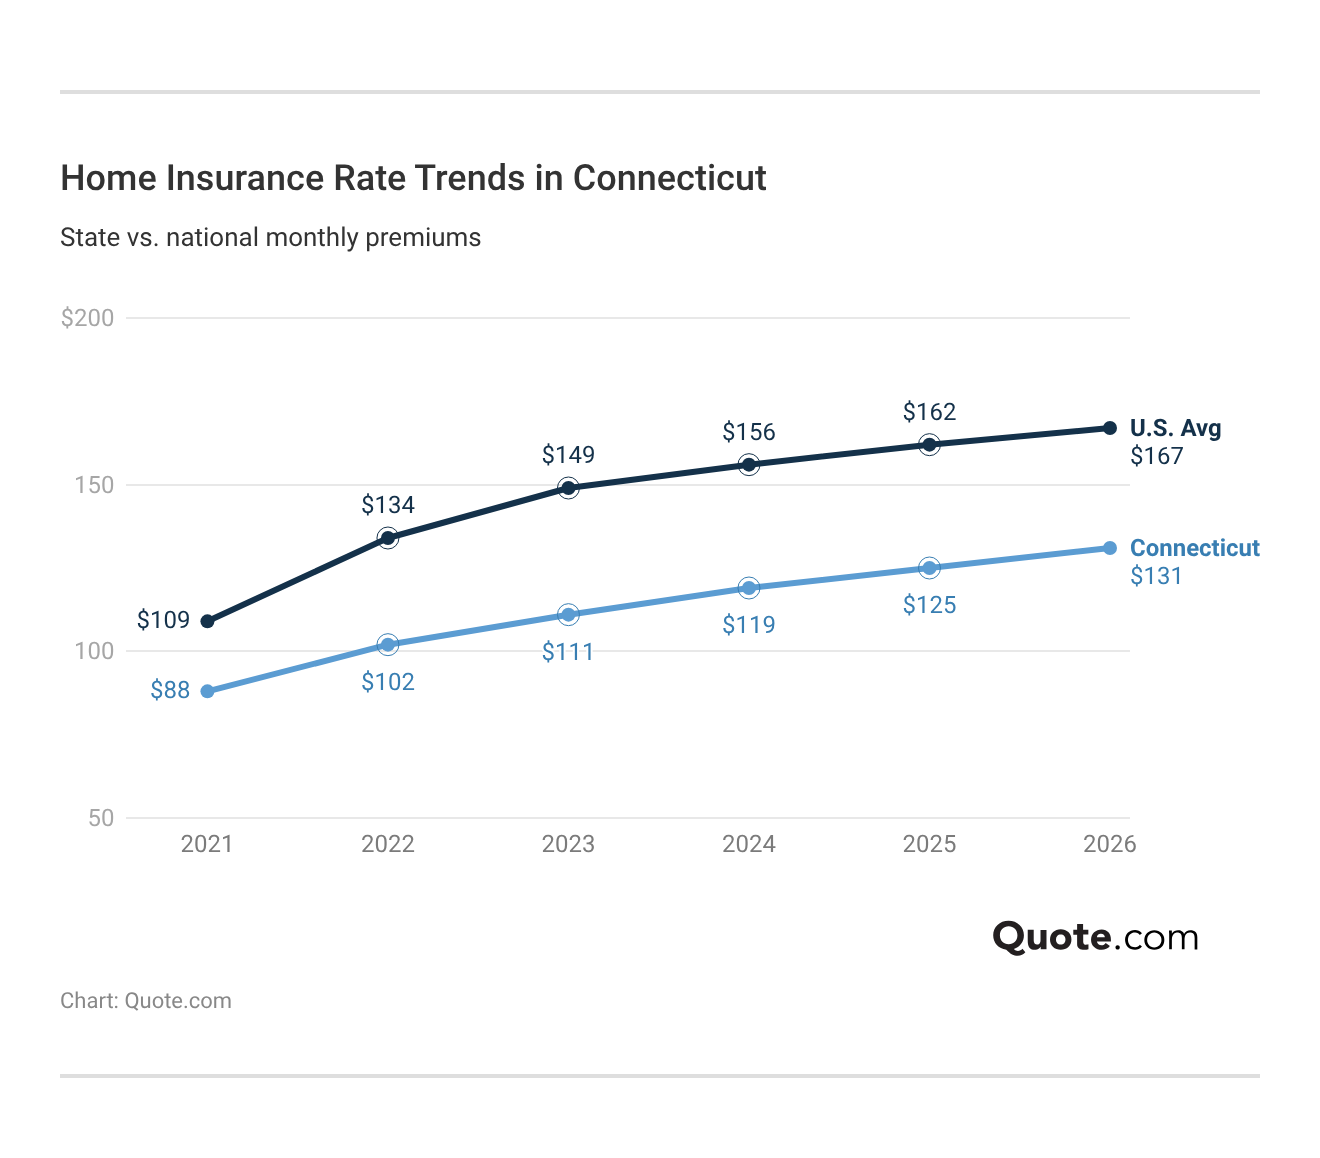
Connecticut home insurance costs are pretty similar to the national average, although rates have increased in recent years.
Even the best home insurance in CT rose by about 38% between 2021 and 2025, with the largest annual increase in 2024.
Connecticut homeowners can pay as little as $88 per month if they shop with Travelers and choose the highest deductible available.
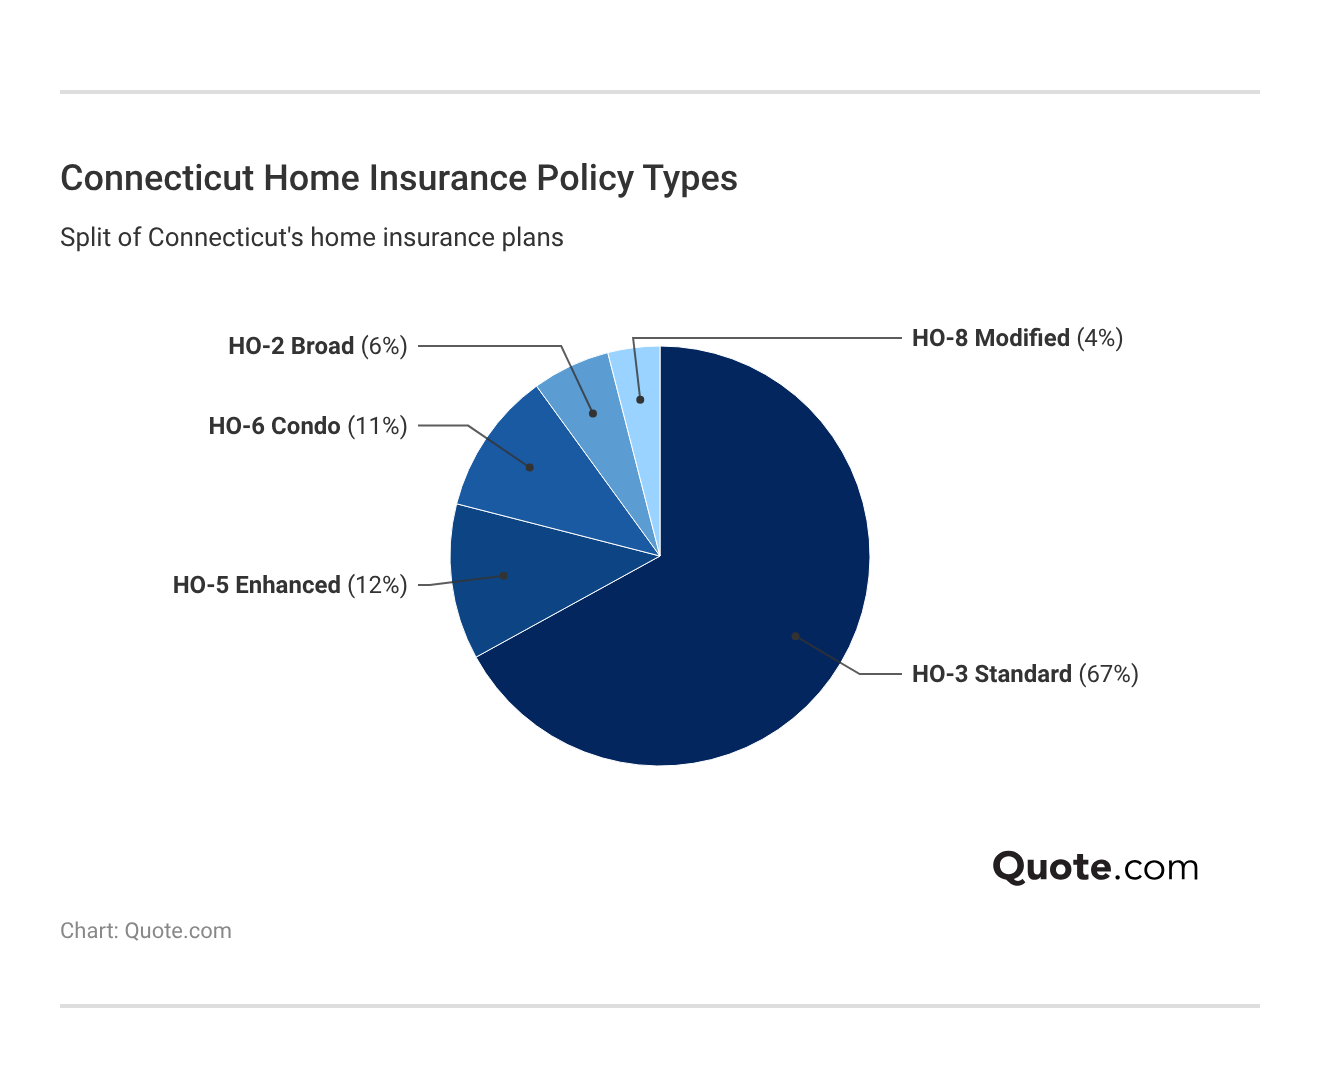
Depending on the type of coverage you purchase, your monthly premium could be relatively low. There are several types of home policies, but the most common is an HO-3.
HO-2 and HO-8 policies are less common but more popular in Connecticut than in other states due to the number of older and historic homes in the area.
While each policy has specific terms, the biggest difference between them is the type of home they cover.
- HO-2 (Broad Form): Covers your home and personal belongings against a specific list of named perils, such as fire, theft, and certain types of storm damage.
- HO-3 (Special Form): This typically covers the home against all perils except those specifically excluded, and personal belongings are covered against named perils.
- HO-5 (Comprehensive Form): This provides broader coverage by covering both the home and personal belongings against all perils except those specifically excluded.
- HO-6 (Condo Unit-Owners Form): Designed for condominium owners, this typically covers the unit’s interior, personal belongings, liability, and certain improvements.
- HO-8 (Modified Coverage Form): This policy is primarily for older homes where replacement costs may be higher than the home’s market value.
Beyond the type of policy you buy, location also strongly affects Connecticut homeowners insurance rates.
Homes along the southern coast generally cost more to insure because of their greater exposure to coastal storms and other weather-related risks. It can be harder to find cheap homeowners insurance in Connecticut when you live on the coast, but not impossible.
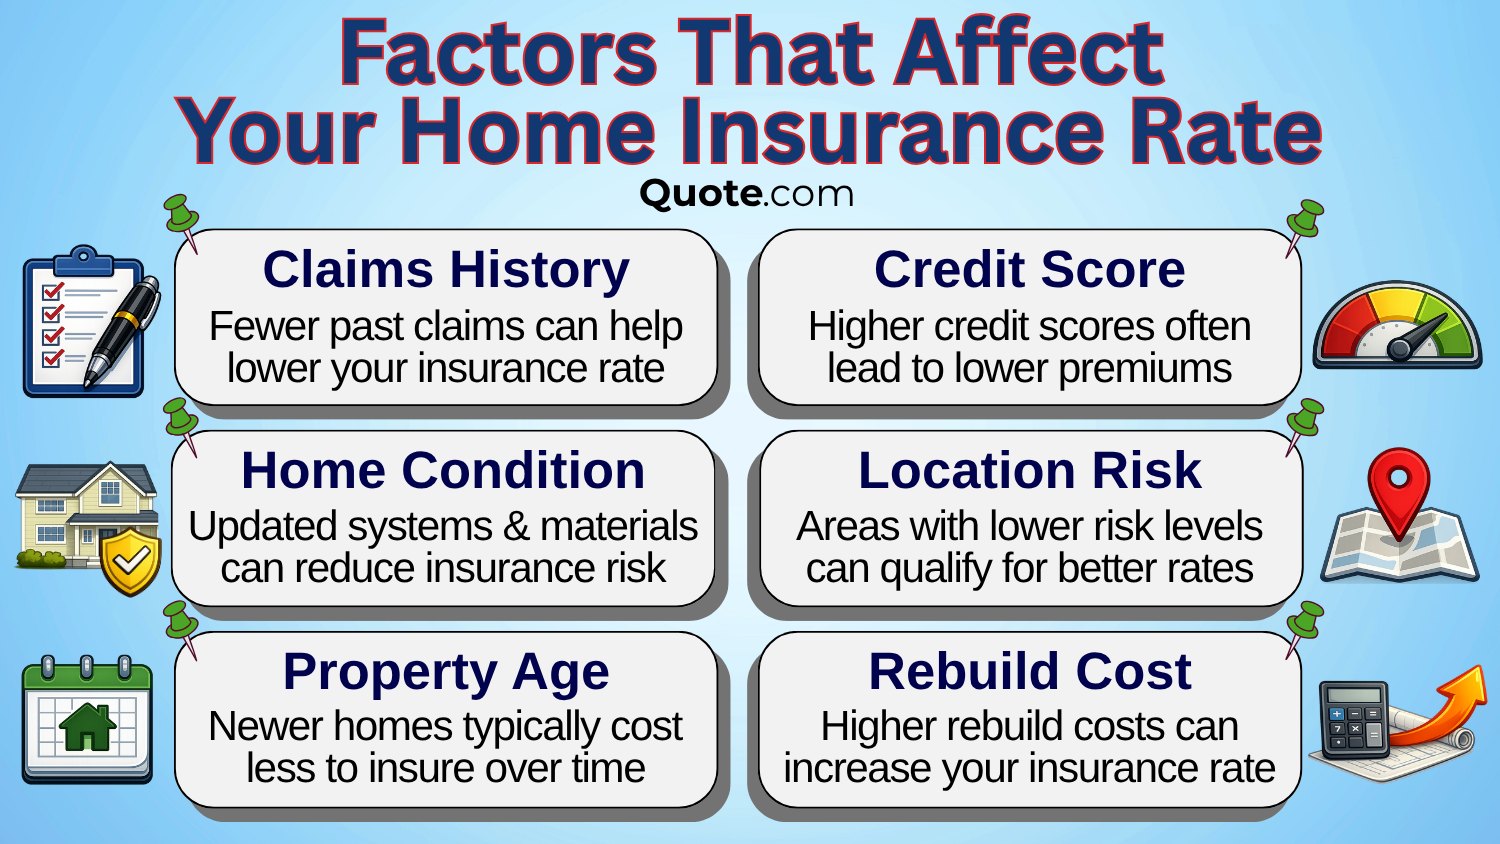
Most insurance companies consider the same factors when they determine home insurance prices in Connecticut. Each factor is weighed differently, based on the company.
Compare quotes from several insurers to find a more affordable policy because each company uses its own underwriting criteria to calculate rates.
How Policy Limits Affect CT Home Insurance Premiums
The amount of dwelling coverage you choose is one of the most important factors affecting your Connecticut home insurance premium.
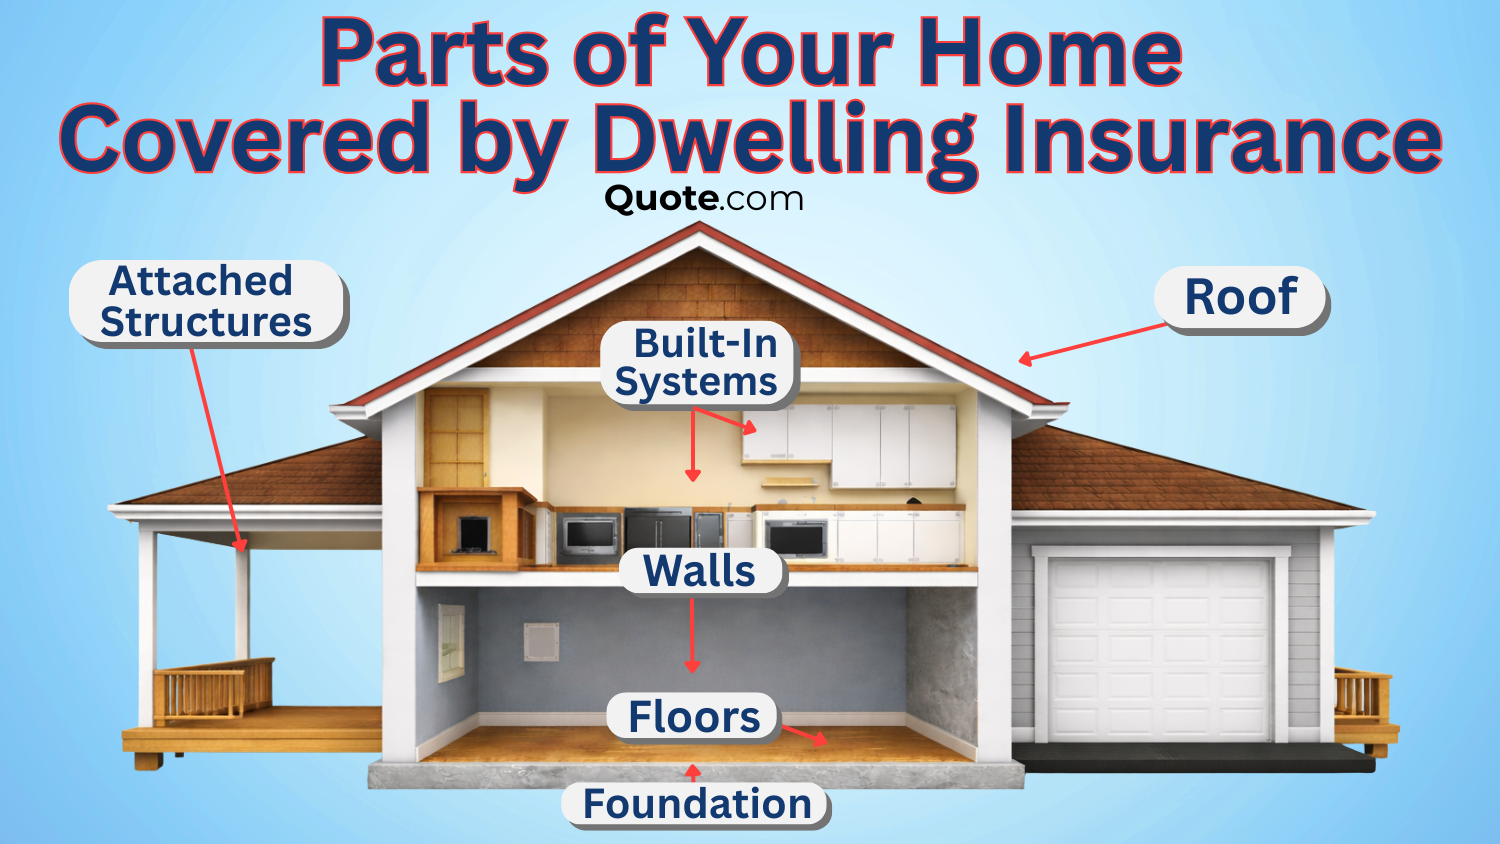
Dwelling coverage pays to repair or rebuild your home’s physical structure after a covered loss, including the roof, walls, foundation, and attached structures.
Connecticut Home Insurance Monthly Rates by Dwelling Coverage| Company | $200K | $300K | $400K | $500K |
|---|---|---|---|---|
| $130 | $163 | $201 | $244 |
| $116 | $147 | $183 | $220 |
| $166 | $213 | $267 | $325 |
| $143 | $181 | $224 | $270 |
| $138 | $174 | $216 | $262 |
| $125 | $158 | $195 | $235 |
| $120 | $152 | $188 | $229 |
| $128 | $160 | $198 | $239 |
| $133 | $168 | $208 | $252 |
| $111 | $140 | $174 | $210 |
Choose a coverage limit based on the estimated cost to rebuild your home, not its market value.
Construction costs, the home’s size and features, and local labor and material prices can all affect how much coverage you need. Find Out More: How much homeowners insurance do you need?
One of the most important factors that affects how much insurance you should buy is where you live. You’ll see ZIP codes on the coast have much higher insurance averages than homes up north.
This price discrepancy comes from the greater risks coastal homes face, like hurricanes and other storms, as well as flooding.
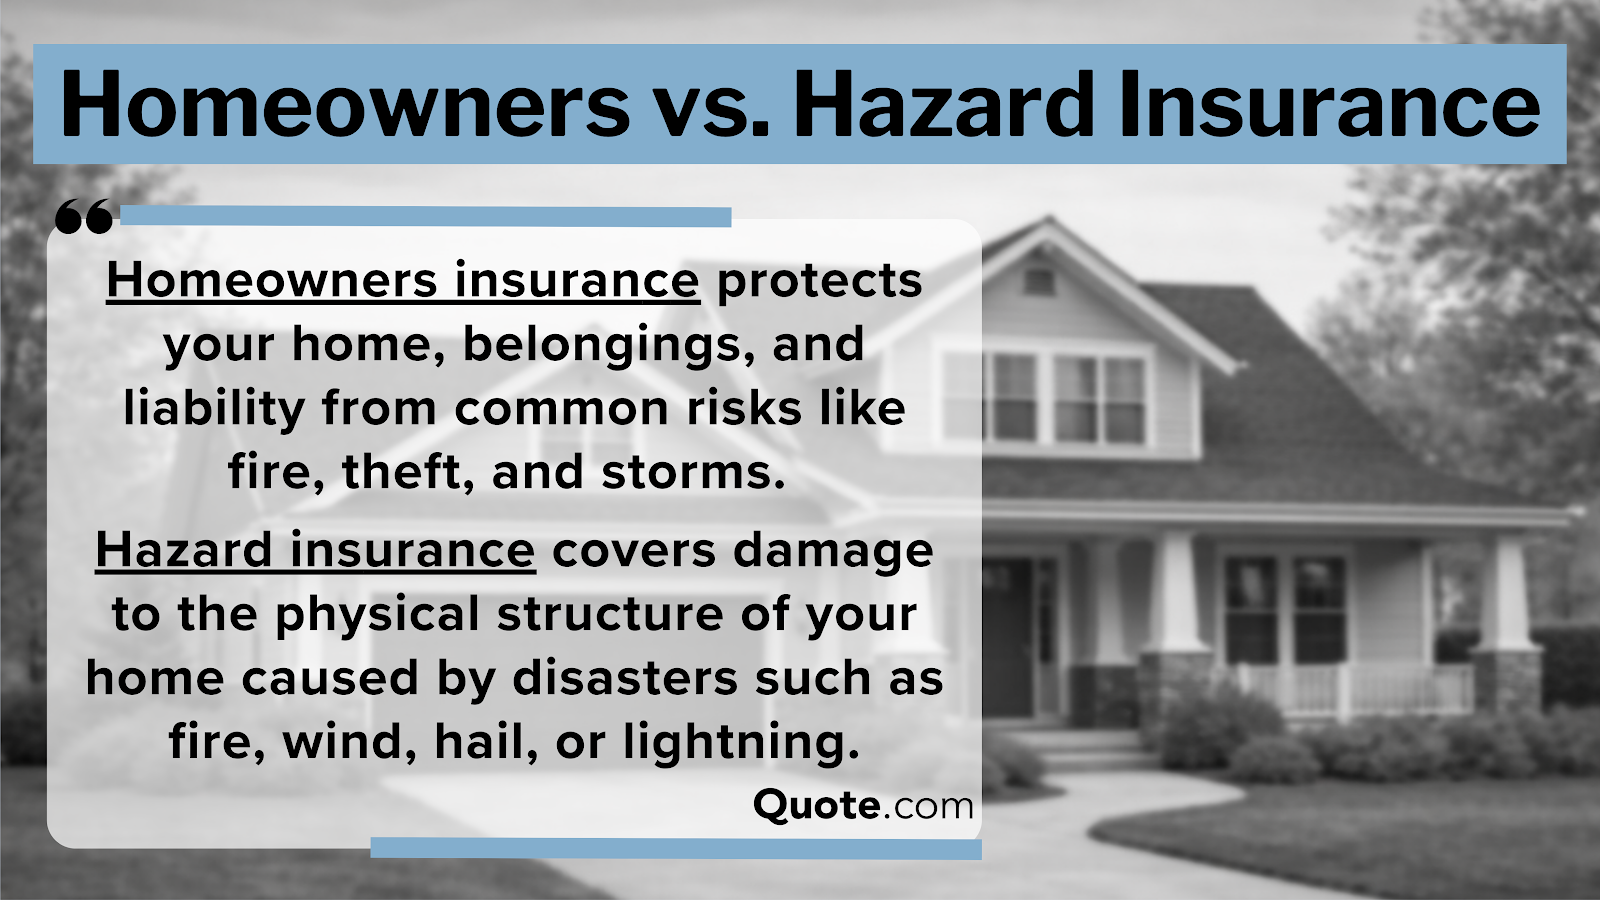
If your home is on the coast, pay close attention to insurers that offer affordable high-risk coverage, like Amica and Travelers.
It may also be worth considering purchasing additional hazard insurance if you live in an area prone to storms or severe winter weather.
How Your Deductible Impacts Connecticut Insurance Prices
Your home insurance deductible is the amount you agree to pay out of pocket before your insurer contributes toward a covered claim.
Generally, choosing a higher deductible lowers your home insurance premium because you assume more of the financial risk yourself. A lower deductible usually costs more but means you pay less when you file a covered claim.
Connecticut Home Insurance Monthly Rates by Deductible| Company | $500 | $1K | $2K | $5K |
|---|---|---|---|---|
| $141 | $130 | $119 | $102 |
| $126 | $116 | $107 | $92 |
| $180 | $166 | $154 | $134 |
| $155 | $143 | $131 | $112 |
| $150 | $138 | $126 | $108 |
| $136 | $125 | $115 | $98 |
| $131 | $120 | $111 | $95 |
| $139 | $128 | $118 | $100 |
| $145 | $133 | $122 | $104 |
| $121 | $111 | $102 | $88 |
If you want the cheapest homeowners insurance rates in Connecticut, look at different deductible amounts. See options where you live with our free tool.
A $5,000 deductible may reduce your premium, but it also means you would need to cover the first $5,000 of a covered claim yourself. Ideally, choose the highest deductible you can afford to ensure you can repair your home. Common CT homeowners insurance deductibles include $500, $1,000, $2,500, and $5,000.
Connecticut homeowners should also pay attention to wind or storm deductibles, particularly if they live near the coast.
Jeff Root Licensed Insurance Agent
Some companies vary premiums more based on your deductible than others. The difference between a $500 deductible and a $5K one at Travelers is just $33 per month, compared to Chubb at $46 monthly.
When you get a quote from a home insurance company, compare your rates based on your deductible before you purchase a policy.
How Common Risks Affect Connecticut Home Coverage
Your home’s risk level can significantly affect how much you pay for homeowners insurance in Connecticut. The best insurance for high-risk homes balances affordable prices with top-tier coverage.
Insurers consider factors such as the home’s age, construction type, roof condition, location, claims history, and exposure to severe weather when setting premiums.
There are ways to find cheap Connecticut home insurance no matter what type of home you have, but minimizing your risk factors can help keep rates down.
Estimated Coverage, Costs, & Risk Levels in Connecticut| Home Value | Coverage | Monthly Rate | Rebuild Costs | Risk Level |
|---|---|---|---|---|
| $200K | $240K | $131 | Low | Standard |
| $225K | $270K | $144 | Low | Standard |
| $250K | $300K | $157 | Moderate | Standard |
| $275K | $330K | $169 | Moderate | Elevated |
| $300K | $360K | $182 | Moderate | Elevated |
| $350K | $420K | $203 | High | Elevated |
| $400K | $480K | $227 | High | Elevated |
| $450K | $540K | $252 | High | Substantial |
| $500K | $600K | $279 | Extreme | Substantial |
| $600K | $720K | $333 | Extreme | Substantial |
While Connecticut home insurance rates are affected by risk factors, there have been no reports of insurance companies canceling policies, as there have been in some states.
Still, Connecticut homeowners will pay higher rates when their homes face more risks from coastal winds or winter freezes.
Connecticut Home Insurance Monthly Rates by Risk Factor| Company | Coastal Wind | Flood Risk | Wind & Hail | Winter Freeze |
|---|---|---|---|---|
| $162 | $182 | $155 | $148 |
| $144 | $159 | $138 | $131 |
| $206 | $226 | $197 | $189 |
| $179 | $201 | $171 | $162 |
| $173 | $194 | $166 | $157 |
| $155 | $175 | $149 | $142 |
| $152 | $170 | $145 | $137 |
| $158 | $178 | $152 | $145 |
| $167 | $187 | $160 | $151 |
| $137 | $154 | $132 | $126 |
Your roof’s condition can also affect both your premium and your ability to obtain coverage. Learn More: How Roof Inspections Affect Home Insurance Costs
If you make repairs or replace your roof, make sure to let your insurance provider know. You might lower your insurance premium.
The Connecticut Insurance Department noted that insurers may inspect roofs using in-person inspections and aerial imagery to determine coverage eligibility.
Dani Best Licensed Insurance Agent
Like any other factor that affects homeowners insurance in CT, the best company for you depends on the type of risk your home faces. Travelers is a safe bet because it tends to offer the cheapest homeowners insurance in Connecticut regardless of risk factor.
Other companies also offer affordable coverage for different risks. Liberty Mutual has low rates for houses facing winter freeze risks, and Progressive is a good choice for wind and hail. Take a closer look in our review: Progressive vs. State Farm Insurance
Connecticut Homeowners Insurance Prices Based on Credit
Your credit history can affect your Connecticut home insurance premium because local insurers use credit-based scores as an underwriting factor.
Finding the cheapest homeowners insurance in CT when you have a low credit score takes a little more research.
Connecticut Home Insurance Monthly Rates by Credit Score| Company | Excellent (800+) | Good (670-799) | Fair (580-669) | Poor (<580) |
|---|---|---|---|---|
| $130 | $143 | $167 | $205 |
| $116 | $125 | $144 | $176 |
| $166 | $178 | $204 | $245 |
| $143 | $159 | $189 | $236 |
| $138 | $153 | $183 | $230 |
| $125 | $137 | $159 | $195 |
| $120 | $134 | $162 | $208 |
| $128 | $139 | $162 | $200 |
| $133 | $146 | $172 | $212 |
| $111 | $120 | $139 | $171 |
Worried about how to buy home insurance if your credit score is low? Connecticut law restricts how insurers can use financial history when rating or underwriting personal insurance.
For example, insurance companies aren’t allowed to reject your application for coverage solely based on your credit score. They also aren’t allowed to use disputed claims on your credit report to determine your premium.
Finally, if your rates are higher because of a lower credit score, the insurance company has to send you a notification explaining why.
If an extraordinary life circumstance has negatively affected your credit, Connecticut law also provides certain exceptions to ease the burden.
Qualifying circumstances can include divorce, the death of a spouse or child, extended involuntary unemployment, identity theft, or a catastrophic illness or injury. Review offers from several insurers to find one willing to work with you.
Free Home Insurance Comparison
Compare Quotes From Top Companies and Save
Qualifying for Discounts on CT Home Insurance
Taking advantage of home insurance discounts is an easy way to keep your annual premiums low.
Home insurance companies in Connecticut offer a variety of discounts across the state, so ask your provider which savings opportunities apply to your policy. Many offer discounts for protective features such as burglar alarms, smoke detectors, deadbolt locks, fire extinguishers, and sprinkler systems.
Top Home Insurance Discounts in Connecticut| Company | Bundling | New Home | No Claims | Security |
|---|---|---|---|---|
| 16% | 12% | 10% | 5% |
| 20% | 14% | 9% | 6% |
| 11% | 16% | 8% | 7% |
| 21% | 11% | 9% | 6% |
| 15% | 13% | 8% | 5% |
| 17% | 12% | 10% | 6% |
| 15% | 10% | 7% | 5% |
| 26% | 11% | 9% | 6% |
| 20% | 13% | 8% | 5% |
| 18% | 14% | 9% | 6% |
Some companies offer savings to customers who renew their policy for an extended period or who belong to qualifying professional, alumni, or business organizations.
A common savings opportunity is auto and home insurance bundling. Farmers and State Farm have the biggest discounts, but Amica stays competitive with 20% savings.
10 Best Home & Auto Insurance Bundle Discounts in Connecticut| Company | Rank | Discount | Savings | Bundle Rules |
|---|---|---|---|---|
| #1 | 26% | $805 | Existing Policy |
| #2 | 21% | $770 | Agent Quote |
| #3 | 20% | $650 | Direct Writer |
| #4 | 18% | $615 | Homeowners |
| #5 | 17% | $585 | Eligible Homes |
| #6 | 16% | $545 | Eligible Policies |
| #7 | 15% | $505 | Shared Address |
| #8 | 15% | $470 | Quote Required |
 | #9 | 12% | $430 | Military Only |
 | #10 | 10% | $365 | Home Agency |
Your home’s condition can also affect whether you qualify for certain discounts. A recently replaced roof, upgraded systems, and improvements to protect against wind or hail may result in lower premiums with some insurers.
Connecticut homeowners should ask their insurer to review recent improvements to make sure they are receiving all applicable discounts.
Other Tips to Save Money on Connecticut Home Insurance
Shopping around is one of the most effective ways to find affordable home insurance in Connecticut.
The state’s insurance department notes that Connecticut has a competitive homeowners insurance marketplace, meaning customers should compare rates from multiple insurers rather than accepting the first quote they receive.
Home Insurance Deductibles in Connecticut: Premium Impact| Category | $500 | $1K | $2K | $5K |
|---|---|---|---|---|
| Best Use | File Often | Less Often | Low Cost | Rare Claims |
| Claim Payout | Largest | High | Moderate | Smallest |
| Claim Rate | Highest | Moderate | Low | Lowest |
| Monthly Rate | $143 | $131 | $120 | $103 |
| Rate Stability | Lowest | Moderate | High | Highest |
Increasing your deductible can also lower your premium, but choose a deductible you could comfortably afford after a covered loss.
Connecticut insurers may offer higher deductible options at reduced premiums, and some policies have separate deductibles for wind, hail, or hurricanes.
5 Most Common Home Insurance Risks in Connecticut| Risk | Claims | Payout | Cost | Area |
|---|---|---|---|---|
| #1 Wind & Hail | 33% | $14K | Moderate | Coastal |
| #2 Winter Storms | 24% | $13K | Moderate | Statewide |
| #3 Water Damage | 21% | $12K | Moderate | Older Homes |
| #4 Flooding | 13% | $31K | High | River Valleys |
| #5 Fire & Lightning | 9% | $38K | High | Woodlands |
Your home’s overall riskiness plays a crucial role in your premiums, so check your coverage limits, deductible, discounts, and recent home improvements with your insurer. Compare Connecticut homeowners insurance quotes from other companies when appropriate.
Finally, review your policy regularly rather than automatically renewing it year after year. Nationwide offers a free On Your Side policy review every year for Connecticut homeowners to review policy changes and savings opportunities.
Don’t Miss It: How to Switch Homeowners Insurance
Figuring Out Your Home Insurance Needs in Connecticut
Base the amount of homeowners insurance you need primarily on how much it would cost to rebuild your home rather than its market value or purchase price.
Construction materials, labor costs, the home’s size and features, and local building requirements can all affect rebuilding costs.
Start by determining your home’s replacement cost and choosing a dwelling coverage limit that provides sufficient protection to rebuild after a covered total loss. Read More: Replacement Costs vs. Actual Cash Value
Connecticut guidance notes that many policies require you to insure the property for at least 80% of its replacement cost to qualify for certain replacement-cost provisions, although insuring the home for 100% of its replacement cost provides stronger protection.
You also need enough coverage for your personal belongings, additional living expenses, and personal liability. Additional coverage may depend on the age and value of your property.
Connecticut Home Insurance Restrictions by Company| Company | Coastal Wind | Inspection? | Roof Limit | Water Damage |
|---|---|---|---|---|
| ⚠️Limited | ❌ | 15 Yrs | ⚠️Limited |
| ⚠️Review | ⚠️Review | 20 Yrs | ✅ |
| ⚠️by Value | ⚠️Review | 20 Yrs | ✅ |
| ⚠️Limited | ❌ | 20 Yrs | ✅ |
| ⚠️Review | ⚠️Review | 15 Yrs | ⚠️Limited |
| ⚠️Limited | ❌ | 20 Yrs | ✅ |
| ⚠️Review | ⚠️Review | 20 Yrs | ⚠️Limited |
| ⚠️Limited | ❌ | 15 Yrs | ⚠️Limited |
| ⚠️Review | ⚠️Review | 20 Yrs | ✅ |
| ⚠️Limited | ⚠️Review | 20 Yrs | ⚠️Limited |
Finally, consider whether you need additional coverage for risks that a standard homeowners policy may exclude. Limited coverage means there are restrictions, while other policy add-ons require a review or inspection.
For instance, standard homeowners insurance generally doesn’t cover flooding, and certain valuable belongings may require scheduled personal property coverage.
Connecticut Homeowners Insurance Coverage Choices
Connecticut residents have several types of homeowners insurance coverage to consider depending on their property and individual needs.
A standard homeowners policy generally includes dwelling coverage, personal property, additional living expenses, personal liability, and medical payments for certain injuries.
Homeowners should also consider whether they need additional coverage beyond a standard policy.
Certain risks may require separate policies or endorsements. Valuable items such as jewelry, antiques, and artwork may require additional or scheduled coverage.
Home Insurance Coverage Options in Connecticut| Company | Flood | Roof | Valuables | Windstorm |
|---|---|---|---|---|
| ⚠️NFIP | ✅Both | ⚠️Limited | ⚠️by Review |
| ⚠️NFIP | ✅RCV | ⚠️Limited | ⚠️by Cost |
| ⚠️Private | ✅RCV | ⚠️Capped | ⚠️by Value |
| ⚠️Private | ✅Both | ➕Add-On | ⚠️by Review |
| ⚠️NFIP | ✅Both | ⚠️Limited | ⚠️by Cost |
| ⚠️Private | ✅Both | ⚠️Capped | ⚠️Limited |
| ⚠️NFIP | ✅Both | ➕Add-On | ⚠️by Location |
| ⚠️NFIP | ✅RCV | ⚠️Limited | ⚠️by Review |
| ⚠️NFIP | ✅Both | ➕Add-On | ⚠️by Cost |
| ⚠️Private | ✅Both | ⚠️Capped | ⚠️by Value |
Reviewing exclusions and coverage limits can help you identify potential gaps. Flood insurance is particularly important to consider in Connecticut.
Standard homeowners policies generally don’t cover flood damage, but homeowners can purchase separate flood insurance through the National Flood Insurance Program or from private insurers.
Free Home Insurance Comparison
Compare Quotes From Top Companies and Save
Top 10 Home Insurance Companies in Connecticut
The top home insurance companies in CT include Amica, The Hartford, and Chubb. These providers offer impressive coverage at affordable rates and are generally considered some of the best home insurance companies overall.
Amica is our top pick for its mix of excellent customer service, low rates, and experience with Connecticut home insurance needs.
10 Largest Home Insurance Companies in Connecticut| Company | Market Share | Policy Count | Premiums Written | Financial Rating |
|---|---|---|---|---|
| 10.1% | 124K | $170.5M | A++ |
| 8.2% | 96K | $138.6M | A+ |
| 7.5% | 84K | $127.1M | A++ |
| 7.0% | 80K | $117.8M | A+ |
| 6.4% | 74K | $108.5M | A |
| 5.8% | 68K | $98.7M | A++ |
 | 4.6% | 54K | $77.6M | A |
| 4.4% | 50K | $73.5M | A |
| 4.2% | 49K | $70.8M | A+ |
| 3.1% | 37K | $53.1M | A+ |
Travelers has the lowest average rates, while Chubb is the best option for high-value, luxury homes. Read on to explore the best homeowners insurance in CT.
Always shop around before you sign up for a policy to avoid overpaying. Make sure to compare Connecticut home insurance quotes by coverage level, deductible, ZIP code, and home age to get more accurate pricing.
#1 – Amica: Top Pick Overall
Pros
- Customer Service: Amica insurance reviews give its stellar home coverage and customer service high ratings.
- Local to New England: Amica is headquartered in Rhode Island and has a long history of serving homeowners throughout New England.
- Competitive Rates: Amica is one of the cheapest options for home insurance in Connecticut at $116 a month.
Cons
- Service Inconsistencies: Some Connecticut homeowners report high satisfaction with the claims process, while others say Amica is slow to resolve issues.
- Coverage Exclusions: A standard homeowners policy from Amica does not eliminate the need to consider separate coverage for some risks.
#2 – The Hartford: Best for Claims Services
Pros
- Claims Service: The Hartford has a reputation for getting home insurance claims resolved quickly in Connecticut.
- Strong Connecticut Presence: Based in Connecticut, The Hartford knows the ins and outs of local risks. Find out more in our article: Review of The Hartford
- AARP Member Benefits: Eligible AARP members can receive special savings and benefits through The Hartford’s homeowners insurance program.
Cons
- AARP Membership: The Hartford primarily serves as AARP’s insurance provider, meaning you need to be a member to buy coverage.
- Discount Availability Varies: Not every The Hartford discount is available in certain parts of Connecticut.
#3 – Chubb: Best for Luxury Homes
Pros
- Excellent Luxury Coverage: Chubb is particularly well suited to Connecticut homeowners who need substantial coverage for expensive homes and belongings.
- High-End Options: Chubb provides more protection than a basic home policy, offering some of the best coverage for high-value properties.
- Customized Coverage: Connecticut homeowners with unique or expensive properties can benefit from Chubb’s comprehensive coverage options.
Cons
- Higher Premiums: More extensive coverage and specialized services can result in higher Connecticut premiums from Chubb.
- Standard Policies Lacking: Connecticut homeowners with minimal and straightforward coverage needs may find a standard insurer with better rates.
#4 – Liberty Mutual: Best for Flexible Coverage Options
Pros
- Flexible Coverage Options: Liberty Mutual offers a ton of coverage options so Connecticut homeowners can get exactly what they want.
- Numerous Discounts: Connecticut homeowners can qualify for Liberty Mutual savings based on factors such as bundling, buying online, and having a new or renovated home.
- Convenient Online Experience: Liberty Mutual lets CT homeowners start and customize a home quote online. See how it works in our guide: Liberty Mutual Review
Cons
- Bundling Necessary: Homeowners who only need property insurance may not receive the same savings as customers who combine Liberty Mutual policies.
- Rates Vary Substantially: A competitive advertised discount does not necessarily mean Liberty Mutual will offer the lowest Connecticut premium for your particular home.
#5 – Nationwide: Best Policy Add-Ons
Pros
- Add-On Options: Customize your home insurance policy with its selection of add-ons. See More: Nationwide Insurance Review
- Wide Range of Discounts: Nationwide offers potential savings for protective devices, claims-free customers, and qualifying renovations, among other savings opportunities.
- Older Home Savings: If you upgrade an older Connecticut home, Nationwide may offer discounts and lower monthly premiums.
Cons
- Property Restrictions: Nationwide doesn’t offer coverage to mobile or manufactured homes in Connecticut.
- Rate Variations: Connecticut homeowners in higher-risk coastal or storm-prone areas may pay more than those in lower-risk areas.
#6 – Progressive: Best Digital Tools
Pros
- Online Tools: Progressive offers a range of digital insurance tools for Connecticut homeowners who need quick and standard coverage.
- Competitive Prices: Progressive is known for offering affordable home insurance rates in Connecticut. Compare quotes in our review: Progressive Insurance Review
- Coastal-Risk Considerations: Progressive offers a ton of guidance for homeowners in coastal areas, making it easier to keep your insurance rates as low as possible.
Cons
- Rate Increases: Some Connecticut homeowners report that Progressive increased their monthly premiums without any apparent reason.
- Coverage Varies: Progressive policy options, like water backup coverage, may be available as an optional endorsement rather than automatically included.
#7 – Travelers: Best for Historic Homes
Pros
- Historic Homes: Connecticut homeowners with historic properties will enjoy Travelers’ expertise with older homes.
- Unique Discounts: Travelers offers hard-to-find discounts to Connecticut homeowners, like savings for green and smart-home features.
- Strong Presence: Travelers maintains a large network of local agents in Connecticut so you can always get the help you need for your home insurance.
Cons
- Higher Coastal Rates: Connecticut homeowners near the shoreline face weather-related risks that can affect Travelers premiums.
- Unexplained Denials: Some Travelers insurance reviews report that the company denied their CT home insurance claims unexpectedly and without explanation.
#8 – Farmers: Best Policy Perks
Pros
- Policy Perks: Farmers offers a variety of policy perks for Connecticut homeowners, including unique discounts and other savings. Shop Now: Farmers Insurance Review
- Varied Policy Coverage: Farmers offers homeowners insurance in Connecticut for single-family homes, condos, seasonal or vacation properties, and older homes.
- Generous Discounts: Farmers offers discounts for bundling, protective devices, claims-free histories, new homes, smart-home technology, and certain home improvements.
Cons
- Agent Involvement: Many customers report frustration that managing policies and filing claims often requires direct involvement from a Farmers agent.
- Higher Rates Possible: Individual property characteristics and location can make Farmers more expensive for certain Connecticut homeowners.
# 9 – State Farm: Best for Bundling Savings
Pros
- Bundling Savings: Connecticut homeowners who combine home and auto insurance with State Farm may qualify for a multi-policy discount.
- Local Agent Presence: State Farm’s agent-based model can give Connecticut homeowners personalized assistance when choosing coverage or filing a claim.
- Roof-Related Savings: Eligible homeowners can potentially receive premium reductions for qualifying roofing materials and installations.
Cons
- Higher Complaints: State Farm receives more complaints for its home insurance and other products than expected for a company its size.
- Long Claims Processing Times: Some State Farm insurance reviews in Connecticut report that it took a long time processing homeowners claims.
#10 – Allstate: Best Discount Options
Pros
- Ample Discounts: Allstate offers potential discounts for bundling, claims-free histories, protective devices, responsible payment, and recent home purchases.
- Affordability: While Allstate is often considered expensive for car insurance, its home policies are generally more affordable.
- Claim RateGuard: Similar to accident forgiveness, RateGuard from Allstate prevents your premiums from increasing just because you filed a claim.
Cons
- Below-Average Claims Satisfaction: Although many Connecticut customers are happy with their policies, many local Allstate reviews are unsatisfied with its claims service.
- Agent Requirements: You can browse and get quotes from Allstate online, but you have to finalize your home insurance purchase with an agent.
Get the Best Connecticut Home Insurance Today
Choosing the best homeowners insurance in Connecticut starts with finding a company that offers the right combination of coverage and affordability for your property.
Amica, The Hartford, and Chubb each have strengths that appeal to different Connecticut homeowners, whether you prioritize competitive rates, extensive coverage, discounts, local service, or protection for a high-value home.
Before selecting a policy, compare homeowners insurance quotes from several providers and review the coverage limits, deductibles, exclusions, and available discounts.
To see how much Connecticut home insurance might cost based on where you live, use our free comparison tool today.
Frequently Asked Questions
Who has the best home insurance in Connecticut?
The best home insurance company in Connecticut depends on your coverage needs, budget, home, and preferred features. Companies such as Amica, The Hartford, and Chubb are often worth considering because of their coverage options, customer service, financial strength, and availability in Connecticut.
Is home insurance required in Connecticut?
There are no legal Connecticut homeowners insurance requirements, but mortgage lenders typically require it as a condition of a home loan. Even when it isn’t required, homeowners insurance can help protect your home, belongings, and finances from covered losses.
Read More: Is home insurance required?
How much homeowners insurance coverage do I need in Connecticut?
You generally need enough dwelling coverage to fully rebuild your home after a covered loss, not just match its market value. You should also consider adequate personal property, liability, and additional living expenses coverage based on your assets. Learn more in our guide to decide what to include in your policy: Homeowners Insurance Coverage Explained
How much does home insurance cost in Connecticut?
The cost of homeowners insurance in Connecticut varies depending on your home’s location, age, and construction, plus your policy’s coverage limits, deductible, and claims history. To find cheap homeowners insurance in Connecticut, enter your ZIP code into our free comparison tool today.
What factors affect home insurance rates in Connecticut?
Connecticut home insurance quotes can be affected by your home’s location, replacement cost, age, construction materials, roof condition, claims history, coverage limits, deductible, and, where permitted, your credit-based insurance score. Risks such as coastal storms, severe weather, and proximity to bodies of water can also influence home insurance premium costs.
How can I lower my homeowners insurance premiums in Connecticut?
Increase your deductible, bundle home and auto insurance, and use available discounts. Installing security systems, smoke detectors, storm-resistant features, and other protective devices may also help reduce your rate. Learn how to compare home insurance quotes, or you’ll likely overpay for your coverage.
Who has the cheapest home insurance in Connecticut?
No single insurer is cheapest for every Connecticut homeowner because premiums depend on individual and property-specific factors. Comparing quotes from several companies, including regional and national insurers, can help you find the lowest rate for the coverage you need. Use our free quote tool to compare personalized home insurance rates based on where you live.
Does home insurance cover flood damage in Connecticut?
Standard homeowners insurance generally does not cover flood damage, so it’s a good idea to purchase flood coverage in Connecticut, depending on where you live. If you’re unsure, an insurance representative from your provider can help you.
Does homeowners insurance cover hurricane damage in Connecticut?
Standard homeowners insurance generally covers many types of hurricane-related damage, such as wind damage, subject to the policy’s terms, limits, and exclusions. However, flooding and storm surge are generally excluded from standard homeowners policies. Some policies may also have separate wind or hurricane deductibles.
How much should CT home insurance be on a $400,000 home?
Your monthly premium for a $400K home depends on several factors, but the average is about $227 per month. To find the best coverage for your needs and the most affordable rates, check rates from multiple companies.
Related Articles
-
Apr 2026

Home Insurance Rates by State in 2026
-
Aug 2026
Best Home Insurance in Delaware for 2026
-
Feb 2026
How much homeowners insurance do you need in 2026?
-
Sep 2026
Best Home Insurance in Alaska for 2026
-
Jun 2026
Flood Insurance: Coverage, Costs & Requirements (2026 Guide)
-
Jun 2026
Home Insurance Rates in 2026
Get a FREE Quote in Minutes
Insurance rates change constantly — we help you stay ahead by making it easy to compare top options and save.