Best Home Insurance in Minnesota for 2026
Amica, Chubb, and Nationwide offer the best home insurance in Minnesota, with rates starting at around $120 per month with a $5K deductible. The top Minnesota home insurance companies specialize in concerns like snow, ice, and tornadoes, while still offering valuable dwelling, property, and liability coverage.
Read more
Table of Contents
Table of Contents
Social Media Manager & Professor
Ashley Dannelly has a Master of Arts in English and serves as the Social Media Manager for Quote.com's portfolio of websites. Ashley also teaches English at Columbia International University and other higher education institutions. Ashley’s background in English and media has allowed her the unique opportunity to edit and create content for many publications, including Livestrong and DiveIn....
Ashley Dannelly
Managing Editor
Daniel S. Young began his professional career as chief editor of The Chanticleer, a Jacksonville State University newspaper. He also contributed to The Anniston Star, a local newspaper in Alabama. Daniel holds a BA in Communication and is pursuing an MA in Journalism & Media Studies at the University of Alabama. With a strong desire to help others protect their investments, Daniel has writt...
Daniel S. Young
Licensed Insurance Agent
Kristen is a licensed insurance agent working in the greater Boston area. She has over 20 years of experience counseling individuals and businesses on which insurance policies best fit their needs and budgets. She knows everyone has their own unique needs and circumstances, and she is passionate about counseling others on which policy is right for them. Licensed in Massachusetts, New Hampshir...
Kristen Gryglik
Updated September 2026
The best home insurance in Minnesota comes from Amica, Chubb, and Nationwide. Amica’s rates start at $142 per month.
- Minnesota homeowners insurance rates are close to the national average
- Severe winter storms are common threats to Minnesota homes
- The FAIR plan can help low-income homeowners get coverage
The best homeowners insurance companies in Minnesota sell policies to protect your home against ice storms, freeze damage, and even tornadoes.
While Minnesota home insurance rates are generally affordable, you can save by finding discounts, upgrading your home, and comparing quotes.
Top 10 Companies: Best Home Insurance in Minnesota| Company | Rank | Claims Satisfaction | Complaints | Best for |
|---|---|---|---|---|
 | #1 | 773 / 1,000 | Low | Customer Care |
 | #2 | 744 / 1,000 | Low | Luxury Homes |
 | #3 | 720 / 1,000 | Mid | Policy Add-ons |
 | #4 | 704 / 1,000 | Mid | Bundle Savings |
 | #5 | 700 / 1,000 | Low | Green Homes |
 | #6 | 700 / 1,000 | Low | Plan Savings |
 | #7 | 691 / 1,000 | High | Custom Policies |
 | #8 | 690 / 1,000 | Mid | Local Agents |
 | #9 | 681 / 1,000 | Low | Rate Savings |
 | #10 | 672 / 1,000 | Mid | New Owners |
Read on to learn more about the top home insurance companies in Minnesota and which might be right for you.
Then, when you’re ready to see personalized quotes, enter your ZIP code in our free comparison tool.
Average Cost of Home Insurance in Minnesota
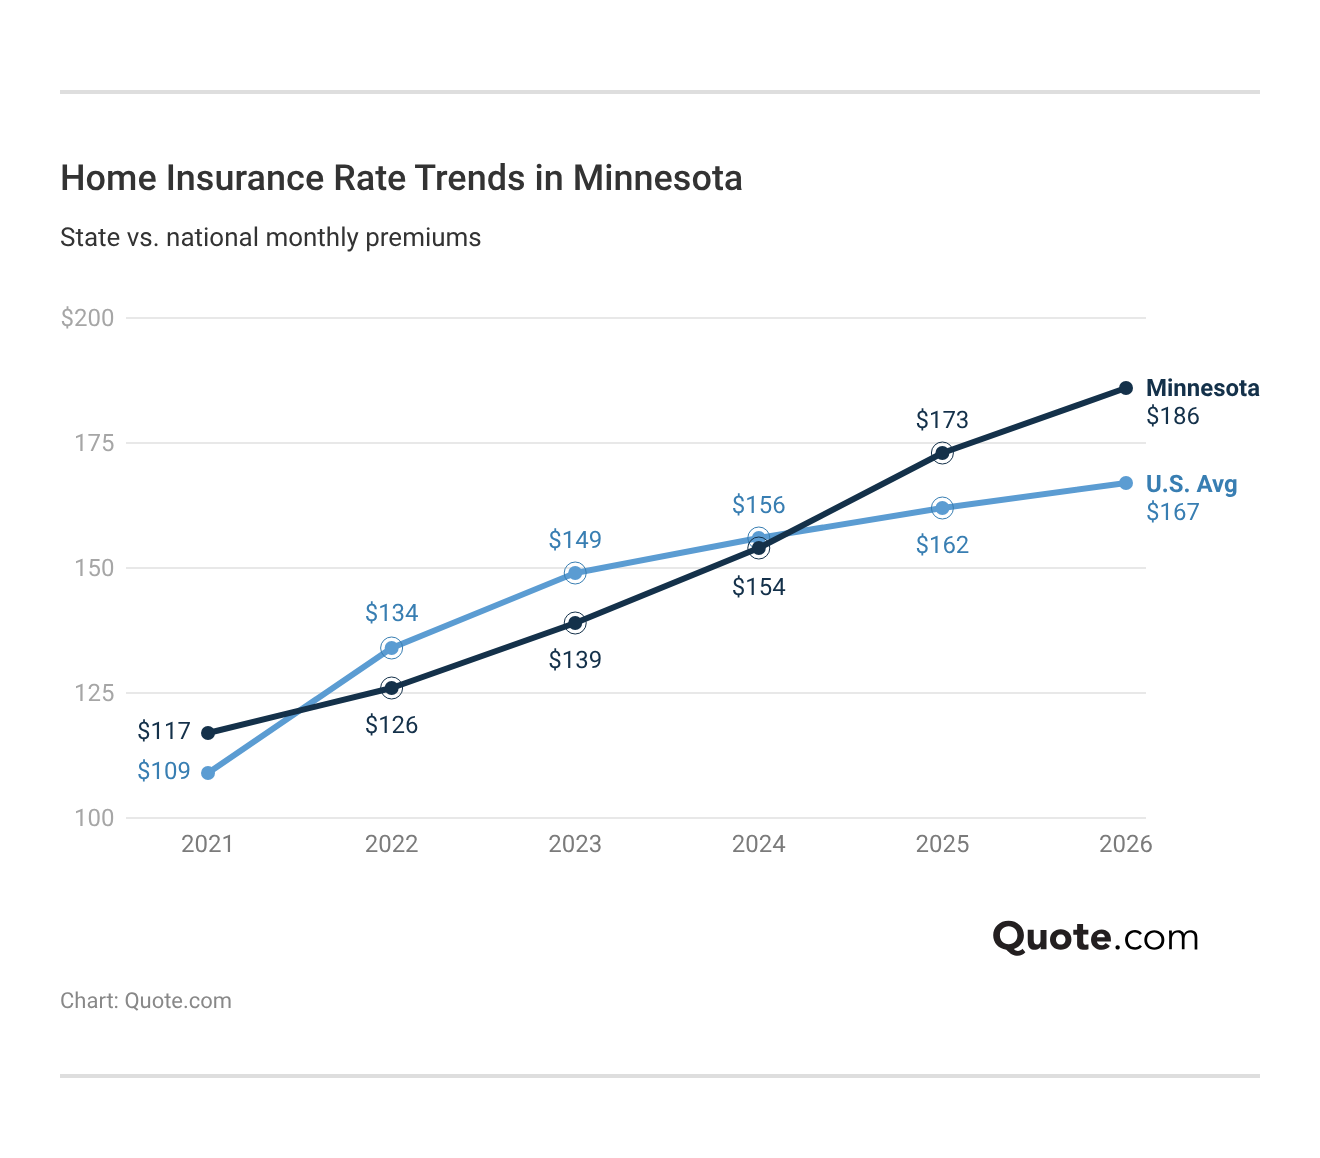
Minnesota homeowners pay an average of about $2.2K per year for their coverage with a $1K deductible. That comes to about $186 per month, similar to the national average.
Of course, the amount you’ll pay for insurance varies by many factors. One of the most important is how much dwelling coverage you need.
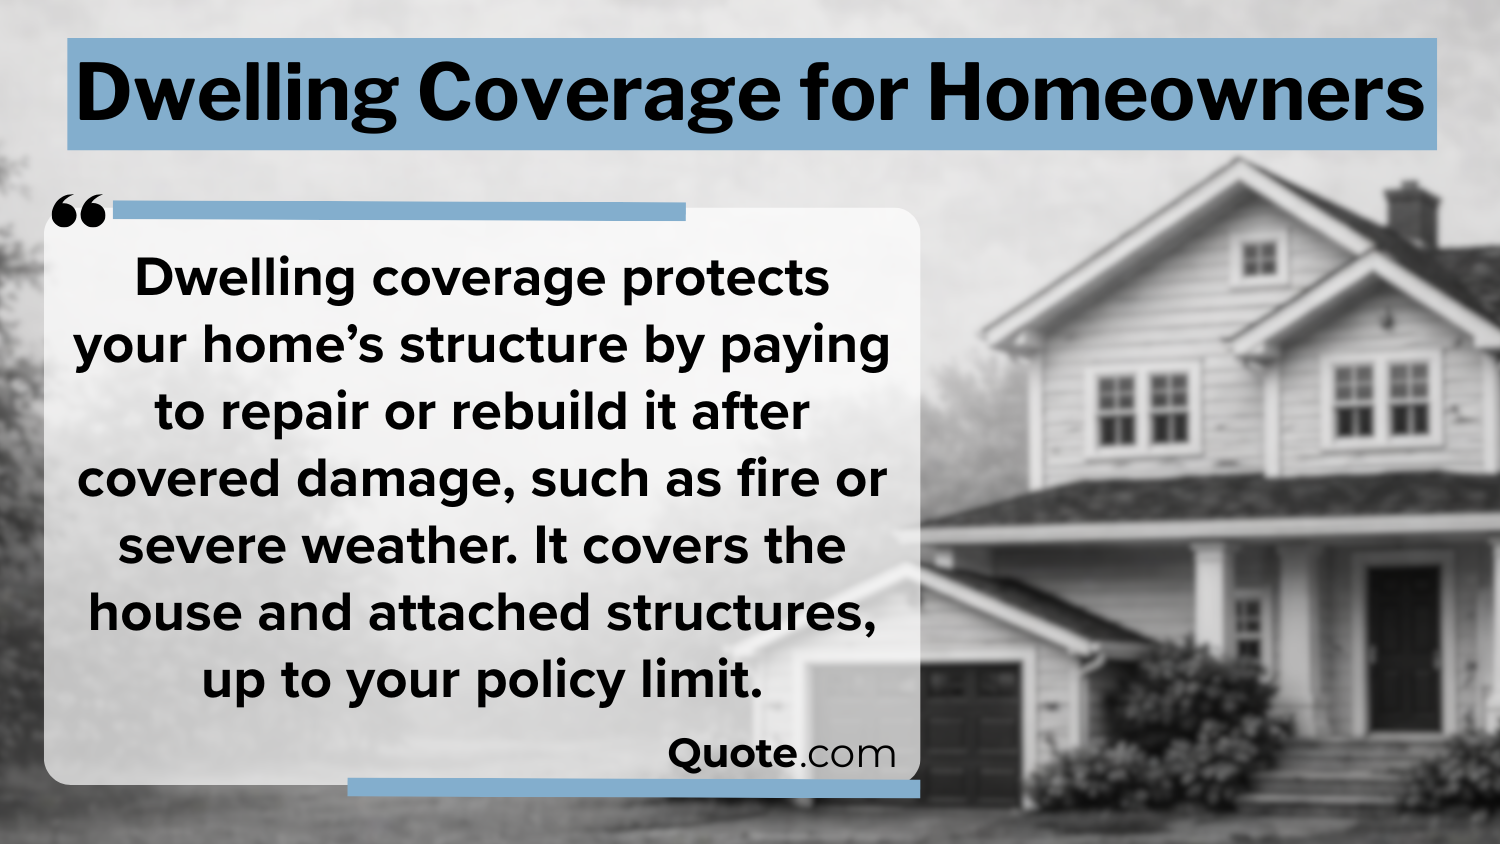
The more your home costs to repair or replace, the more you’ll have to pay for insurance. Finding the cheapest homeowners insurance gets harder as your repair costs grow.
Home insurance rates in Minnesota can run high for reasons outside of your home’s overall value, though.
Minnesota Home Insurance Monthly Rates by Dwelling Coverage| Company | $200K | $300K | $400K | $500K |
|---|---|---|---|---|
| $198 | $268 | $341 | $409 |
| $219 | $299 | $379 | $454 |
| $172 | $234 | $297 | $358 |
| $187 | $252 | $321 | $386 |
| $224 | $307 | $392 | $472 |
| $166 | $224 | $286 | $343 |
| $179 | $243 | $309 | $371 |
| $157 | $213 | $272 | $328 |
| $198 | $267 | $338 | $405 |
| $161 | $219 | $279 | $336 |
Costs are also affected by Minnesota’s severe weather, such as hail, strong winds, winter storms, and even tornadoes.
These common weather risks are part of why Minnesota home insurance rates have been climbing.
MN home insurance companies also spread out the cost of increased claims over their entire customer base, so you’ll see a bit of an increase from that even if you don’t live in a high-risk area.
Home insurance quotes in Minnesota are a little higher than in other states, so the state offers the FAIR Plan to help low-income homeowners get affordable coverage. The FAIR Plan helps qualifying applicants get property and liability coverage for their home. Check rates in your area to find more competitive premiums.
Comparing Homeowners Insurance Across Minnesota
Of course, the type of coverage you buy isn’t the only thing that matters. The ZIP code you live in plays a crucial role in how much you pay for coverage.
Counties with higher weather risks in Minnesota see higher homeowners insurance rates. Northern Minnesota homes typically cost less to insure than those in the south because they experience fewer severe weather risks.Depending on where you live, you may want to consider buying flood, wind, or hazard insurance, even though it increases your premium.
If your MN homeowners insurance rates are closer to $400 a month, compare quotes to see if you can find more affordable coverage. The best way to compare costs online in your area is to use our free comparison tool.
Choosing a Home Insurance Deductible in Minnesota
Your insurance deductible is the amount you pay out of pocket toward a covered claim before your insurer pays the remaining eligible expenses.
If a covered loss causes $10K in damage and your deductible is $1K, you would pay the first $1K, and your insurer would pay the remaining $9K.
Minnesota Home Insurance Monthly Rates by Deductible| Company | $500 | $1K | $2K | $5K |
|---|---|---|---|---|
| $220 | $198 | $181 | $151 |
| $243 | $219 | $200 | $168 |
| $190 | $172 | $157 | $133 |
| $207 | $187 | $170 | $143 |
| $246 | $224 | $205 | $174 |
| $184 | $166 | $151 | $127 |
| $199 | $179 | $163 | $137 |
| $175 | $157 | $143 | $120 |
| $221 | $198 | $179 | $149 |
| $179 | $161 | $146 | $122 |
Choosing a higher deductible lowers your Minnesota home insurance premium because you agree to take on more of the financial responsibility if you file a claim. If you choose a lower deductible, you’ll pay more per month, but you won’t have to worry about a huge bill after filing a claim.
Progressive and Travelers are the most competitive with a $5K deductible, but shop around to find the best rates in your neighborhood.
Minnesota Home Insurance Premiums by Risk Level
Your home’s location, age, construction, condition, and claims history can all affect the insurer’s risk assessment.
In Minnesota, that can include risks from severe thunderstorms, hail, tornadoes, wind, winter storms, and other weather-related events.
5 Most Common Home Insurance Risks in Minnesota| Risk | Claims | Payout | Cost | Area |
|---|---|---|---|---|
| #1 Wind & Hail | 46% | $32K | High | Central |
| #2 Winter Freeze | 17% | $21K | High | Statewide |
| #3 Water Damage | 12% | $14K | Moderate | River Areas |
| #4 Wildfire | 8% | $88K | Highest | Northeast |
| #5 Winter Storms | 6% | $18K | Moderate | Northwest |
A Minnesota home in an area that frequently experiences severe weather claims typically has higher premiums than a similarly priced home in a less risky area since your provider is more likely to incur costly home repairs.
Insurers don’t all evaluate risk in exactly the same way, so a claim that affects your premium with one company may have a different effect with another.
Minnesota Home Insurance Monthly Rates by Risk Factor| Company | Water Damage | Wildfire | Wind & Hail | Windstorms |
|---|---|---|---|---|
| $236 | $231 | $254 | $224 |
| $261 | $257 | $281 | $245 |
| $202 | $199 | $216 | $191 |
| $221 | $217 | $244 | $208 |
| $267 | $262 | $287 | $247 |
| $198 | $194 | $219 | $186 |
| $212 | $208 | $232 | $199 |
| $188 | $184 | $207 | $176 |
| $233 | $229 | $251 | $220 |
| $191 | $187 | $211 | $180 |
Progressive and Travelers remain the cheapest providers across all risk levels, but a policy with a slightly higher rate from Amica or Chubb could provide better protection for your particular home.
Some insurers also have separate deductibles for wind or hail losses, and these can sometimes be based on a percentage of the home’s insured value. The best insurance for high-risk homes makes getting wind and hail damage coverage easy.
Insurers consider characteristics of the individual property, such as the age and condition of the roof.
Dani Best Licensed Insurance Agent
The policy limits determine how much your insurance company will pay for different types of damage, and you may want to increase your coverage if your home is at risk for wind and winter freeze damage.
Your personal claims history can also affect your rates. A homeowner who has recently filed several claims may be considered a greater insurance risk than someone with no recent claims.
Because Minnesota’s weather risks can vary by location, homeowners should compare policies based on more than the quoted premium.
Comparing home insurance quotes is easy with our online tool, and you can check policies for weather-risk coverage.
Credit Scores and Minnesota Home Insurance Quotes
Credit can affect the price of homeowners insurance in Minnesota. Insurers rely on a credit-based insurance score instead of the credit score consumers typically see when applying for a mortgage or credit card.
These insurance scores use information from a person’s credit and claim history to help predict the likelihood of future insurance losses.
Minnesota Home Insurance Monthly Rates by Credit Score| Company | Excellent (800+) | Good (670-799) | Fair (580-669) | Poor (<580) |
|---|---|---|---|---|
| $198 | $218 | $271 | $349 |
| $219 | $244 | $310 | $402 |
| $172 | $188 | $232 | $298 |
| $187 | $204 | $249 | $318 |
| $224 | $241 | $292 | $365 |
| $166 | $184 | $233 | $303 |
| $179 | $196 | $241 | $307 |
| $157 | $174 | $216 | $279 |
| $198 | $217 | $268 | $344 |
| $161 | $176 | $214 | $271 |
According to the Minnesota Legislature, insurers may use credit information as part of the underwriting and rating process, but state law sets requirements for how insurers use it.
When an insurer uses credit information for underwriting, it must disclose that it will obtain and use credit information as part of the insurance underwriting process.
Credit information cannot be the only underwriting factor used to determine eligibility for Minnesota homeowners insurance.
Jeff Root Licensed Insurance Agent
Homeowners with higher credit scores receive cheaper insurance rates than those with lower scores.
The good news is that you’re not stuck with higher rates forever. If you can improve your credit score, your insurance rates will gradually decrease.
Read More: How to Buy Home Insurance Coverage
Free Home Insurance Comparison
Compare Quotes From Top Companies and Save
How Much Home Insurance You Need in Minnesota
The amount of MN home insurance you need depends primarily on how much it would cost to rebuild your home.
Rebuilding costs focus on labor, materials, and construction needed to reconstruct the home. A house with a modest market value could therefore require substantial dwelling coverage if rebuilding it would be expensive.
Estimated Coverage, Costs, & Risk Levels in Minnesota| Home Value | Coverage | Monthly Rate | Rebuild Costs | Risk Level |
|---|---|---|---|---|
| $200K | $238K | $186 | Low | Standard |
| $225K | $267K | $207 | Low | Standard |
| $250K | $296K | $224 | Moderate | Standard |
| $275K | $324K | $243 | Moderate | Elevated |
| $300K | $358K | $253 | Moderate | Elevated |
| $350K | $412K | $301 | High | Elevated |
| $400K | $468K | $321 | High | Substantial |
| $450K | $526K | $379 | High | Substantial |
| $500K | $584K | $384 | Extreme | Substantial |
| $600K | $695K | $486 | Extreme | Substantial |
Rising home costs directly affect insurance premiums, and replacement costs can differ from your home’s market value. If your house is valued at $300K but you need $358K to cover rebuilding costs, you’ll pay about $253 per month.
How much homeowners insurance do you need? Your dwelling coverage should be high enough to cover the estimated replacement cost of the home’s structure, while other portions of a homeowners policy cover personal belongings and liability.
- Dwelling Coverage: Dwelling coverage repairs or rebuilds the home’s structure after a covered loss, up to the policy limit.
- Loss of Use Coverage: This coverage helps pay for living expenses if a covered loss makes your home temporarily uninhabitable.
- Other Structures Coverage: This helps cover detached structures such as garages, sheds, and fences.
- Personal Liability Coverage: Liability coverage protects you financially if you are legally responsible for someone else’s injuries or certain property damage.
- Personal Property Coverage: Personal property coverage pays to repair or replace items like furniture, clothing, electronics, and appliances.
There are times when additional coverage is recommended. For example, if you have expensive jewelry, fine art, or valuable sports or music equipment, you’ll probably want to get extended personal items coverage.
While these types of coverage are included in most policies, you should be aware of restrictions. Companies are usually clear about what isn’t included in your policy, but it’s always a good idea to research first.
Minnesota Home Insurance Restrictions by Company| Company | Inspection? | Roof Limit | Wildfire | Winter Freeze |
|---|---|---|---|---|
| ⚠️by Age | 20 Yrs | ✅ | ⚠️Capped |
| ⚠️by Review | 20 Yrs | ✅ | ✅ |
| ⚠️by Review | 25 Yrs | ⚠️by Review | ⚠️by Review |
| ⚠️Exterior | 20 Yrs | ⚠️by Condition | ⚠️by Condition |
| ⚠️by Value | 25 Yrs | ⚠️by Review | ⚠️Limited |
| ⚠️by Age | 15 Yrs | ⚠️Limited | ⚠️by Condition |
| ⚠️by Review | 20 Yrs | ⚠️by Review | ⚠️by Review |
| ⚠️Varies | 20 Yrs | ⚠️Varies | ⚠️Varies |
| ⚠️by Age | 20 Yrs | ⚠️Limited | ⚠️Capped |
| ⚠️by Review | 20 Yrs | ⚠️Limited | ⚠️by Review |
The best Minnesota home insurance company will have the best options for your house, but the most popular choices are a good place to start.
Minnesota home insurance reviews recommend Amica’s combination of customer care and affordability. Review several offers from insurers in your area to see how it compares.
Home Insurance Options in Minnesota
Minnesota homeowners have several types of insurance policies and coverage options to consider. The right choice depends on whether you own a single-family home, condominium, mobile home, or another type of property.
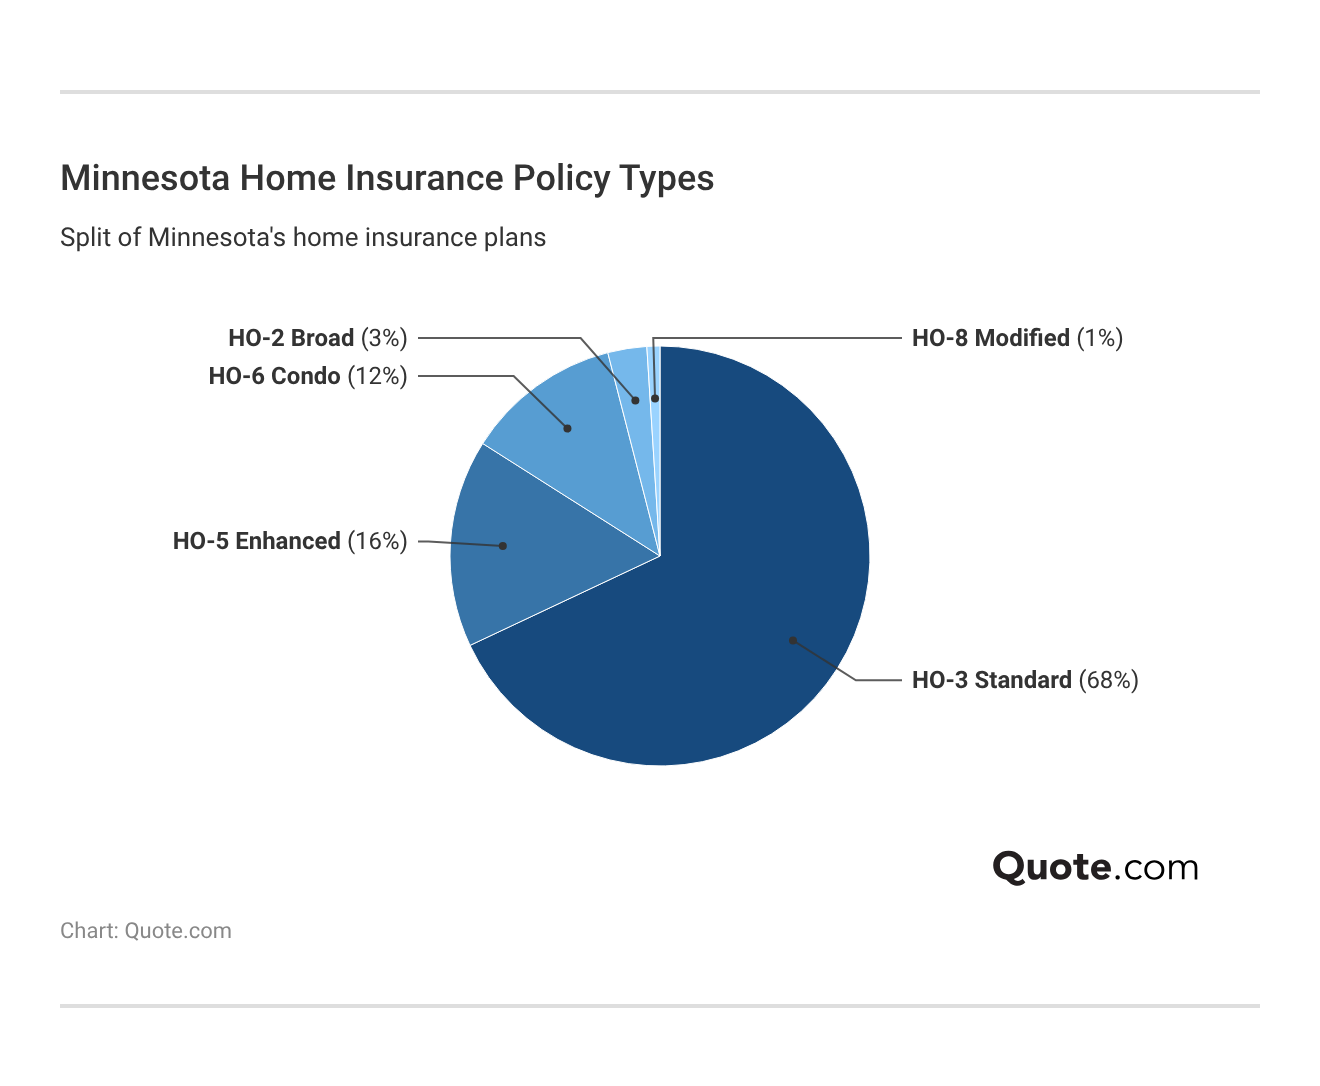
The most common homeowners policy is an HO-3 policy. HO-3 policies provide broad coverage for the dwelling, but there are several other types to consider:
- HO-2 Policy: This provides coverage for the home and personal property against a list of covered perils. It provides less protection than an HO-3 policy.
- HO-3 Policy: The most common homeowners policy, providing broad dwelling coverage subject to the policy’s exclusions and limitations.
- HO-5 Policy: This provides broader coverage than an HO-3 policy and may be worth considering for homeowners who want more extensive protection.
- HO-8 Policy: This uses actual cash value rather than replacement cost for covered property. It’s sometimes used for older homes where rebuilding the property costs more.
While these are the basic types of home insurance, your actual policy will consist of a variety of coverage types. Most insurance companies offer the same basic coverages, plus many add-ons.
For the most part, you’ll automatically buy an HO-3 policy when you sign up for home insurance. You probably don’t have to worry about which type of policy to purchase because you’ll probably be matched with the right plan when you enter your home information.
Even with all these basic types of home insurance, there are plenty of add-ons that increase the amount of coverage in your policy. Not every home needs additional coverage, but they can benefit homeowners in riskier areas.
Some of the most popular home insurance add-ons protect against weather risks like hail, ice, and wind. Frozen water can also cause burst pipes and roof damage, which are major risks for Minnesota homes. Water damage from these types of events can lead to costly repairs.
Home Insurance Coverage Options in Minnesota| Company | Flood | Roof | Sewer | Wind & Hail |
|---|---|---|---|---|
| ✅Both | ✅ACV | ➕Add-On | ➕Add-On |
| ✅Both | ➕Add-On | ➕Add-On | ✅ |
| ⚠️NFIP | ⚠️Varies | ➕Add-On | ✅ |
| ✅Both | ➕Add-On | ➕Add-On | ➕Add-On |
| ⚠️Private | ✅RCV | ✅ | ⚠️Limited |
| ⚠️Private | ✅ACV | ➕Add-On | ✅ |
| ⚠️Private | ➕Add-On | ➕Add-On | ✅ |
| ✅Both | ➕Add-On | ⚠️Varies | ⚠️Limited |
| ⚠️NFIP | ✅RCV | ➕Add-On | ✅ |
| ⚠️Private | ✅ACV | ➕Add-On | ✅ |
If you want flood insurance for your home, you can get information from your provider. Alternatively, you can visit the National Flood Insurance Program for more information.
For Minnesota homeowners, the goal isn’t necessarily to find the policy with the most coverage or the lowest price. Instead, you should use our free insurance comparison tool to find a policy that includes as much coverage as you need to keep your home safe.
How Minnesota Homeowners Can Save on Insurance
Minnesota home insurance discounts vary by insurer, and not every company offers the same savings opportunities.
Picking a company that offers the most discounts to you is a crucial step in saving on your Minnesota home insurance. Amica offers one of the biggest claim-free discounts at 12%.
Top Home Insurance Discounts in Minnesota| Company | Bundling | New Home | No Claims | Security |
|---|---|---|---|---|
| 18% | 9% | 12% | 5% |
| 40% | 8% | 12% | 6% |
| 30% | 8% | 12% | 5% |
| 14% | 8% | 10% | 4% |
| 10% | 9% | 11% | 6% |
| 20% | 7% | 10% | 5% |
| 15% | 8% | 11% | 6% |
| 25% | 5% | 7% | 4% |
| 27% | 7% | 10% | 5% |
| 16% | 9% | 12% | 6% |
Insurance experts recommend asking your provider which discounts are available to you. You should also ask if you can reduce your premium by improving your home’s resistance to local risks.
You can also take advantage of bundling auto and home insurance discounts, which can lead to significant savings. The best bundling discounts can help you significantly lower your rates. Shop Now: Best Auto Insurance Companies in Minnesota
10 Best Home & Auto Insurance Bundle Discounts in Minnesota| Company | Rank | Discount | Savings | Bundle Rules |
|---|---|---|---|---|
| #1 | 40% | $1,051 | Same Account |
| #2 | 27% | $642 | Current Policy |
| #3 | 25% | $471 | Bundle Quote |
| #4 | 20% | $398 | Qualifying Policy |
| #5 | 18% | $428 | Online Bundle |
| #6 | 16% | $309 | Qualifying Home |
| #7 | 15% | $322 | Prior Policy |
| #8 | 14% | $314 | Local Agent |
 | #9 | 14% | $223 | Agent Required |
 | #10 | 14% | $220 | Members Only |
When comparing quotes, don’t assume that the insurer with the most advertised discounts will necessarily be the cheapest.
A company might offer more discounts but have a higher base premium. Ask each insurer for the final quote after applying all discounts you qualify for.
Other Ways to Save on Minnesota Home Insurance
Discounts aren’t the only way to lower your Minnesota homeowners insurance costs. You can also potentially save by changing your deductible, improving your home’s safety, and regularly comparing policies.
To show you how much a minor change can save you, take a look at how the amount you select for your deductible can change your monthly premiums.
Home Insurance Deductibles in Minnesota: Premium Impact| Category | $500 | $1K | $2K | $5K |
|---|---|---|---|---|
| Best Use | File Often | Less Often | Low Cost | Rare Claims |
| Claim Payout | Largest | High | Moderate | Smallest |
| Claim Rate | Highest | Moderate | Low | Lowest |
| Monthly Rate | $206 | $186 | $170 | $142 |
| Rate Stability | Lowest | Moderate | High | Highest |
You can lower your coverage cost by choosing the highest deductible possible. You also shouldn’t be afraid to switch insurance companies if you find a better rate elsewhere.
To help keep your homeowners insurance quotes in Minnesota as low as possible, you can also do the following.
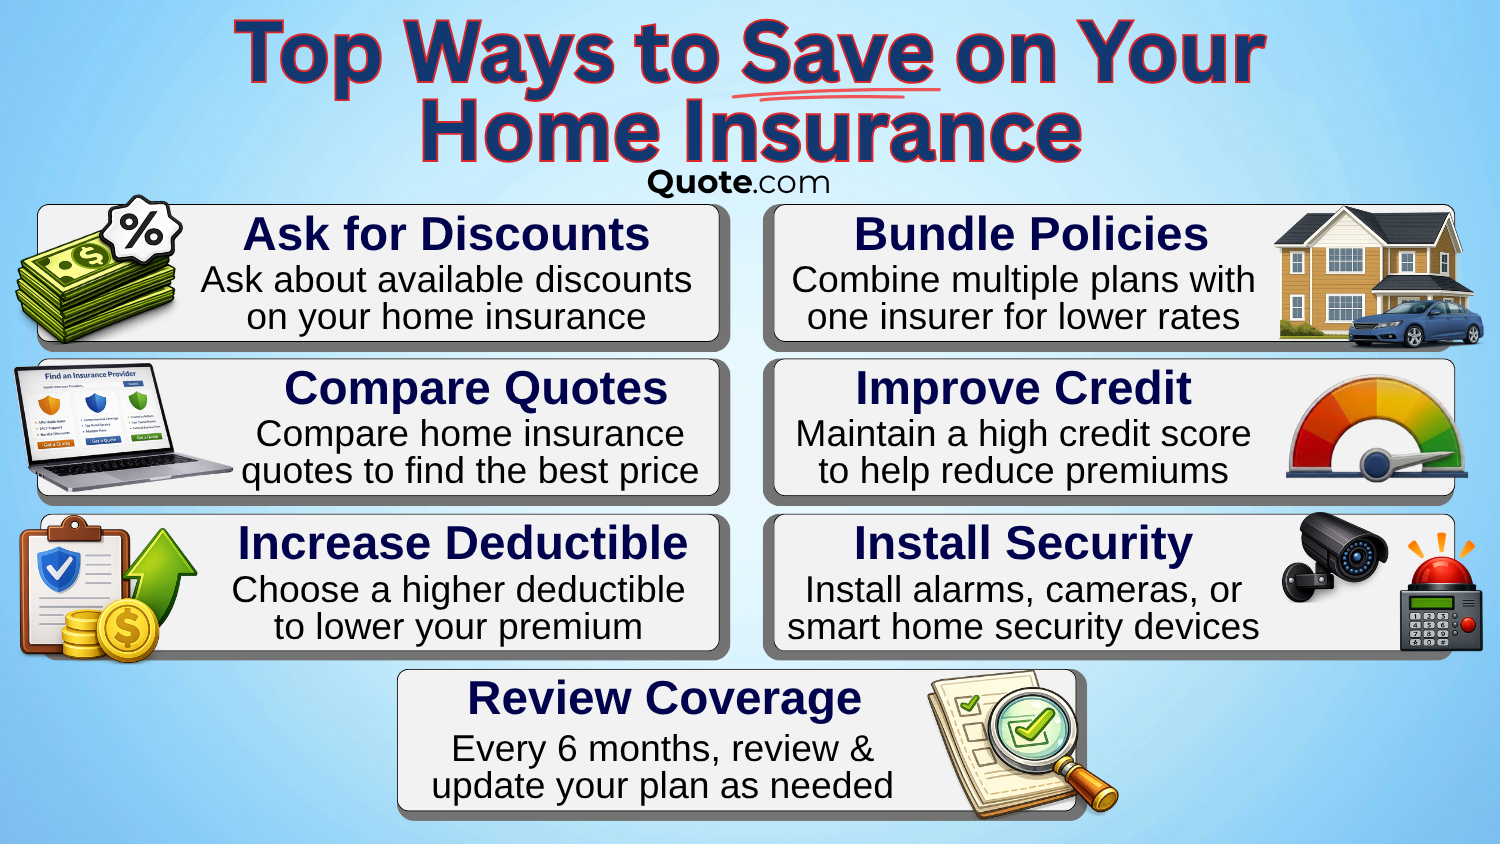
Don’t assume that your current insurer will always offer the lowest rate. Minnesota homeowners insurance prices can change as providers adjust rates based on local claim and weather trends.
Most importantly, don’t reduce coverage just to lower your premium. Instead, shop around online and compare quotes when your policy comes up for renewal. You may find savings with another company.
Top Home Insurance Companies in Minnesota
Finding the best home insurance in Minnesota starts with understanding what different insurers offer and how their policies fit your needs, rather than just looking at price.
Amica is our top overall pick for home insurance in Minnesota because it offers affordable rates, excellent customer service, and has great ratings from local homeowners.
10 Largest Home Insurance Companies in Minnesota| Company | Market Share | Policy Count | Premiums Written | Financial Rating |
|---|---|---|---|---|
| 26.3% | 332K | $1.1B | A+ |
| 15.5% | 178K | $623.3M | A |
| 8.6% | 116K | $348.2M | A+ |
| 7.7% | 115K | $309.9M | A |
 | 5.1% | 73K | $205.1M | A |
 | 4.4% | 71K | $177.2M | A++ |
| 4.3% | 64K | $173.2M | A++ |
| 4.1% | 53K | $164.7M | A+ |
| 2.5% | 36K | $100.3M | A |
| 2.1% | 34K | $82.2M | A |
Progressive and Travelers tend to have the cheapest homeowners insurance in Minnesota. However, the cheapest home insurance isn’t necessarily the best choice for you. Depending on your home, a slightly higher price may be worth it.
If you’re a new homeowner, Allstate might have the best resources for you. Or, if you have a luxury house, Chubb would likely be a better option.
Coverage costs can also vary significantly based on your home’s location, age, replacement cost, claims history, and the coverage limits and deductible you choose.
To help you get the perfect policy, we’ve researched the best homeowners insurance companies in Minnesota.
#1 – Amica: Top Pick Overall
Pros
- Customer Care: Amica insurance reviews focus on the company’s dedication to customer service excellence in Minnesota.
- Minnesota-Specific Discounts: You can get Amica home insurance discounts for things like temperature monitoring, which helps Minnesota residents save.
- Roof Replacement Coverage: Amica’s higher-tier home insurance options in Minnesota include replacement-cost roof coverage.
Cons
- Higher Rates: While Amica offers great customer service, it’s not the cheapest option in Minnesota.
- Exclusive Underwriting: Amica has strict underwriting restrictions, requiring Minnesota homeowners to have higher credit scores and a claim-free history.
#2 – Chubb: Best for Luxury Homes
Pros
- Luxury Home Coverage: Chubb offers the best coverage for high-value properties in Minnesota due to its focus on luxury homes and expensive properties.
- High Liability Limits: Minnesotans with high net worth can buy up to $100 million in Chubb liability coverage.
- Financial Strength: Chubb has an A++ rating from AM Best, meaning Minnesota residents can trust it will pay claims.
Cons
- Higher Rates: Since Chubb focuses on luxury homes, it doesn’t have the most affordable homeowners insurance in Minnesota.
- Limited Online Quotes: Most Minnesotans can’t buy a Chubb home insurance policy online without speaking to an agent.
#3 – Nationwide: Best Policy Add-on Options
Pros
- MN Weather Add-Ons: Minnesota homeowners have excellent add-on options from Nationwide, including better roof replacement and wind and hail coverage.
- High Dwelling Limits: Nationwide’s optional dwelling replacement cost coverage can provide up to twice the normal dwelling coverage.
- Flexible Payouts: If your home is a total loss, Nationwide lets you choose to either buy a new house elsewhere or rebuild.
Cons
- Higher Minnesota Rates: Nationwide insurance reviews in Minnesota report high rate spikes at renewal.
- Doesn’t Cover All Properties in MN: If you have a mobile or manufactured home in Minnesota, you won’t be able to buy coverage from Nationwide.
#4 – Progressive: Best for Bundling Policies
Pros
- Bundling Discounts: Progressive offers a wide array of discounts, but it’s particularly good for its bundling discount for home and auto insurance.
- Affordability: For Minnesota residents, Progressive is often one of the cheapest home insurance options.
- Digital Tools: Progressive’s HomeQuote Explorer makes it easy to explore Minnesota home insurance quotes and coverage options.
Cons
- Underwriter Partnerships: Progressive connects customers with a network of home insurance companies, so a different provider may write your policy.
- Pet Restrictions: According to Progressive insurance reviews, your application might be rejected if you have certain types of dog breeds living with you.
#5 – Travelers: Best for Green Homes
Pros
- Green Home Benefits: Travelers offers optional green home rebuild coverage, plus a 5% LEED discount. Travelers insurance reviews are happy with these coverage options.
- Flexible Coverage: Minnesota homeowners have several add-on options for their houses, including additional replacement and water backup protection.
- First Homeowner Friendly: Some providers charge higher rates if you’ve never had home coverage, but Travelers does not.
Cons
- Mixed Reviews: Travelers receives mixed customer satisfaction reviews for its home insurance service in Minnesota.
- ACV vs. Replacement Cost: Home insurance from Travelers automatically includes actual cash value instead of replacement cost coverage.
#6 – American Family: Best Selection of Discounts
Pros
- Discount Selection: American Family offers Minnesota homeowners many discounts to help keep premiums as low as possible.
- Equipment Breakdown: Minnesotans can add equipment breakdown coverage to protect against mechanical or electrical failures.
- Low Complaints: American Family insurance reviews are more positive than other companies of a similar size. Most Minnesota customers are satisfied with their service.
Cons
- Agent Required: You can get Minnesota homeowners insurance quotes online, but you’ll need to speak with an AmFam agent to buy a policy.
- Higher Rates: Although American Family offers many discounts, it usually doesn’t offer the lowest Minnesota home insurance rates.
#7 – Farmers: Best for Customizable Policies
Pros
- Customizable Policies: Farmers offers Minnesota homeowners coverage options designed to address common repair concerns, including matching materials.
- Many Ways to Save: Minnesotans have plenty of discount opportunities with Farmers, like being claims-free and bundling policies.
- High Customer Ratings: Farmers insurance reviews from Minnesota are predominantly positive about the service customers receive when they need help.
Cons
- Strict Underwriting: Depending on the age of your roof, Farmers might charge much higher rates for your Minnesota home.
- Creeping Price Hikes: While Farmers makes it easy to save on your initial premiums, many Minnesota homeowners report constant price hikes.
#8 – State Farm: Best for Local Agent Access
Pros
- Local Agents: State Farm is the largest homeowners insurance writer in Minnesota, giving homeowners access to a substantial local agent network.
- Inflation Protection: Your State Farm coverage in Minnesota automatically scales dwelling limits with local construction costs.
- No Banned Dogs: Unlike many Minnesota home insurance companies, State Farm doesn’t restrict coverage based on dog breed. Get More Details: State Farm Insurance Review
Cons
- Claims Issues: Many Minnesota homeowners express dissatisfaction with the speed and outcomes of State Farm’s claims process.
- Higher Average Rates: While State Farm is usually an affordable home insurance option, its rates in Minnesota tend to run a little higher.
#9 – Auto-Owners: Best for Affordable Rates
Pros
- Competitive Rates: No matter your home type or coverage needs, Auto-Owners typically has affordable rates in Minnesota.
- Unique Discounts: Auto-Owners offers Minnesota homeowners unique discounts, like for having a water shut-off system or a backup generator.
- Specialty Add-Ons: You’ll have the choice of many add-ons for MN home insurance policies when you shop at Auto-Owners, including an inland flood endorsement.
Cons
- No Online Quotes: If you want to buy a Minnesota Auto-Owners home insurance policy, you’ll have to speak with an agent.
- Lower Customer Ratings: According to J.D. Power, Auto-Owners insurance reviews often express dissatisfaction with this provider’s customer service.
#10 – Allstate: Best for New Homeowners
Pros
- New Homeowners Coverage: Allstate makes getting a first home insurance policy in Minnesota easy with its coverage options and helpful agents.
- Strong Minnesota Presence: Whether you want to buy new coverage or need to file a claim, Allstate has agents throughout Minnesota who are ready to help.
- Claim Forgiveness: Allstate’s Claim Forgiveness feature stops your premium from increasing after a claim. Find out how you can save: Allstate Insurance Review
Cons
- Higher Rates: While it’s not the most expensive option in Minnesota, Allstate typically doesn’t have the cheapest rates either.
- Claims Satisfaction: In Minnesota, Allstate’s home insurance claims reviews are mixed and often lean toward the lower side of the scale.
Free Home Insurance Comparison
Compare Quotes From Top Companies and Save
Get the Best Home Insurance in Minnesota Today
Choosing the best home insurance in Minnesota depends on more than finding the lowest premium. Amica is a great choice for homeowners who value great service and specialty home coverage. Alternatively, consider State Farm if you want the reassurance that an agent is almost always available.
Learning how to compare homeowners insurance quotes can help you find a balance between affordable rates and the protection your home needs. To get a good idea of the importance of comparing quotes, consider Progressive. It offers low rates in Minnesota but has strict pet breed restrictions.
Review your policy regularly and ask your insurer about available discounts, coverage updates, and ways to reduce your premium without leaving important gaps in protection.
To make sure you have the best home insurance in MN, you can compare home insurance prices with your ZIP code and see personalized quotes.
Frequently Asked Questions
What is the best home insurance company in Minnesota?
Companies such as Amica, Chubb, and Nationwide offer the best homeowners insurance in Minnesota, but home insurance premium costs, coverage options, discounts, and claims experiences vary by customer and property.
Who has the cheapest home insurance in MN?
The cheapest home insurance company depends on factors such as your home’s location, replacement cost, deductible, claims history, and coverage needs. Getting quotes from several insurers is more useful than choosing a company based on statewide averages alone.
How much should homeowners insurance cost in MN?
NerdWallet estimates that Minnesota homeowners pay about $2.2K per year, or $186 per month, for a policy with a $1,000 deductible. Your actual premium can be substantially higher or lower depending on your property and coverage choices.
Why is Minnesota home insurance so high?
Minnesota home insurance rates have increased substantially in recent years, with insurers citing factors such as rising storm-damage repair costs and higher rebuilding costs. Check out our guide to combat these higher rates: How to Compare Home Insurance Quotes
What factors affect home insurance rates in Minnesota?
Insurers can consider factors such as the amount of coverage you need, your deductible, claims history, the home’s characteristics, and protective features when determining premiums. Higher coverage limits cost more, while measures such as security systems, renovations, and higher deductibles may reduce rates. To see how your unique circumstances affect your premiums, enter your ZIP code into our tool today.
How much home insurance do you need in Minnesota?
There are no Minnesota home insurance requirements that you need to meet, but you might need to get coverage while you have a mortgage. Your dwelling coverage should be based on the estimated cost to rebuild your home, not its market value or what you paid for it. You should also consider adequate limits for personal property, living expenses, and liability protection.
Read More: Is home insurance required?
Does my credit score affect home insurance rates in Minnesota?
It can, because Minnesota permits insurers to use credit information or insurance scores as an underwriting factor for homeowners insurance. An insurer cannot reject, cancel, or nonrenew a homeowners policy based on credit information alone, and it must also consider other applicable underwriting factors.
Does homeowners insurance cover hail damage in Minnesota?
Hail damage may be covered if it results from a covered peril under your homeowners policy, but coverage and deductibles depend on your policy. Minnesota homeowners should check whether their policy has a separate wind or hail deductible and whether any exclusions or limitations apply. Compare coverages in our guide to find what you need: Homeowners vs. Hazard Insurance Coverage
Does homeowners insurance cover ice-dam damage in Minnesota?
Coverage for ice-dam damage depends on the circumstances of the loss and the specific policy, so Minnesota homeowners should review their policy rather than assume all ice-dam-related expenses are covered. In particular, damage resulting from a covered event may be treated differently from maintenance or ice-dam removal costs. Use our free quote tool to find the coverage you need.
Do I need flood insurance in Minnesota?
Standard homeowners insurance usually does not cover flood damage, so homeowners who want protection need a separate flood insurance policy. This can be relevant even outside Minnesota’s highest-risk flood zones because flooding can occur in many areas.
Related Articles
-
Aug 2026

Best Home Insurance in Maine for 2026
-
May 2026
Best Home Insurance Discounts in 2026: Save on Your Policy
-
Aug 2026
Best Home Insurance in Oregon for 2026
-
Oct 2025
Best Condo Insurance in 2026
-
Aug 2026
Best Home Insurance in South Dakota for 2026
-
Jul 2026
Homeowners Insurance Coverage in 2026
Get a FREE Quote in Minutes
Insurance rates change constantly — we help you stay ahead by making it easy to compare top options and save.