Best Home Insurance in Missouri for 2026
Amica, USAA, and The Hartford offer the best home insurance in Missouri, with rates starting at $69 per month. Missouri homeowners also enjoy a 40% bundle discount from American Family. Chubb can pay rebuilding costs above dwelling limits, while Liberty Mutual covers up to $12K in service line damage.
Read more
Table of Contents
Table of Contents
Social Media Manager & Professor
Ashley Dannelly has a Master of Arts in English and serves as the Social Media Manager for Quote.com's portfolio of websites. Ashley also teaches English at Columbia International University and other higher education institutions. Ashley’s background in English and media has allowed her the unique opportunity to edit and create content for many publications, including Livestrong and DiveIn....
Ashley Dannelly
Managing Editor
Aleksandra J. Churlinov holds a Bachelor of Arts in English Language and Literature and a Master of Science in Marketing Management. Over the past six years, Aleks has focused on the insurance sector, working on a range of content, including business, auto, and life insurance. In April 2025, she stepped into the role of Managing Editor, where she now leads a team of talented insurance writers. ...
Aleksandra J. Churlinov
Licensed Insurance Agent
Scott W Johnson is an independent insurance agent in California. Principal Broker and founder of Marindependent Insurance Services, Scott brings over 25 years of experience to his clients. His Five President’s Council awards prove he uses all he learned at Avocet, Sprint Nextel, and Farmers Insurance to the benefit of his clients. Scott quickly grasped the unique insurance requirements of his...
Scott W. Johnson
Updated September 2026
Amica, USAA, and The Hartford provide the best home insurance in Missouri, with annual rates starting at $828.
- Amica leads with the highest claims satisfaction score at 773 out of 1K
- Progressive saves $696 yearly when choosing a $5K deductible
- Missouri homeowners face tornado, hail, and severe wind risks
Amica covers eligible roof damage in Missouri at replacement cost so that depreciation won’t reduce the payout for a covered claim.
USAA gives eligible members up to 15% off after five claim-free years and covers military uniforms, so it’s worth checking out when shopping for the cheapest home insurance in Missouri.
Top 10 Companies: Best Home Insurance in Missouri| Company | Rank | Claims Satisfaction | Complaints | Best for |
|---|---|---|---|---|
 | #1 | 773 / 1,000 | Low | Claims Service |
 | #2 | 757 / 1,000 | Low | Military Families |
 | #3 | 756 / 1,000 | Mid | Senior Owners |
 | #4 | 744 / 1,000 | Low | Luxury Homes |
 | #5 | 722 / 1,000 | High | Systems Coverage |
 | #6 | 720 / 1,000 | Low | Roof Upgrades |
 | #7 | 704 / 1,000 | Mid | Online Comparison |
 | #8 | 700 / 1,000 | Low | Bundle Savings |
 | #9 | 700 / 1,000 | Low | Green Homes |
 | #10 | 691 / 1,000 | Mid | Deductible Rewards |
After three years with no claims, The Hartford reduces the property deductible for senior homeowners by $50, then reduces it by an additional $50 each year thereafter.
Enter your ZIP code to compare home insurance rates in Missouri and find coverage, deductibles, and discounts that fit your needs.
Missouri Home Insurance Premiums & Cost Factors
Missouri home insurance rates reflect storm exposure, roof age, rebuilding costs, and a homeowner’s claims history.
Tornadoes, hail, and strong winds can do serious damage to roofs, siding, and windows, especially during Missouri’s spring storm season.
Missouri’s average monthly rate climbed from $165 in 2021 to $255 in 2026, which is $90 more per month in five years.
An older roof can also push rates higher because worn shingles are more likely to need repairs or replacement after wind or hail damage. It’s worth taking the time to shop around, since insurers can price roof age, storm risk, deductibles, and claims differently.
How Much Insurance Coverage MO Homeowners Need
Higher home values can make a claim more expensive, so Missouri homeowners should look beyond the price they paid for the property.
Rebuilding may involve tearing out damaged materials, hauling debris, replacing wiring, and paying local contractors before the house is livable again.
Estimated Coverage, Costs, & Risk Levels in Missouri| Home Value | Coverage | Monthly Rate | Rebuild Costs | Risk Level |
|---|---|---|---|---|
| $200K | $218K | $205 | Low | Standard |
| $225K | $247K | $222 | Low | Standard |
| $250K | $271K | $238 | Moderate | Standard |
| $275K | $298K | $254 | Moderate | Elevated |
| $300K | $327K | $271 | Moderate | Elevated |
| $350K | $382K | $303 | High | Elevated |
| $400K | $438K | $336 | High | Substantial |
| $450K | $487K | $373 | Highest | Substantial |
| $500K | $548K | $409 | Highest | Substantial |
| $600K | $654K | $579 | Highest | Substantial |
Home improvements can also change how much coverage you need. Finishing a basement, remodeling your kitchen, or adding a bedroom can increase the cost of rebuilding your home.
Let your insurer know when you make major changes to your home. It’s also a good idea to update your dwelling limit so it reflects what your home would cost to rebuild today.
Ask about extended replacement coverage because it can provide extra protection when rebuilding costs go beyond your dwelling limit.
Jeff Root Licensed Insurance Agent
Once homeowners know how much dwelling coverage they need, the next step is seeing how the best home insurance companies price that same level of protection.
The average cost of home insurance in Missouri, at $255 a month, is a useful benchmark, but rates vary by coverage.
Missouri Home Insurance Monthly Rates by Dwelling Coverage| Company | $200K | $300K | $400K | $500K |
|---|---|---|---|---|
| $369 | $493 | $601 | $693 |
| $181 | $239 | $292 | $341 |
| $215 | $283 | $347 | $409 |
| $267 | $348 | $439 | $537 |
| $196 | $257 | $316 | $371 |
| $191 | $268 | $345 | $424 |
| $173 | $228 | $279 | $327 |
| $188 | $247 | $303 | $356 |
| $181 | $240 | $301 | $377 |
| $89 | $114 | $136 | $157 |
At $500K in coverage, choosing Progressive over American Family saves $4,392 each year while keeping the same limit.
USAA may offer some of the cheapest home insurance in Missouri, but eligibility excludes many homeowners. To see whether switching saves money, compare policies with equal coverage and deductibles.
Related: Dwelling Coverage for Homeowners
Choosing the Best Home Insurance Deductible in Missouri
Choosing a deductible means balancing what you can afford to pay after a claim with a reasonable monthly premium.
Moving from a $500 to a $5K deductible saves $696 yearly with Progressive, compared with $336 through USAA.
Missouri Home Insurance Monthly Rates by Deductible| Company | $500 | $1K | $2K | $5K |
|---|---|---|---|---|
| $401 | $369 | $334 | $282 |
| $198 | $181 | $164 | $139 |
| $232 | $215 | $196 | $169 |
| $292 | $267 | $241 | $205 |
| $214 | $196 | $178 | $151 |
| $207 | $191 | $174 | $146 |
| $190 | $173 | $157 | $132 |
| $204 | $188 | $171 | $144 |
| $199 | $181 | $163 | $137 |
| $97 | $89 | $81 | $69 |
A $5K deductible means you pay $4.5K more out of pocket than with a $500 deductible before insurance begins to cover the claim.
A $1K insurance deductible brings the monthly rate to $205, down from $223 with the $500 option for Missouri homeowners.
A $2K deductible brings the monthly rate down to $186, giving Missouri homeowners another option before moving up to a $5K deductible.
If $5K would be hard to cover after a claim, a lower deductible may be easier on your budget.
Home Insurance Deductibles in Missouri: Premium Impact| Category | $500 | $1K | $2K | $5K |
|---|---|---|---|---|
| Best Use | File Often | Less Often | Low Cost | Rare Claims |
| Claim Payout | Largest | High | Moderate | Smallest |
| Claim Rate | Highest | Moderate | Low | Lowest |
| Monthly Rate | $223 | $205 | $186 | $157 |
| Rate Stability | Lowest | Moderate | High | Highest |
It’s also worth checking your policy before choosing your coverage to see if separate wind or hail deductibles apply.
To see how different deductibles affect what you pay, compare quotes from insurers in Missouri.
How Location in Missouri Affects Your Home Insurance Premium
Where you live in Missouri can make a big difference in how much you pay for home insurance.
Looking at home insurance rates by state and county can help homebuyers understand whether a property sits in a more expensive area. Compare local rates for homeowners and mobile home insurance in Missouri since prices vary by location.
The $302 monthly gap between the lowest and highest county rates adds up to an extra $3,624 over a year, so check available rates in your area before deciding.
Even when home insurance is required by a mortgage lender, buyers can still shop among insurers instead of accepting the first policy offered.
Current homeowners looking for cheap home insurance in Missouri can compare rates using the same dwelling limit and deductible for a fair comparison.
USAA will often have the lowest Missouri home insurance rates. If you’re not in the military, Amica, Progressive, and Travelers are often the next most competitive, especially in areas at risk for tornadoes and hail damage. Shop Now: American Family vs. Travelers Insurance
Most Common Property Risks Facing Missouri Homeowners
Home insurance rates for properties with flooding risk range from $176 to $481 per month among the listed insurers.
Flooding risk has the highest monthly rate for eight of the 10 insurers listed. Must Know Facts: Best Insurance for High-Risk Homes
Missouri Home Insurance Monthly Rates by Risk Factor| Company | Earthquake | Flooding | Tornadoes | Wind & Hail |
|---|---|---|---|---|
| $394 | $481 | $458 | $438 |
| $198 | $286 | $220 | $210 |
| $237 | $341 | $270 | $253 |
| $294 | $389 | $345 | $322 |
| $216 | $311 | $247 | $231 |
| $209 | $297 | $234 | $223 |
| $190 | $272 | $216 | $205 |
| $207 | $296 | $230 | $221 |
| $199 | $284 | $226 | $212 |
| $98 | $176 | $110 | $104 |
Homes affected by tornadoes also face higher premiums, but the increase is usually less than what homeowners experience with flood risk.
While hazard insurance covers some weather damage, floods and earthquakes usually require separate coverage. Homeowners should also consider which hazards are most likely to result in a claim.
5 Most Common Home Insurance Risks in Missouri| Risk | Claims | Payout | Cost | Area |
|---|---|---|---|---|
| #1 Wind & Hail | 41% | $14K | High | Statewide |
| #2 Water & Freeze | 28% | $14K | High | North & Central |
| #3 Fire & Lightning | 21% | $84K | Highest | Rural Areas |
| #4 Falling Trees | 7% | $4K | Low | Ozarks |
| #5 Vandalism | 3% | $9K | Moderate | St. Louis & KC |
Among the common claims in Missouri, wind and hail make up 41%, so having enough money set aside for your deductible can make storm repairs easier. Although fire and lightning claims happen less often, the average loss is much higher at $84K.
Water and freeze damage account for 28% of claims, so fixing worn pipes can help prevent costly repairs. Knowing the common risks Missouri home insurance policies cover can also help you shop for coverage that fits your needs.
How Credit Score Affects Home Insurance in Missouri
Credit can affect how much homeowners pay for the same coverage, with weaker credit generally leading to higher premiums.
A lower insurance score can raise the price of a policy without changing the coverage or protection you receive.
Missouri Home Insurance Monthly Rates by Credit Score| Company | Excellent (800+) | Good (670-799) | Fair (580-669) | Poor (<580) |
|---|---|---|---|---|
| $369 | $442 | $583 | $842 |
| $181 | $218 | $288 | $421 |
| $215 | $251 | $322 | $449 |
| $267 | $333 | $461 | $712 |
| $196 | $239 | $320 | $478 |
| $191 | $231 | $306 | $451 |
| $173 | $214 | $294 | $442 |
| $188 | $226 | $299 | $431 |
| $181 | $220 | $291 | $426 |
| $89 | $104 | $132 | $184 |
When you renew or buy home insurance, take a quick look at your credit report for incorrect balances, unfamiliar accounts, or inaccurate late payments.
If you spot any errors, dispute them. If your credit has improved, ask for new quotes so insurers can use your updated credit information when setting your rate.
Free Home Insurance Comparison
Compare Quotes From Top Companies and Save
What Home Insurance Policies Cover in Missouri
Home insurance policies can offer different levels of protection depending on the coverage you choose.
It can also protect your belongings, cover liability, and help with extra living costs after a covered loss.
- Additional Living Expenses (ALE): Helps pay for temporary housing, meals, and other added costs if a covered loss makes your home unlivable.
- Dwelling Coverage: Helps pay to repair or rebuild your home after covered damage from fire, wind, hail, or other risks.
- Liability Coverage: Helps with legal costs and damages if someone gets hurt or you accidentally damage their property.
- Personal Property Coverage: Helps repair or replace things you own, like furniture, clothes, and electronics, after a covered loss.
Some Missouri risks may require additional coverage beyond these basic protections. Flood damage requires a separate flood insurance policy because standard homeowners insurance does not cover it.
Earthquake protection typically requires an endorsement or separate policy and can matter for homes near the New Madrid Seismic Zone. Sewer backup coverage usually requires an endorsement to cover eligible cleanup and property damage from sewer or drain backups.
Check how your policy handles matching siding. Replacing just one damaged section can leave the rest of your home looking off.
Michelle Robbins Licensed Insurance Agent
Keep a current home inventory to make sure your personal property limit covers what you own. Review your Missouri homeowners insurance coverage to understand your limits, deductibles, and what your policy will pay after a covered claim.
The policy form you choose also determines which causes of damage are covered. Some forms cover only listed risks, while broader forms cover more risks unless the policy excludes them.
- HO-2 Broad: Protects your home and belongings from 18 named risks, such as fire, theft, wind, hail, and vandalism.
- HO-3 Special: Protects your home from most risks unless excluded, but covers belongings only for risks specifically named in the policy.
- HO-5 Enhanced: Protects both your home and belongings from most risks unless the policy specifically excludes them.
- HO-6 Condo: Covers belongings, liability, and interior improvements the master policy may not cover. Condo owners should also check their policy for water damage coverage.
- HO-8 Modified: Designed for older homes when rebuilding costs are significantly higher than the home’s current market value.
HO-3 is the most common policy form in our Missouri data at 74% of all home policies reviewed.
Together, HO-3 and HO-5 account for 86% of policies included in our Missouri coverage data.
Wind and hail protection comes standard with most of the insurers shown, but how roof claims are paid can vary. Amica, Chubb, Travelers, and USAA offer replacement cost coverage for qualifying roofs.
Sewer backup coverage also varies by insurer. Chubb includes it, while American Family, Amica, Liberty Mutual, and USAA offer it as an add-on.
Home Insurance Coverage Options in Missouri| Company | Earthquake | Roof | Sewer | Wind & Hail |
|---|---|---|---|---|
| ➕Add-On | ⚠️Varies | ➕Add-On | ✅ |
| ➕Add-On | ✅RCV | ➕Add-On | ✅ |
| ➕Add-On | ✅RCV | ✅ | ✅ |
| ➕Add-On | ⚠️Varies | ⚠️Capped | ✅ |
| ➕Add-On | ➕Add-On | ➕Add-On | ✅ |
| ➕Add-On | ⚠️Varies | ⚠️Capped | ✅ |
| ⚠️Varies | ⚠️Varies | ⚠️Capped | ⚠️Varies |
| ➕Add-On | ➕Add-On | ⚠️Capped | ✅ |
| ➕Add-On | ✅RCV | ⚠️Capped | ⚠️by Age |
| ➕Add-On | ✅RCV | ➕Add-On | ✅ |
The difference between replacement cost and actual cash value can make a big difference in what you get after a covered claim.
Replacement cost generally pays what it costs to replace your property, while actual cash value takes depreciation out of the payout.
Roof, Inspection, and Flood Restrictions in Missouri
Missouri insurers have different rules for roof age, inspections, and flood coverage. These rules can affect whether a home qualifies for coverage and how much the insurer pays after a claim. Among the ranked companies, Amica and USAA stand out for allowing roofs up to 25 years old.
Liberty Mutual usually covers qualifying non-wood roofs at replacement cost until they turn 11. After that, it pays actual cash value, while wood roofs use actual cash value at any age.
Missouri Home Insurance Restrictions by Company| Company | Flood Zone | Inspection? | Roof Limit | Wildfire |
|---|---|---|---|---|
| ⚠️NFIP | ⚠️by Review | ⚠️Varies | ✅ |
| ⚠️Both | ⚠️by Age | 25 Yrs | ✅ |
| ⚠️Private | ⚠️by Value | 20 Yrs | ✅ |
| ⚠️NFIP | ⚠️by Age | ⚠️Varies | ✅ |
| ⚠️NFIP | ✅Exterior | ⚠️Varies | ✅ |
| ⚠️NFIP | ⚠️by Value | 15 Yrs | ✅ |
| ⚠️Private | ⚠️Capped | 20 Yrs | ⚠️Varies |
| ⚠️NFIP | ⚠️by Age | 20 Yrs | ✅ |
| ⚠️NFIP | ⚠️by Review | 15 Yrs | ✅ |
| ⚠️NFIP | ⚠️by Review | 25 Yrs | ✅ |
Travelers covers qualifying Missouri roofs up to 15 years old. How your roof claim is paid depends on the policy, so check whether replacement cost, actual cash value, or functional replacement cost applies.
When comparing the best home insurance companies in Missouri, it’s also worth looking at flood and inspection requirements. Chubb and Progressive list private flood insurance, while several other ranked insurers use the NFIP. Inspection rules can also depend on the home’s age, value, or condition.
Proven Ways to Save on MO Homeowners Insurance
Missouri insurers weigh factors like claims history, deductibles, home condition, and policy features differently when setting premiums.
Reviewing these factors at renewal can show where your current policy may be costing you more than necessary.
- Avoid Small Claims: If a repair costs just above your deductible, pay for it yourself to keep a minor claim off your record.
- Choose Deductibles Carefully: A higher deductible lowers your premium but means you’ll pay more if wind or hail damages your Missouri home.
- Compare Insurer Rates: Get quotes from several Missouri insurers at renewal to see if another company offers the same coverage limits for a lower premium.
- Maintain Older Systems: Repair worn roofs, aging plumbing, and outdated wiring before they cause damage or affect your policy renewal.
- Remove Unneeded Add-Ons: Review your policy and drop optional coverage for belongings, equipment, or home features you do not own anymore.
You can also look for home insurance discounts based on bundling, home age, security systems, and your claims history.
American Family offers the biggest bundling discount at 40% and up to 55% off for new homes.
Top Home Insurance Discounts in Missouri| Company | Bundling | New Home | No Claims | Security |
|---|---|---|---|---|
| 40% | 55% | 12% | 6% |
| 30% | 15% | 15% | 10% |
| 10% | 22% | 10% | 10% |
| 20% | 34% | 1% | 6% |
| 12% | 15% | 10% | 8% |
| 20% | 39% | 15% | 10% |
| 15% | 48% | 12% | 8% |
| 20% | 20% | 10% | 8% |
| 16% | 35% | 15% | 10% |
| 10% | 38% | 15% | 10% |
If you are shopping for home insurance for new construction, these discounts are worth comparing. Progressive offers 48% and Nationwide 39%.
You might qualify for more than one discount, but insurers have different rules for combining them. Check what you can stack to see how much you could save.
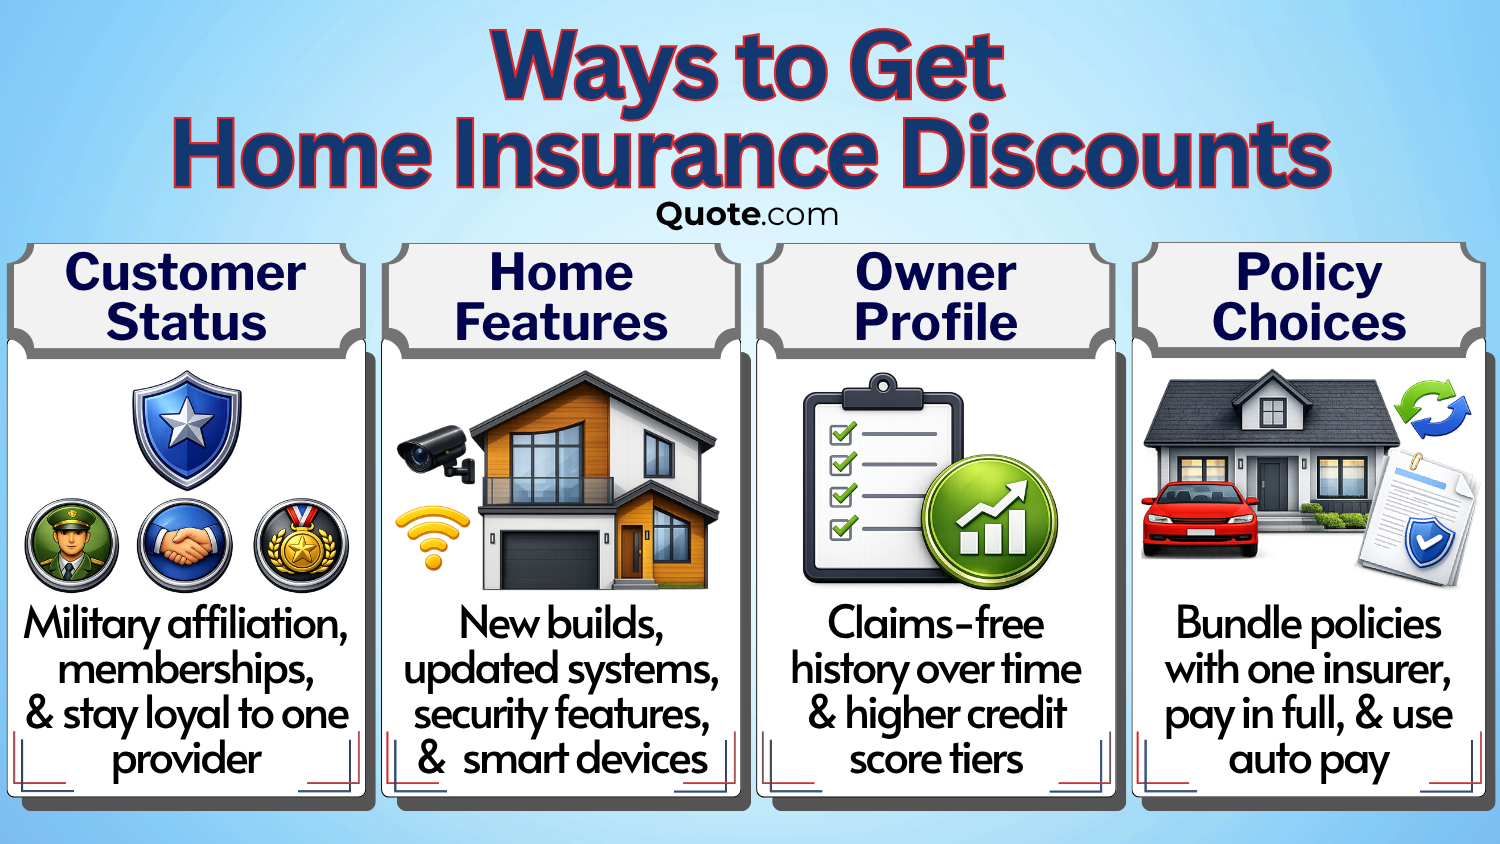
Making a few updates to your home could also help you save. A newer roof, updated plumbing or wiring, and qualifying security devices may help lower your rate.
After making major updates to your home, review your policy and check discounts to see if you qualify for new Missouri home insurance discounts.
Top Home and Car Insurance Savings in Missouri
Missouri homeowners should compare bundling discounts and the yearly cost of combined home and auto policies to see whether bundling actually saves money.
Before you switch to new policies, check your current coverage to see whether there are any cancellation charges or savings you’ll lose by changing insurers.
10 Best Home & Auto Insurance Bundle Discounts in Missouri| Company | Rank | Discount | Savings | Bundle Rules |
|---|---|---|---|---|
| #1 | 40% | $680 | Auto Customers |
 | #2 | 26% | $610 | Existing Policy |
 | #3 | 20% | $540 | Same Account |
 | #4 | 20% | $465 | Eligible Policies |
| #5 | 20% | $440 | Agent Signup |
 | #6 | 20% | $305 | Eligible Homes |
| #7 | 16% | $390 | Homeowners |
 | #8 | 13% | $330 | Member Only |
| #9 | 12% | $275 | Shared Address |
| #10 | 10% | $220 | Military Member |
A 40% bundling discount from American Family can make a bigger difference than smaller discounts, but homeowners should still compare the final combined premium.
State Farm’s $610 in savings shows why it’s worth checking the dollar amount, since a smaller discount can still save you quite a bit.
Ask if loyalty and bundle discounts work together. Some insurers may limit which discounts can be combined.
Melanie Musson Published Insurance Expert
Adding a teenage driver, buying another vehicle, or making a claim could affect what you pay for Missouri car insurance and your overall bundle when you renew.
Watch both renewal prices because an increase can erase your original savings. Compare quotes yearly to make sure your bundle remains competitive.
Explore Further: Best Auto Insurance Companies in Missouri
Top Missouri Homeowners Insurance Providers
State Farm and American Family are top home insurance companies in Missouri by market share, accounting for around 41% of the market.
State Farm has the largest Missouri market share at 24.8%, with 202K policies and $848.6M in written premiums. Get More Details: State Farm Insurance Review
American Family makes our Missouri ranking for its local agent network and up to 40% home-and-auto bundling savings.
10 Largest Home Insurance Companies in Missouri| Company | Market Share | Policy Count | Premiums Written | Financial Rating |
|---|---|---|---|---|
| 24.8% | 202K | $848.6M | A+ |
| 16.1% | 110K | $551.3M | A |
| 6.6% | 69K | $226.9M | A |
| 5.6% | 36K | $192.0M | A+ |
| 5.6% | 27K | $190.4M | A++ |
| 5.3% | 55K | $181.8M | A |
| 5.3% | 42K | $179.7M | A++ |
| 5.0% | 51K | $171.0M | A |
| 4.1% | 31K | $139.1M | A- |
| 3.0% | 29K | $101.4M | A+ |
USAA gives eligible military families up to 15% off after five claim-free years, while The Hartford reduces the property deductible after three claim-free years. Compare Missouri home insurance rates, coverage, and discounts to find better value.
Missouri homeowners learning how to get home insurance in Missouri can use the ultimate insurance cheat sheet to better understand coverage, exclusions, and policy terms.
#1 – Amica: Top Pick Overall
Pros
- Claims Satisfaction: Amica scores 773/1K for claims satisfaction, the highest of the insurers in our Missouri ranking.
- Bundle Savings: Amica offers up to 30% savings for bundling qualifying home and auto policies.
- Older Roofs: Amica may cover qualifying Missouri homes with roofs up to 25 years old.
Cons
- New-Home Discount: Qualifying new homes can get up to 15% off, but some insurers in our comparison offer bigger savings.
- Claim Forgiveness Cap: Amica’s home claim forgiveness covers eligible claims up to $5K, depending on the policy and state. Read More: Amica Insurance Review
#2 – USAA: Best for Military Families
Pros
- Military-Specific Coverage: Active-duty and Reserve members pay no deductible on covered losses involving military uniforms and equipment.
- Five-Year Claims-Free Savings: Eligible homeowners can save up to 15% after going at least five years without a homeowners or renters claim.
- Smart-Home Savings: Eligible members can receive up to 8% off for using qualifying devices that detect leaks, smoke, and other hazards.
Cons
- Restricted Eligibility: Our USAA insurance review shows coverage is limited to qualifying military members and family members, leaving many households ineligible.
- Bundle Discount: USAA’s listed 10% bundling discount ties Chubb for the lowest in this comparison.
#3 – The Hartford: Best for Senior Owners
Pros
- AARP Home Program: The Hartford offers an AARP home insurance program with benefits geared toward eligible members.
- Disappearing Deductible: Eligible homeowners can lower their property deductible after going three years without a loss.
- New-for-Old Coverage: Eligible homeowners can replace destroyed belongings with similar new items. Find Out More: The Hartford Insurance Review
Cons
- AARP Eligibility: Some Hartford rates and benefits require AARP membership, so homeowners who don’t qualify may miss out.
- 20-Year Roof Limit: The Hartford covers qualifying Missouri roofs up to 20 years old, so owners of older roofs may have limited options.
#4 – Chubb: Best for Luxury Homes
Pros
- Rebuilding Protection: Chubb can help rebuild a qualifying home even if the cost goes over the policy limit.
- Cash Settlement Option: Eligible homeowners can take a cash payout up to the policy limit after a covered total loss instead of rebuilding.
- HomeScan Loss Prevention: Chubb uses infrared technology to identify hidden leaks, insulation gaps, and electrical issues before they become bigger problems.
Cons
- High-Value Focus: Chubb focuses its homeowners coverage on high-value properties, so it may not fit homeowners looking for a standard policy.
- 20-Year Roof Limit: Chubb covers qualifying Missouri roofs up to 20 years old, so older roofs may have fewer coverage options.
#5 – Liberty Mutual: Best for Systems Coverage
Pros
- Systems Coverage: Eligible homeowners can add up to $50K in coverage for home system and appliance breakdowns, with a $500 deductible.
- Service Line Coverage: Liberty Mutual offers up to $12K for eligible service line damage. Read More: Liberty Mutual Insurance Review
- Inflation Protection: Your coverage limits can adjust as costs go up, and you may get a discount for adding this protection.
Cons
- Water Backup Add-On: You’ll need extra coverage for protection from sewer or sump-pump backups.
- Older Roof Payouts: Liberty Mutual uses actual cash value for qualifying Missouri roofs once they reach 11 years old, so depreciation can lower the payout after a covered claim.
#6 – Nationwide: Best for Roof Upgrades
Pros
- Stronger Roofs: Better Roof Replacement can help pay for stronger materials when a qualifying roof needs to be replaced.
- Bundle Savings: You can save up to 20% by combining eligible home and auto policies with Nationwide.
- Belongings Replacement: Brand New Belongings helps replace possessions without depreciation. Find Out More: Nationwide Insurance Review
Cons
- Optional Features: Brand New Belongings and Better Roof Replacement cost extra because they must be added to the policy.
- 15-Year Roof Limit: Nationwide covers qualifying Missouri roofs up to 15 years old, while five of the 10 insurers listed show roof limits of 20–25 years.
#7 – Progressive: Best for Online Comparison
Pros
- Online Comparison: HomeQuote Explorer lets homeowners compare rates and coverage from multiple insurers online.
- Property Data Fill: HomeQuote Explorer pulls details like roof type and square footage from public records, so homeowners enter less information.
- One-Deductible Benefit: Eligible customers may pay one deductible when the same covered event damages both their home and vehicle.
Cons
- Smaller Discount: Our Progressive insurance review shows a 15% home bundling discount, compared with 20% or more from some insurers.
- Different Underwriters: Progressive home policies may come from different insurers, so the company handling coverage and claims may differ.
#8 – American Family: Best for Bundle Savings
Pros
- Bundle Discount: American Family offers up to 40% savings for bundling qualifying home and auto policies. What to Know: American Family Insurance Review
- New Home Savings: Qualifying newer homes can get up to 55% off, the highest new-home discount in our comparison.
- Equipment Protection: Homeowners can add coverage for appliances, home systems, and smart devices if they suddenly break down.
Cons
- Breakdown Deductible: Equipment Breakdown coverage comes with a $500 deductible, so smaller repair or replacement claims may not be worth filing.
- Older Roof Limits: AmFam doesn’t offer replacement cost coverage for Missouri shingle roofs over 15 years old, while some tile and metal roofs can qualify for up to 30 years.
#9 – Travelers: Best for Green Homes
Pros
- LEED Home Savings: Travelers offers up to 5% off for qualifying LEED-certified homes.
- Early Quote Savings: Our Travelers insurance review shows customers can save up to 10% when they get coverage before their policy starts.
- Homebuyer Savings: Customers who bought their home within the past 12 months may qualify for an additional discount.
Cons
- LEED Required: Energy-efficient upgrades alone may not qualify for the green-home discount because Travelers requires LEED certification.
- 15-Year Roof Limit: Travelers shows a 15-year roof limit for qualifying Missouri roofs, while several insurers show limits of 20–25 years.
#10 – Farmers: Best for Deductible Rewards
Pros
- Lower Deductible: Policyholders can earn $50 toward their deductible each year they keep their Farmers policy. Learn More: Farmers Insurance Review
- Claims-Free Savings: Farmers offers a discount after three claim-free years, including qualifying years with a previous insurer.
- Bundle Savings: Farmers offers up to 20% savings for bundling eligible home and auto policies.
Cons
- Five-Year Wait: You’ll need five claim-free years before you can get Farmers’ claim forgiveness.
- Roof Depreciation: Farmers may pay actual cash value for older or worn Missouri roofs, which can lower your claim payout.
Free Home Insurance Comparison
Compare Quotes From Top Companies and Save
Getting the Best Home Insurance in Missouri
Finding the best home insurance in Missouri means comparing home insurance premiums, rebuilding costs, exclusions, deductibles, and coverage for the risks your home may face.
Amica’s Platinum Choice can give you extra dwelling coverage if rebuilding your home ends up costing more than your policy limit.
USAA gives eligible military households replacement-cost coverage for belongings, so depreciation won’t reduce what they receive for covered items.
The Hartford offers optional coverage of up to $500 to replace your locks if you lose a house key or have it stolen.
Compare claims satisfaction scores and complaint levels before choosing an insurer. They can give you a better idea of what to expect when you file a claim.
Luke Williams Insurance and Finance Writer
Homeowners should also check their limits for detached buildings, valuable items, temporary housing, and renovations, especially after making major home improvements.
Once you’ve checked those details, compare Missouri home insurance quotes from affordable home insurers in Missouri to find coverage and rates that work for your home and budget.
Frequently Asked Questions
Which home insurance company is best in Missouri?
Amica ranks first for home insurance in Missouri in our comparison. It stands out for strong claims service and flexible coverage. USAA is a good option for eligible military families, while The Hartford offers benefits for AARP members.
What is the average cost of homeowners insurance in Missouri?
Missouri homeowners pay about $255 per month on average based on our statewide data. Your rate can be higher or lower depending on your home, location, deductible, claims history, and coverage. Learn More: How Roof Inspections Affect Home Insurance Costs
Who has the cheapest home insurance in Missouri?
USAA is the cheapest in our comparison, starting at $69 per month with a $5K deductible. Progressive is next at $132 per month with the same deductible and is available to homeowners who don’t qualify for USAA.
Shop around for Missouri home insurance to find coverage that fits your home and budget.
Is homeowners insurance required by law in Missouri?
No. Missouri law doesn’t require homeowners insurance, but your mortgage lender may require coverage while you have a loan. When comparing types of home insurance, check what your lender requires and choose coverage that fits your home and needs.
What homeowners insurance coverage is recommended in Missouri?
Missouri homeowners should consider dwelling, personal property, liability, and additional living expenses coverage. Wind and hail coverage is also worth having because severe storms can cause costly home damage.
What factors affect homeowners insurance rates in Missouri?
Your home’s rebuilding cost, location, roof age, claims history, coverage limits, and deductible affect your Missouri home insurance rate. If your premium goes up, you may want to switch homeowners insurance after comparing rates and coverage.
How do I estimate the cost of Missouri homeowners insurance?
Start with the home’s rebuilding cost, then compare quotes with the same coverage and deductible. Things like location, roof age, and claims history can change the price.
Use our free quote comparison tool to find affordable Missouri homeowners insurance rates.
Why is homeowners insurance so expensive in Missouri?
Severe storms, tornadoes, wind, and hail can raise Missouri insurance costs by causing expensive property claims. Rising labor and material costs also make covered repairs more expensive.
How can I make my Missouri home insurance cheaper?
Compare rates and discounts from different insurers using insurance comparison sites. Raising your deductible, bundling policies, or making home improvements may also lower your rate.
Should I bundle my Missouri home and auto insurance?
Bundling can make sense if it lowers the total cost of both policies. Check the final price and coverage to make sure the savings are worthwhile. Enter your ZIP code to find the best home insurance options available in Missouri.
Does homeowners insurance cover water damage in Missouri?
Does homeowners insurance cover earthquakes in Missouri?
Which Missouri home insurance company has the most complaints?
Which Missouri insurance company denies most claims?
Is $200 a month a lot for Missouri home insurance?
How much is insurance on a $400K Missouri house?
How much is homeowners insurance on a $500K Missouri house?
What should I not say to a Missouri home insurance claim adjuster?
Get a FREE Quote in Minutes
Insurance rates change constantly — we help you stay ahead by making it easy to compare top options and save.