Best Home Insurance in Montana for 2026
The best home insurance in Montana comes from Amica, Chubb, and Liberty Mutual, with strong claims service, luxury-home coverage, and policy discounts. MT homeowners insurance rates start at $147 a month with a $5K deductible. Montana homeowners should review wildfire and winter storm protection.
Read more
Table of Contents
Table of Contents
Insurance Copywriter
Rachel Bodine graduated from college with a BA in English. She has since worked as a Feature Writer in the insurance industry and gained a deep knowledge of state and countrywide insurance laws and rates. Her research and writing focus on helping readers understand their insurance coverage and how to find savings. Her expert advice on insurance has been featured on sites like PhotoEnforced, AllWom...
Rachel Bodine
Managing Editor
Daniel S. Young began his professional career as chief editor of The Chanticleer, a Jacksonville State University newspaper. He also contributed to The Anniston Star, a local newspaper in Alabama. Daniel holds a BA in Communication and is pursuing an MA in Journalism & Media Studies at the University of Alabama. With a strong desire to help others protect their investments, Daniel has writt...
Daniel S. Young
Licensed Insurance Agent
Michelle Robbins has been a licensed insurance agent for over 13 years. Her career began in the real estate industry, supporting local realtors with Title Insurance. After several years, Michelle shifted to real estate home warranty insurance, where she managed a territory of over 100 miles of real estate professionals. Later, Agent Robbins obtained more licensing and experience serving families a...
Michelle Robbins
Updated September 2026
Amica is our top pick for the best home insurance in Montana, while Chubb stands out for luxury properties, and Liberty Mutual offers savings through several policy discounts.
- Home and auto bundle discounts reach up to 40% in Montana
- Wildfire claims average $110K, the highest payout among listed risks
- You can get cheaper MT home insurance rates with a higher deductible
Among the top-ranked providers, State Farm has the lowest rate for $200K in dwelling coverage at $185 a month, compared to Amica at $218 monthly.
Rates vary by coverage level, deductible, credit, and property details, so homeowners should review more than the starting price when choosing a policy.
Top 10 Companies: Best Home Insurance in Montana| Company | Rank | Claims Satisfaction | Complaints | Best for |
|---|---|---|---|---|
 | #1 | 773 / 1,000 | Low | Customer Care |
 | #2 | 744 / 1,000 | Low | Luxury Homes |
 | #3 | 722 / 1,000 | High | Policy Discounts |
 | #4 | 720 / 1,000 | High | Security Savings |
 | #5 | 704 / 1,000 | Low | Online Quotes |
 | #6 | 700 / 1,000 | Low | Safety Features |
 | #7 | 691 / 1,000 | Low | Custom Policies |
 | #8 | 690 / 1,000 | Mid | Local Agents |
 | #9 | 672 / 1,000 | High | New Homes |
 | #10 | 666 / 1,000 | Mid | Digital Tools |
Montana premiums are also impacted by your location and the exposure to wildfire, hail, and severe winter weather. Review how much homeowners insurance you need to choose coverage that matches your home’s value and rebuilding costs.
You may find a better home insurance price by comparison shopping online. Check homeowners insurance costs from multiple providers.
Montana Home Insurance Costs Over Time
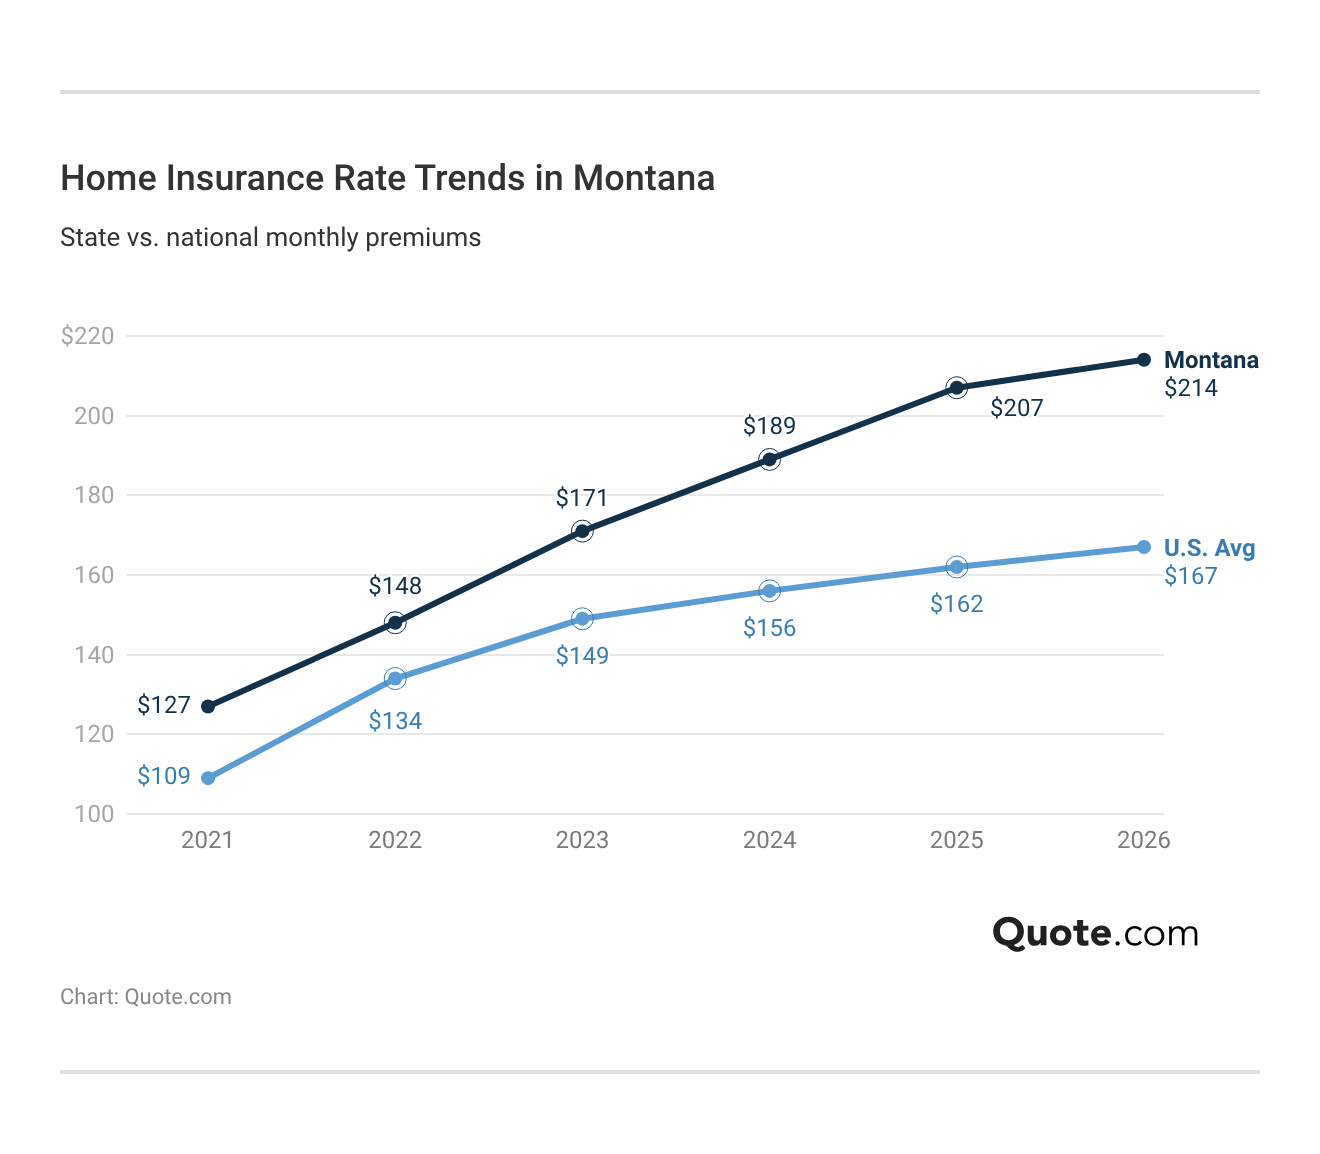
The average cost of home insurance in Montana has climbed from $127 per month in 2021 to $214 in 2026, rising much faster than the national average.
Montana home insurance rates continue to rise as rebuilding costs increase. Higher construction and labor costs make covered repairs more expensive.
Homes face greater risks from severe weather and natural disasters in Montana than other states, and wildfire, hail, and winter storm claims can drive up rates.
State-by-state home insurance rates can help homeowners see how local premiums differ from costs elsewhere in the country.
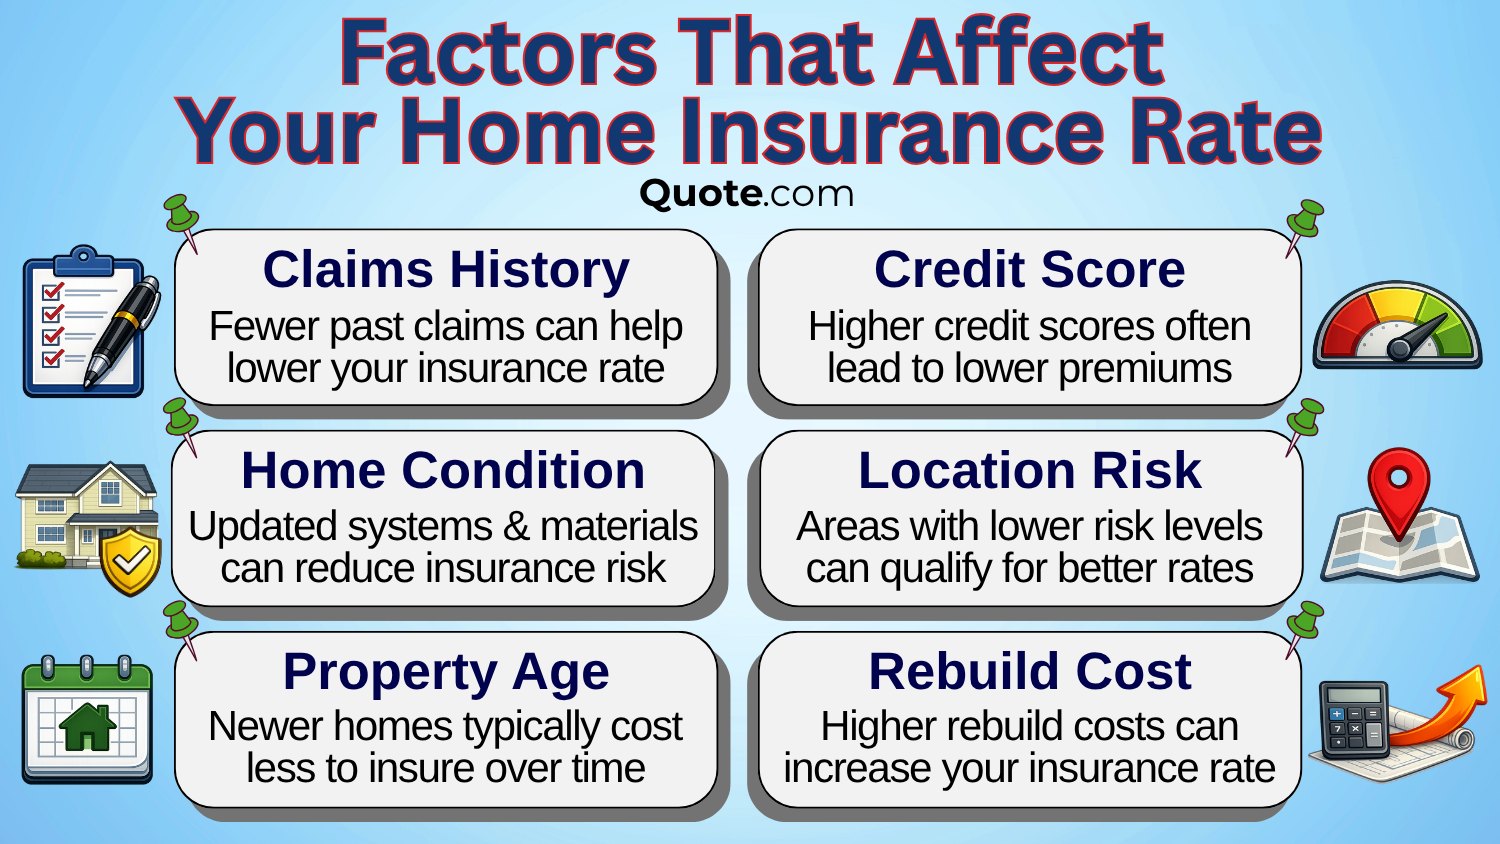
Coverage limits, policy deductibles, and credit scores also affect what Montana homeowners pay.
Find out how to get the best rate in Montana by reviewing several insurers, since premiums vary with each provider.
How Dwelling Coverage Changes What You Pay
If you’re wondering how much homeowners insurance you need in Montana, start with estimated rebuilding costs. Review quotes using the same dwelling limit and deductible for a more accurate price comparison.
Dwelling coverage helps pay to repair or rebuild the physical structure of your home after a covered loss, so choosing enough dwelling coverage matters.
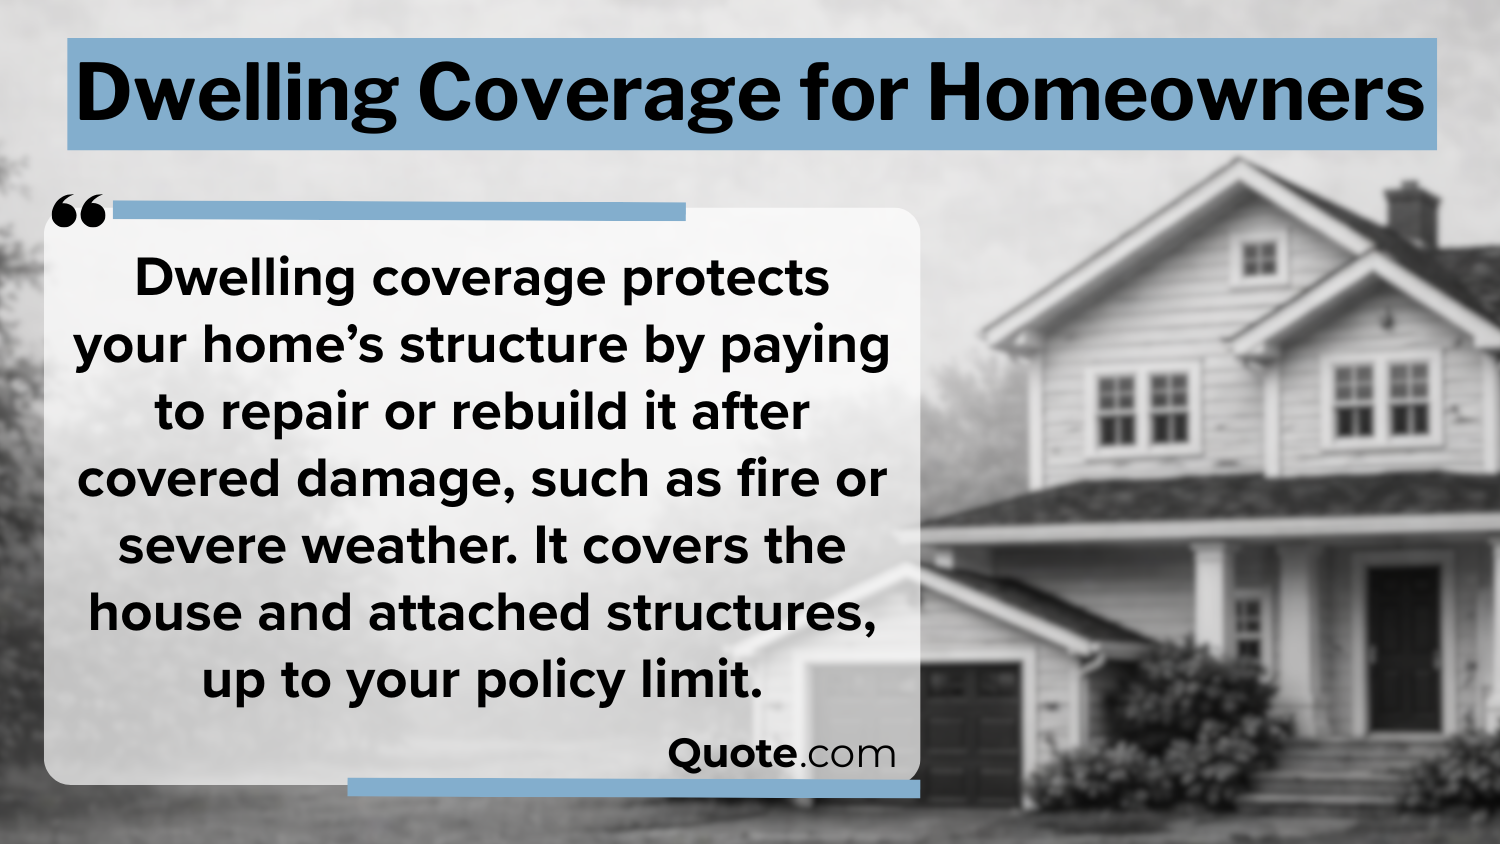
An insufficient policy limit could leave you responsible for part of the repair or rebuilding bills after a major loss.
Understanding this part of a homeowners policy makes it easier to evaluate the $200K to $500K coverage levels used in the rate comparison.
Montana Home Insurance Monthly Rates by Dwelling Coverage| Company | $200K | $300K | $400K | $500K |
|---|---|---|---|---|
| $211 | $263 | $311 | $358 |
| $218 | $276 | $329 | $381 |
| $246 | $322 | $397 | $469 |
| $244 | $338 | $432 | $521 |
| $226 | $289 | $347 | $404 |
| $205 | $281 | $354 | $426 |
| $198 | $258 | $316 | $371 |
| $215 | $274 | $334 | $392 |
| $185 | $233 | $276 | $323 |
| $193 | $247 | $292 | $337 |
State Farm has the lowest monthly rates at every dwelling coverage level shown, starting at $185 for $200K in coverage and increasing to $323 for $500K.
Travelers is the next-cheapest option across all four coverage levels, with rates from $193 to $337 per month, while Progressive ranges from $198 to $371 monthly.
Montana homeowners should insure their home for its rebuilding cost, choose an affordable deductible, and check coverage for wildfire, hail, and winter storms.
Jeff Root Licensed Insurance Agent
The price differences become more noticeable as coverage increases, with Farmers charging the highest $500K rate at $521 per month, which is $198 more than State Farm.
Compare the best homeowners insurance rates in Montana using the same dwelling limit to see how prices differ in your neighborhood.
How Property Value Affects Your Montana Coverage Needs
Higher-value homes in Montana usually need more dwelling coverage. A $200K home costs about $214 per month with $218K in coverage, compared with $339 monthly for a $400K home with $462K in coverage.
Rebuild costs rise with home values, so Montana homeowners should base coverage on reconstruction costs, not market value.
Estimated Coverage, Costs, & Risk Levels in Montana| Home Value | Coverage | Monthly Rate | Rebuild Costs | Risk Level |
|---|---|---|---|---|
| $200K | $218K | $214 | Low | Standard |
| $225K | $247K | $230 | Low | Standard |
| $250K | $286K | $247 | Moderate | Standard |
| $275K | $312K | $263 | Moderate | Elevated |
| $300K | $338K | $278 | Moderate | Elevated |
| $350K | $397K | $309 | High | Elevated |
| $400K | $462K | $339 | High | Substantial |
| $450K | $514K | $368 | High | Substantial |
| $500K | $572K | $398 | Extreme | Substantial |
| $600K | $684K | $458 | Extreme | Substantial |
A $600K home carries about $684K in coverage with a $458 monthly rate, more than double the premium shown for a $200K property.
The cost of home insurance also depends on the type of home you’re insuring and the deductible you choose with the policy.
Comparing Home Insurance Costs by Deductible
Montana homeowners can lower their monthly premium by choosing a higher insurance deductible.
The average monthly rate falls from $235 with a $500 deductible to $214 at $1K, $193 at $2K, and $167 at $5K.
Montana Home Insurance Monthly Rates by Deductible| Company | $500 | $1K | $2K | $5K |
|---|---|---|---|---|
| $232 | $211 | $192 | $167 |
| $235 | $218 | $197 | $174 |
| $272 | $246 | $221 | $193 |
| $268 | $244 | $215 | $186 |
| $247 | $226 | $205 | $178 |
| $225 | $205 | $183 | $158 |
| $217 | $198 | $181 | $156 |
| $236 | $215 | $192 | $166 |
| $202 | $185 | $170 | $147 |
| $211 | $193 | $173 | $149 |
State Farm has the lowest rate at each deductible shown, including $147 per month with a $5K deductible. Travelers is close behind at $149 a month, while the other insurers remain above $150 per month.
The lower premium comes with more out-of-pocket responsibility, since the policyholder must cover the larger deductible before insurance pays an eligible claim.
Home Insurance Deductibles in Montana: Premium Impact| Category | $500 | $1K | $2K | $5K |
|---|---|---|---|---|
| Best Use | File Often | Less Often | Low Cost | Rare Claims |
| Claim Payout | Largest | High | Moderate | Smallest |
| Claim Rate | Highest | Moderate | Low | Lowest |
| Monthly Rate | $235 | $214 | $193 | $167 |
| Rate Stability | Lowest | Moderate | High | Highest |
However, that difference should be weighed against the additional amount you would have to pay toward repairs after a covered loss.
When you shop for home insurance in Montana, consider how much you could comfortably pay after a claim.
Insurance Costs for Higher-Risk Properties in Montana
Property risks can affect what Montana homeowners pay for insurance, and wildfire produces the highest monthly rates for every company shown.
State Farm has the lowest prices across all four risk categories, ranging from $199 per month for lightning risk to $269 monthly for wildfire, while Travelers follows at $209 and $281 monthly.
Montana Home Insurance Monthly Rates by Risk Factor| Company | Lightning | Wildfire | Wind & Hail | Winter Storm |
|---|---|---|---|---|
| $227 | $306 | $273 | $249 |
| $233 | $315 | $281 | $258 |
| $265 | $346 | $309 | $286 |
| $263 | $356 | $319 | $293 |
| $241 | $331 | $291 | $269 |
| $220 | $299 | $266 | $243 |
| $216 | $288 | $259 | $235 |
| $232 | $318 | $278 | $257 |
| $199 | $269 | $241 | $219 |
| $209 | $281 | $250 | $228 |
Farmers has the highest wildfire rate at $356 per month and the highest wind and hail rate at $319. Home insurance coverage for wildfires costs $87 more per month with Farmers than State Farm.
When you review your natural-disaster coverage options in Montana, check each insurer’s limits and restrictions for wildfire, wind and hail, winter storms, flooding, and earthquakes.
What Montana Homeowners Pay by Credit Score
Credit has a noticeable effect on home insurance premiums, with rates increasing as credit scores decline. Montana homeowners with fair or poor credit may find especially large price differences when comparing the same coverage and deductible across companies.
State Farm has the lowest monthly rate across all four credit tiers, ranging from $185 with excellent credit to $369 with poor credit.
Montana Home Insurance Monthly Rates by Credit Score| Company | Excellent (800+) | Good (670-799) | Fair (580-669) | Poor (<580) |
|---|---|---|---|---|
| $211 | $244 | $301 | $416 |
| $218 | $248 | $296 | $382 |
| $246 | $276 | $329 | $421 |
| $244 | $286 | $362 | $500 |
| $226 | $264 | $329 | $445 |
| $205 | $241 | $308 | $430 |
| $198 | $234 | $295 | $407 |
| $215 | $251 | $316 | $432 |
| $185 | $216 | $270 | $369 |
| $193 | $224 | $278 | $375 |
Travelers follows at $193 per month for excellent credit and $375 for poor credit, while Farmers shows the highest poor-credit rate at $500 per month.
For Farmers, that is $256 more each month than its rate for excellent credit, adding up to $3,072 over a year.
Choosing a higher deductible may lower your monthly premium, but make sure you could afford that amount if you need to file a claim.
Melanie Musson Published Insurance Expert
Your Montana home insurance premiums will go down as you work to improve your credit score.
In the meantime, save money by checking rates from several insurers, since credit affects each company’s pricing differently.
How Home Insurance Costs Vary Across Montana
Montana homeowners insurance rates by city and county range from about $151 to $538 per month, showing how much location can affect premiums.
Many western Montana counties have lower premiums, while several eastern counties cost more. Weather, rebuilding costs, property risks, and local claims can all affect rates.
To find Montana home insurance that reflects local pricing, check rates for your ZIP code rather than relying only on the statewide average, especially with a $387 monthly spread between the lowest and highest county rates shown.
Compare home insurance quotes using the same coverage and deductible to see quotes from local companies that offer similar protection.
Free Home Insurance Comparison
Compare Quotes From Top Companies and Save
Finding Lower Home Insurance Rates in Montana
Bundling the best home and auto insurance in Montana is a great way to save money. Amica, the top homeowners insurance provider overall in the ranking, offers a 30% bundle discount with estimated savings of $785 a year.
American Family has the largest bundle discount shown at 40%, with estimated annual savings of $1,051.
10 Best Home & Auto Insurance Bundle Discounts in Montana| Company | Rank | Discount | Savings | Bundle Rules |
|---|---|---|---|---|
 | #1 | 40% | $1,051 | Auto Customers |
| #2 | 30% | $785 | Direct Writer |
| #3 | 26% | $577 | Current Policy |
| #4 | 25% | $594 | Bundle Quote |
| #5 | 20% | $586 | Qualifying Policy |
| #6 | 20% | $506 | Online Bundle |
 | #7 | 18% | $443 | Local Agent |
 | #8 | 18% | $486 | Agent Quote |
| #9 | 16% | $371 | Qualifying Home |
| #10 | 13% | $320 | Prior Policy |
State Farm offers a 26% discount worth $577 per year, while Progressive offers 25% with higher estimated savings of $594 annually.
Before bundling home and auto insurance, compare the combined price with the cost of buying each policy separately, since bundle discounts and eligibility rules vary by insurer. The final dollar savings matter more than the discount percentage alone.
More Montana Home Insurance Savings Tips
Montana homeowners have several ways to reduce their premiums. The best home insurance discounts in MT include savings for remaining claims-free, newer homes, and qualifying security features.
Savings for remaining claims-free reach 12% with Allstate, Amica, and Travelers, while Allstate, Chubb, and Travelers offer the highest new-home discount shown at 9%.
Top Home Insurance Discounts in Montana| Company | Bundling | New Home | No Claims | Security |
|---|---|---|---|---|
| 20% | 9% | 12% | 5% |
| 30% | 8% | 12% | 5% |
| 10% | 9% | 11% | 6% |
| 20% | 7% | 10% | 5% |
| 12% | 6% | 9% | 4% |
| 13% | 8% | 11% | 6% |
| 25% | 5% | 7% | 4% |
| 19% | 5% | 11% | 10% |
| 26% | 7% | 10% | 5% |
| 16% | 9% | 12% | 6% |
Safeco stands out for home security savings at 10%, compared with 4% to 6% from the other insurers.
Along with discounts, review coverage options, claims service, restrictions, and the final premium to get better value on the best homeowners insurance in Montana.
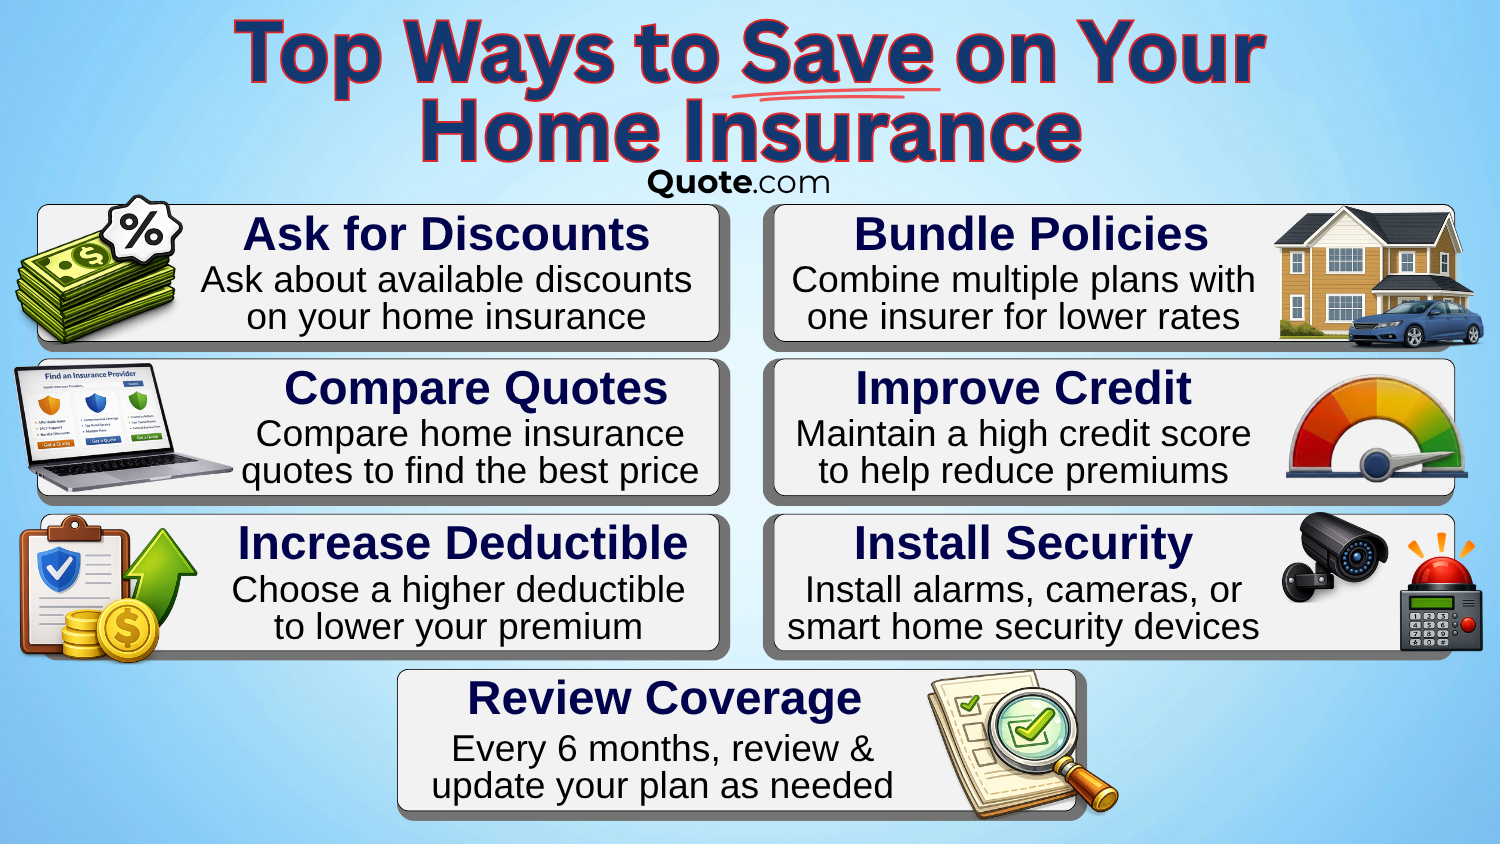
Before making changes, check how each discount or coverage adjustment affects the amount you would pay after a loss.
A lower premium may come with a higher deductible or different coverage limits, so compare the savings with any increase in out-of-pocket costs before changing your policy.
Get More Details: How to Switch Homeowners Insurance
Policies Montana Homeowners Need
Shoppers asking whether Montana requires homeowners insurance should separate legal requirements from lender requirements, then check for the protection needed for risks common to their location.
Review what homeowners insurance covers for wildfire, wind and hail, sewer backups, winter weather, and earthquakes, including any coverage that requires an endorsement or separate policy.
Home Insurance Coverage Options in Montana| Company | Flood | Sewer | Wildfire | Wind & Hail |
|---|---|---|---|---|
| ✅Both | ➕Add-On | ⚠️Limited | ➕Add-On |
| ⚠️NFIP | ➕ Add-On | ✅ | ✅ |
| ⚠️Private | ⚠️ Capped | ✅ | ✅ |
| ⚠️NFIP | ➕ Add-On | ✅ | ✅ |
| ⚠️NFIP | ➕ Add-On | ⚠️Limited | ✅ |
| ⚠️Private | ➕ Add-On | ✅ | ✅ |
| ⚠️Private | ⚠️ Varies | ⚠️Capped | ⚠️Varies |
| ⚠️ NFIP | ➕ Add-On | ✅ | ✅ |
| ⚠️NFIP | ➕ Add-On | ✅ | ✅ |
| ⚠️Private | ⚠️ Capped | ✅ | ⚠️by Age |
Wind and hail cause 32% of claims, averaging $15K per payout, while winter storms account for 21%, averaging $24K.
Wildfires account for 13% of claims but have the highest average payout. Homeowners in wildfire-prone areas will have higher premiums and may have exclusions and wildfire restrictions on their policies. Read More: How to File a Wildfire Home Insurance Claim
Top providers Amica and Chubb include wildfire coverage, but Liberty Mutual, Allstate, and Progressive cap or limit coverage.
5 Most Common Home Insurance Risks in Montana| Risk | Claims | Payout | Cost | Area |
|---|---|---|---|---|
| #1 Wind & Hail | 32% | $15K | Low | Eastern Plains |
| #2 Winter Storms | 21% | $24K | Moderate | Mountainous |
| #3 Wildfire | 13% | $110K | Highest | Western |
| #4 Flooding | 9% | $46K | High | River Valleys |
| #5 Earthquake | 2% | $95K | Highest | Southwest |
Homeowners insurance options in Montana likely won’t include flood protection. You’ll need to buy separate coverage through the NFIP or private insurers, depending on the company.
Standard policies usually exclude earthquake damage, too, which has a high $95K average payout, even though it only accounts for 2% of claims in the state.
When choosing home insurance, match your dwelling limit to rebuilding costs and confirm your policy covers the property risks most common in your area.
Travis Thompson Licensed Insurance Agent
Check out home insurance coverage options before you buy so you know which risks are included and which require added protection.
Compare home insurance coverage with our free tool to find policies that fit your property and budget.
Common Types of Homeowners Policies in Montana
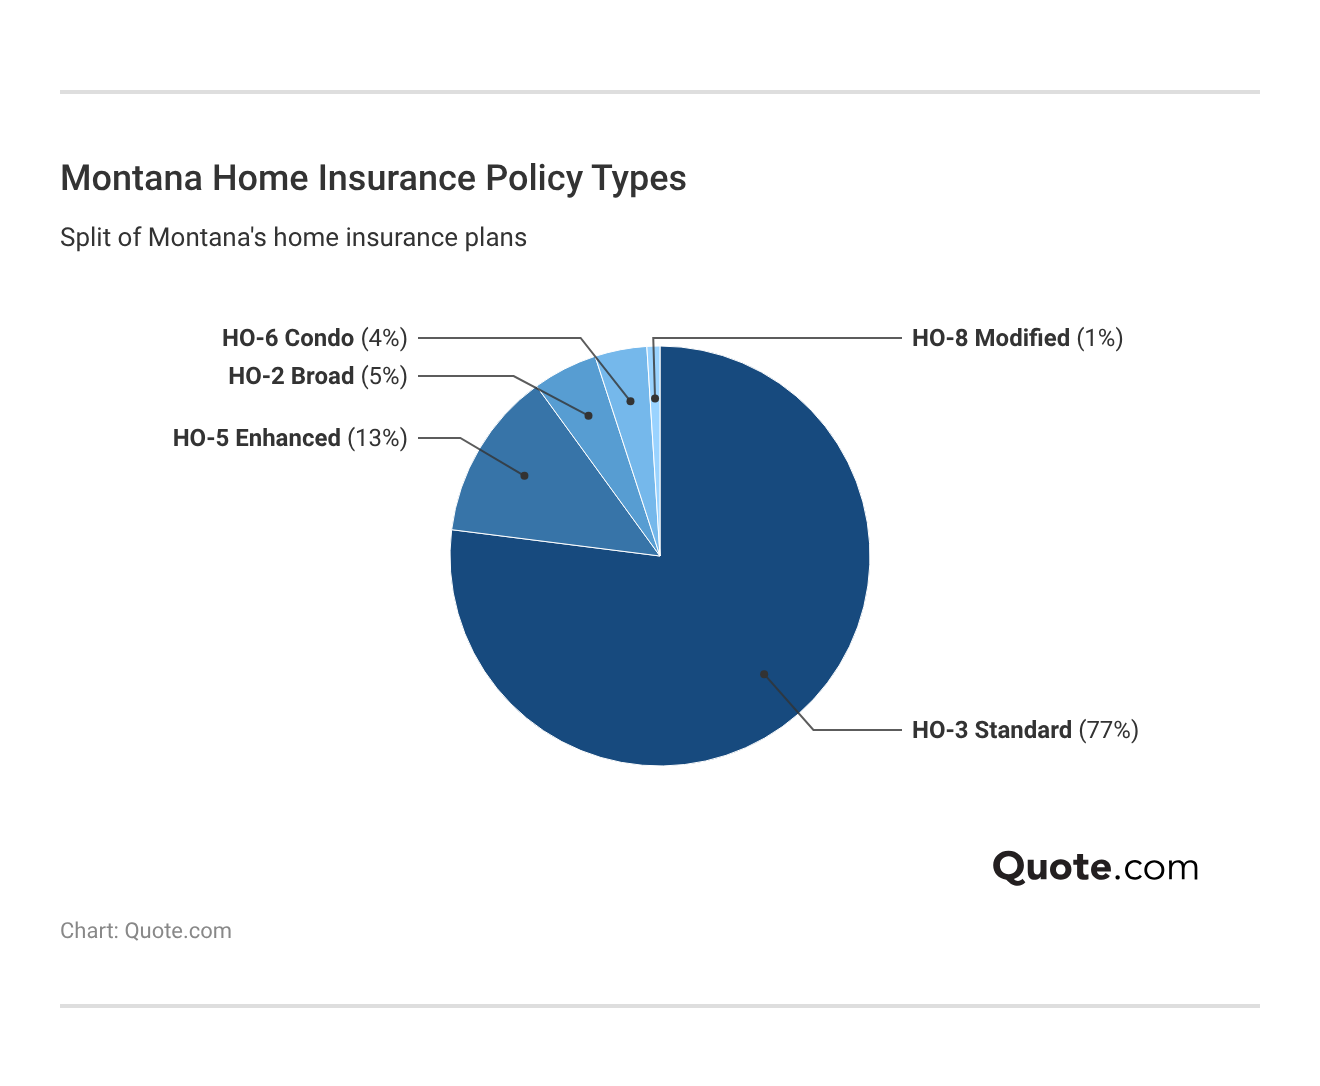
HO-3 policies are the most common type of homeowners insurance in Montana, making up 77% of the plans shown. They cover the home broadly while protecting belongings against listed risks.
HO-5 policies account for another 13% and typically provide broader protection for both the home and personal property.
HO-2 policies make up 5%, while HO-6 condo policies represent 4% and are designed for condo owners who need coverage for their unit, belongings, and liability.
HO-8 policies make up just 1% and are generally intended for older homes where rebuilding costs may be difficult to match with the property’s market value.
When Insurers Limit or Decline Coverage in Montana
Even among the top homeowners insurance carriers in Montana, coverage limits can differ based on the property, roof age and inspection requirements, and type of risk.
Amica and Chubb allow roofs up to 25 years old, while most companies shown set a 20-year limit, and Farmers and Liberty Mutual cap roof age at 15 years.
Montana Home Insurance Restrictions by Company| Company | Earthquake | Inspection? | Roof Limit | Winter Freeze |
|---|---|---|---|---|
| ➕Add-On | ⚠️by Age | 20 Yrs | ⚠️Capped |
| ➕Add-On | ⚠️by Review | 25 Yrs | ⚠️by Review |
| ➕Add-On | ⚠️by Value | 25 Yrs | ⚠️Limited |
| ➕Add-On | ⚠️by Age | 15 Yrs | ⚠️by Condition |
| ➕Add-On | ⚠️by Age | 15 Yrs | ⚠️Capped |
| ⚠️by Value | ⚠️by Review | 20 Yrs | ⚠️by Review |
| ⚠️Capped | ⚠️Varies | 20 Yrs | ⚠️Varies |
| ➕Add-On | ⚠️by Age | 20 Yrs | ⚠️by Condition |
| ➕Add-On | ⚠️by Age | 20 Yrs | ⚠️Capped |
| ⚠️Capped | ⚠️by Review | 20 Yrs | ⚠️by Review |
Earthquake coverage is available as an add-on from Allstate, Amica, Chubb, Farmers, Liberty Mutual, Safeco, and State Farm. Inspection rules may depend on the home’s age, value, or individual review.
When to shop for new homeowners insurance in Montana may depend on changes to your property or current coverage. Owners of older homes should pay particular attention to roof limits, inspections, and winter freeze restrictions when reviewing another insurer.
Top 10 Montana Home Insurance Providers
Companies with a larger share are more popular among Montana homeowners, but consider market share alongside financial ratings and customer satisfaction.
Our top two picks, Amica and Chubb, don’t even make up 5% of the Montana market but still compete closely with State Farm and Liberty Mutual on financial strength, claims, and customer service.
10 Largest Home Insurance Companies in Montana| Company | Market Share | Policy Count | Premiums Written | Financial Rating |
|---|---|---|---|---|
| 23.4% | 60K | $167.1M | A+ |
| 16.3% | 42K | $116.3M | A |
| 13.0% | 33K | $92.8M | A |
 | 8.3% | 21K | $59.4M | A++ |
| 7.5% | 19K | $53.9M | A++ |
 | 5.0% | 13K | $35.5M | B++ |
| 3.0% | 8K | $21.8M | A++ |
| 3.0% | 8K | $21.7M | A+ |
| 2.8% | 7K | $20.2M | A |
 | 2.2% | 6K | $15.6M | A- |
A company with fewer Montana policies may still have strong financial backing and coverage options that better fit a particular home.
USAA and Travelers also have smaller market shares at 8.3% and 7.5%, but both carry A++ financial ratings.
Insurers price risks differently in Montana. Comparing several companies helps you find competitive rates while making sure your policy has the right coverage for the hazards your home actually faces.
Dani Best Licensed Insurance Producer
When you compare home insurance quotes, look closely at limits and exclusions for wildfire, wind, hail, and winter damage.
Claims service matters, too. A lower premium may save money upfront, but responsive claims handling becomes important when your home needs repairs after a covered loss.
See More: Best Insurance Companies for Claims Handling
#1 – Amica: Top Pick Overall
Pros
- Strong Claims Satisfaction: Amica leads the Montana comparison with a 773 out of 1,000 claims satisfaction score and a low complaint level.
- Big Bundle Savings: Eligible homeowners can save up to 30% by bundling home and auto coverage, the second-highest discount shown.
- Older Roof Eligibility: Amica accepts roofs up to 25 years old, while most competitors set a 20-year limit. Read more: Amica Insurance Review
Cons
- Higher Monthly Rate: Amica charges $218 per month for $200K in dwelling coverage, compared with $185 from State Farm and $193 from Travelers.
- Freeze Coverage Review: Winter freeze protection is reviewed individually, so Montana homeowners should confirm the terms before choosing a policy.
#2 – Chubb: Best for Luxury Homes
Pros
- Above-Average Claims Handling: Chubb ranks second with a 744 out of 1,000 claims satisfaction score and a low complaint level.
- High Financial Rating: Chubb carries an A++ AM Best rating, the highest financial rating shown in the Montana market-share table.
- Older Roof Flexibility: Chubb accepts roofs up to 25 years old. Learn more: Best Home Insurance for High-Value Properties
Cons
- Higher Coverage Costs: Chubb charges $246 per month for $200K in dwelling coverage and $469 for $500K, making it one of the more expensive options shown.
- Smaller Montana Presence: Chubb holds just 3% of Montana’s home insurance market, much less than State Farm at 23.4% and Liberty Mutual at 16.3%.
#3 – Liberty Mutual: Best for Policy Discounts
Pros
- Multiple Discount Options: Liberty Mutual offers savings for bundling, newer homes, remaining claims-free, and qualifying security features.
- Large Montana Presence: Liberty Mutual holds 16.3% of Montana’s home insurance market, the second-largest share in the comparison.
- Storm Coverage Available: Wind and hail protection is available, covering 32% of claims shown. More details here: Liberty Mutual Insurance Review
Cons
- More Complaints in Montana: Liberty Mutual receives a high complaint designation, while Amica, Chubb, Travelers, and Farmers are rated low.
- Stricter Roof Limit: Its 15-year roof limit is shorter than the 20- or 25-year limits listed by several competitors.
#4 – Nationwide: Best for Home Security Savings
Pros
- Competitive Starting Rate: Nationwide charges $205 per month for $200K in dwelling coverage, less than Amica, Liberty Mutual, Chubb, Allstate, and Safeco.
- Covers Multiple Property Risks: Wildfire, wind, and hail protection are listed as available, covering two significant Montana property risks.
- Home Security Savings: Qualifying home security systems earn up to 6% off, which is lower than Safeco but comes with better customer service. Find More: Nationwide Review
Cons
- More Customer Complaints: Nationwide receives a high complaint designation, while several other Montana insurers in the comparison have low complaint levels.
- Smaller Bundle Discount: Its 13% home and auto discount trails Amica, State Farm, Progressive, and Farmers.
#5 – Progressive: Best for Online Quotes
Pros
- Convenient Online Quotes: Progressive makes it easy to request and review insurance quotes online. A closer look: Progressive Insurance Review
- Competitive Home Premiums: Progressive charges $198 per month for $200K in dwelling coverage, the third-lowest rate among the insurers compared.
- Strong Bundle Savings: Qualifying homeowners can save up to 25% by bundling home and auto insurance, one of the larger discounts shown.
Cons
- Montana Coverage Varies: Flood, sewer, wildfire, and wind and hail protection have varying limits or availability, so homeowners should check their specific policy.
- Lower Claims Score: Progressive earns 704 out of 1,000 for claims satisfaction, trailing Amica, Chubb, Liberty Mutual, and Nationwide in the Montana ranking.
#6 – Travelers: Best for Safety Features
Pros
- Lower Coverage Price: Travelers charges $193 per month for $200K in dwelling coverage, second only to State Farm among the companies shown.
- Security Feature Savings: Homeowners with qualifying security features can receive a 6% discount, along with up to 12% for remaining claims-free.
- Strong Financial Rating: Travelers carries an A++ AM Best rating and receives a low complaint designation. Find out more: Travelers Insurance Review
Cons
- Age-Based Storm Coverage: Wind and hail protection may depend on the home’s age, so owners of older properties should check the policy terms.
- Capped Earthquake Coverage: Earthquake protection is capped, which may limit coverage for homeowners seeking additional protection.
#7 – Farmers: Best for Custom Policies
Pros
- Flexible Policy Coverage: Farmers offers options homeowners can adjust based on their property and priorities. See our article: Farmers Insurance Review
- Low Complaint Level: Farmers receives a low complaint designation, putting it ahead of several competitors on this measure.
- Big Savings When You Bundle: Qualifying homeowners can save up to 20% by combining their home and auto policies.
Cons
- Higher Rates for High-Risk Homes: Farmers has the highest wildfire rate at $356 per month and the highest wind and hail rate at $319.
- Restrictive Roof Limit: Farmers limits eligible roofs to 15 years, compared with 20 years for many competitors and 25 years for Amica and Chubb.
#8 – State Farm: Best for Local Agents
Pros
- Lowest Rates for More Dwelling Coverage: State Farm has the lowest monthly rates at every policy level shown, from $185 for $200K to $323 for $500K in coverage.
- Strong Montana Presence: State Farm holds 23.4% of Montana’s home insurance market, representing 60,000 policies. Keep Reading: State Farm Insurance Review
- Bundle Savings: Home and auto bundling offers up to 26% off, with estimated savings of $577.
Cons
- Mid-Level Complaints: State Farm receives a mid-level complaint designation, while several competing insurers are rated low.
- Capped Freeze Coverage: Winter freeze protection is capped, so homeowners should check the limit before relying on it for cold-weather damage.
#9 – Allstate: Best for New Homes
Pros
- New-Home Savings: Qualifying newer homes receive up to 9% off, tied with Chubb and Travelers for the highest new-home discount shown.
- Claims-Free Discount: Homeowners who remain claims-free may qualify for savings of up to 12%.
- Several Ways to Save: Allstate offers discounts for bundling, newer homes, claims-free histories, and home security features. Related: Allstate Insurance Review
Cons
- Limited Wildfire Coverage: Wildfire protection is listed as limited, which is worth checking for homes in higher-risk areas of Montana.
- Higher Complaint Level: Allstate receives a high complaint designation, while several insurers in the Montana ranking have low complaint levels.
#10 – Safeco: Best for Digital Tools
Pros
- Strong Security Discount: Safeco offers a 10% home security discount, the highest among insurers compared. What to know: Safeco Insurance Review
- Key Coverage for Montana Hazards: Wildfire, wind, and hail protection are all listed as available for qualifying policies.
- Useful Digital Services: Safeco offers online policy management, digital billing, and claims tools that let homeowners handle common account tasks without calling an agent.
Cons
- Lower Claims Score: Safeco has a 666 out of 1,000 claims satisfaction score, the lowest among the Montana companies ranked.
- Condition-Based Freeze Coverage: Winter freeze protection depends on the property’s condition, so eligibility may vary by home.
Free Home Insurance Comparison
Compare Quotes From Top Companies and Save
Finding the Right Montana Home Insurance
Our top picks for the best home insurance in Montana are Amica, Chubb, and Liberty Mutual, each standing out for different coverage and service advantages.
Amica is the best-ranked home insurance company in Montana, with a 773 out of 1,000 claims satisfaction score and a low complaint level.
State Farm has the cheapest home insurance in Montana across the dwelling coverage levels shown, starting at $185 per month for $200K in coverage.
Compare Montana home insurance using the same dwelling limit and deductible, and pay particular attention to wildfire, wind and hail, winter storm, flood, and earthquake protection before choosing a policy.
Before you buy, compare home insurance quotes online to see what different Montana insurers charge.
Frequently Asked Questions
Which home insurance company is best in Montana?
Amica ranks first for Montana homeowners insurance coverage, with a claims satisfaction score of 773 out of 1,000 and a low complaint level. Chubb ranks second and stands out for luxury homes, while Liberty Mutual takes third place for its policy discounts.
What is the average cost of home insurance in Montana?
Home insurance premiums vary by coverage, insurer, location, deductible, credit, and property risks. The average Montana home insurance quote is $214 per month, compared with $167 nationally. Monthly rates for $200K in dwelling coverage range from $185 with State Farm to $246 with Chubb. At $500K, they range from $323 to $521 a month.
How much should Montana home insurance cost on a $400,000 house?
Home insurance for a $400,000 house in Montana averages about $339 per month in our data, based on approximately $462,000 in dwelling coverage. The actual cost depends on rebuilding expenses, location, deductible, credit, property risks, and the insurance company. Learn More: Replacement Cost vs. Actual Cash Value
How much are Montana homeowners insurance premiums expected to increase?
Housing market projections show that Montana home insurance premiums may continue rising by 1.6%. Actual renewal increases will vary by insurer, property, coverage, and location.
What type of insurance protection is required in Montana?
Drivers in Montana must carry car insurance, but state law generally does not require home insurance. If you have a home loan, mortgage lenders typically require you to maintain coverage on financed homes. If your home insurance is getting expensive, shop affordable home insurance coverage and see what else is available.
What are the worst Montana insurance companies for homeowners policies?
Among the top home insurance companies in Montana, Safeco has the lowest J.D. Power claims satisfaction score of 666 out of 1,000. Allstate follows at 672, and State Farm at 690.
How do home and rebuilding costs affect Montana homeowners insurance?
A home’s market value does not determine how much insurance it needs. Homeowners insurance coverage levels should reflect estimated rebuilding costs, which affect the dwelling limit and premium. A $300K home has about $338K in coverage at $278 per month, while a $500K home has $572K in coverage at $398 per month.
Is bundling home and auto insurance cheaper in Montana?
Bundling may lower the combined cost of home and car insurance in Montana, but savings vary by insurer. American Family offers the largest discount shown at 40%, with estimated savings of $1,051. Amica offers 30% with $785 in estimated savings, while State Farm offers 26% with $577. Compare the bundled price with separate policies to see which option costs less.
What is the fine for not having homeowners insurance in Montana?
Montana does not have a state fine for going without homeowners insurance. Homeowners with a mortgage may still be required by their lender to maintain coverage. Check out our guide for more mortgage requirements and insurance rules: Is home insurance required?
Does Montana home insurance offer options for households with lower incomes?
There is no low-income homeowners insurance program in Montana. If you need to reduce your premiums, review available discounts for bundling, remaining claim-free, owning a new home, or installing qualifying home security features. Compare home insurance quotes from multiple companies for lower rates.
How does renters insurance differ from homeowners insurance in Montana?
How do other insurance costs affect a Montana homeowner’s budget?
Related Articles
-
Apr 2026

Best Home Insurance for Seniors in 2026: Top Low-Cost Plans
-
Aug 2026

Best Insurance for Vacation Homes: Top Companies & Value (2026)
-
Oct 2025
Best Home Insurance for High-Value Properties in 2026
-
Sep 2026
Best Home Insurance in Massachusetts for 2026
-
Aug 2026
Best Home Insurance in Rhode Island for 2026
-
Jun 2026
Best Home Insurance for First-Time Buyers: Top-Rated Coverage (2026)
Get a FREE Quote in Minutes
Insurance rates change constantly — we help you stay ahead by making it easy to compare top options and save.